
ADT (ADT) Stock May Be Cheap Despite Its Earnings Focus
ADT Inc. has seen its share price fall sharply over the past year, which naturally puts the focus back on what investors are paying for its earnings today. With the stock now trading around US$6.34, the key issue is whether that level still lines up with what the business is currently generating in profit.
- The share price has declined 23.8% over the past year, which puts extra weight on the question of how closely ADT's valuation tracks its earnings power.
- The business relies heavily on recurring service revenue and ongoing monitoring contracts, which can shape how consistently earnings support the current share price over time.
- There is a second opinion on ADT worth weighing. See what analysts think ADT's shares could be worth.
The stock's next move may depend on whether ADT's present earnings profile is enough to underpin the price investors are being asked to pay today.
If you want a broader starting point for ideas around companies where valuation is closely tied to earnings strength, it can be useful to look through 30 high quality undervalued stocks.
Is ADT Still Cheap on Earnings?
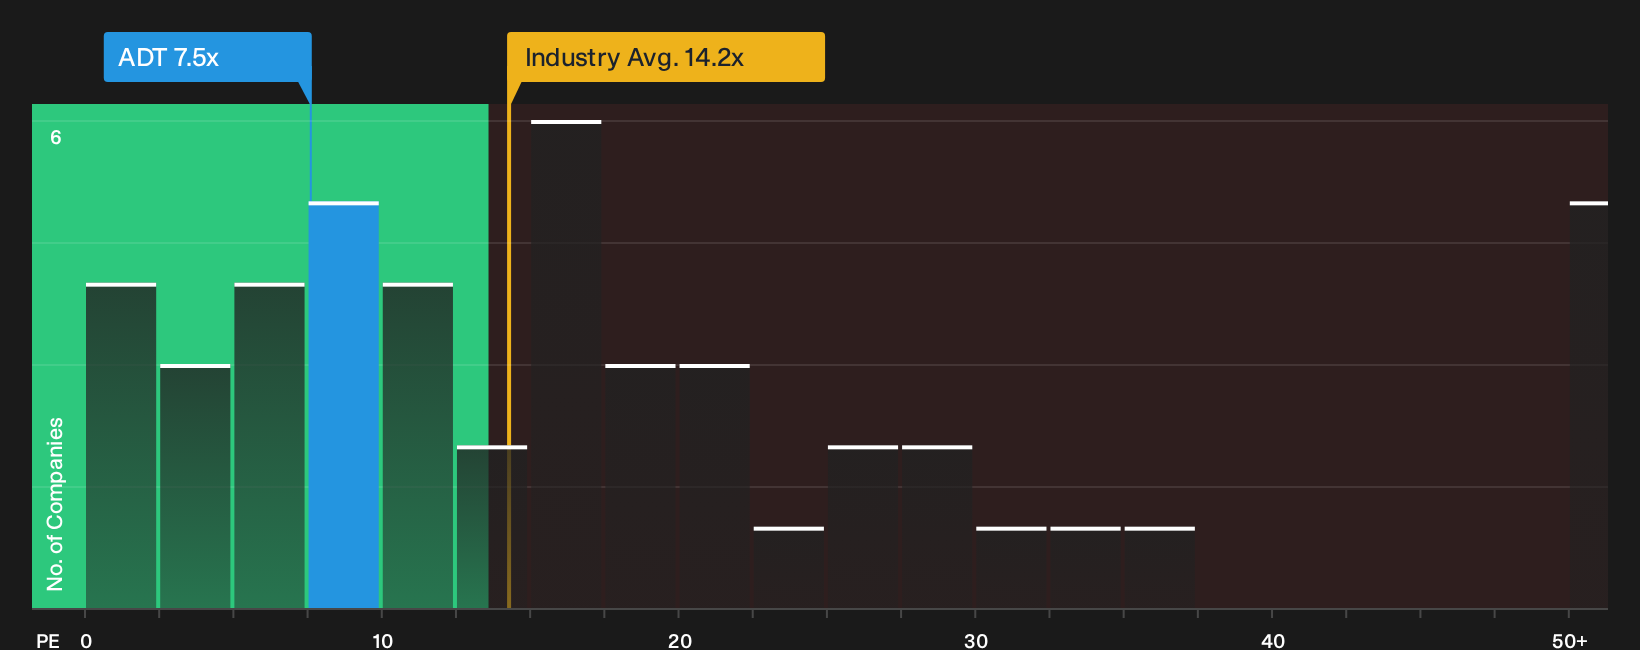
The P/E ratio fits ADT because the business is built around recurring earnings from monitoring services, which tend to be the main anchor for what investors are willing to pay. At the current share price, ADT trades on a P/E of 7.5x, compared with about 14.2x for the wider Consumer Services industry and roughly 18.3x for peers in its reference group. That gap means the market is attaching a lower earnings multiple to ADT than to many similar businesses.
The Fair Ratio model, which factors in ADT's own margins, scale and risk profile rather than just raw sector averages, points to a higher multiple than the one implied by the current share price. That places the stock in undervalued territory on this framework, with investors paying less for each dollar of earnings than the model would usually suggest for a company with these characteristics. Explore the numbers behind ADT's P/E valuation.
The ADT Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where ADT's valuation question leaves off by spelling out which paths for ADT's growth, margins and earnings would need to play out for the stock to look meaningfully higher or lower than today’s price. Each story on the Community page links its number to a clear view on how growth trends, profitability and risk might shift, giving you something concrete to update as fresh information comes through.
One of the top community narratives on ADT: 23% undervalued
"The strategic partnerships with Google and State Farm (although the latter's program was technically halted) represent a highly defensible moat..."
Discover why this Narrative puts ADT at 23% undervalued.
One more angle on ADT that could change how you see the stock
ADT's current P/E tells you what the market is paying for earnings today, but the projections that professional analysts map out for the next few years offer a different lens on what might be baked into the price. Explore where analysts expect ADT to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com