
Prada (SEHK:1913) Gets A New Vitkac Platform As Undervalued Narrative Holds
Prada (SEHK:1913) just gained fresh shelf space at Vitkac, a Warsaw based luxury retailer known for its tightly curated mix of global designers, expanding the fashion group’s reach to international customers.
For investors watching the ticker, Prada’s 1 day share price return of 2.03% comes after a year to date share price decline of 14.68% and a 1 year total shareholder return that is down 15.39%, suggesting weaker momentum despite recent distribution wins such as Vitkac.
Compare Prada’s new Vitkac shelf space with other consumer brands that analysts flag as potential breakout candidates by scanning 620 high quality undiscovered gems in the global luxury and premium goods space.
Prada’s move at Vitkac can be read in two ways. Either the share price is catching up with an improving business profile, or sentiment is briefly bouncing while the fundamentals point elsewhere.
Most Popular Narrative: 23.5% Undervalued
On the narrative view, Prada’s fair value of HK$49.86 sits well above the last close at HK$38.14. This frames today’s Vitkac placement as one small piece of a wider rerating story grounded in brand, operations, and capital allocation.
Miu Miu's significant space expansion, robust growth across all geographies, and increasing focus on higher-margin categories (like leather goods) are expected to boost the group's volume, sales mix, and profitability over the next several years.
See why 6 investors see Prada as 24% undervalued.
Result: Fair Value of HK$49.86 (UNDERVALUED)
Still, the Prada story only holds if tourism driven demand, along with rising marketing and digital costs, does not erode the earnings profile analysts are banking on.
Find out about the key risks to this Prada narrative.
Another View: Prada On Earnings Multiples
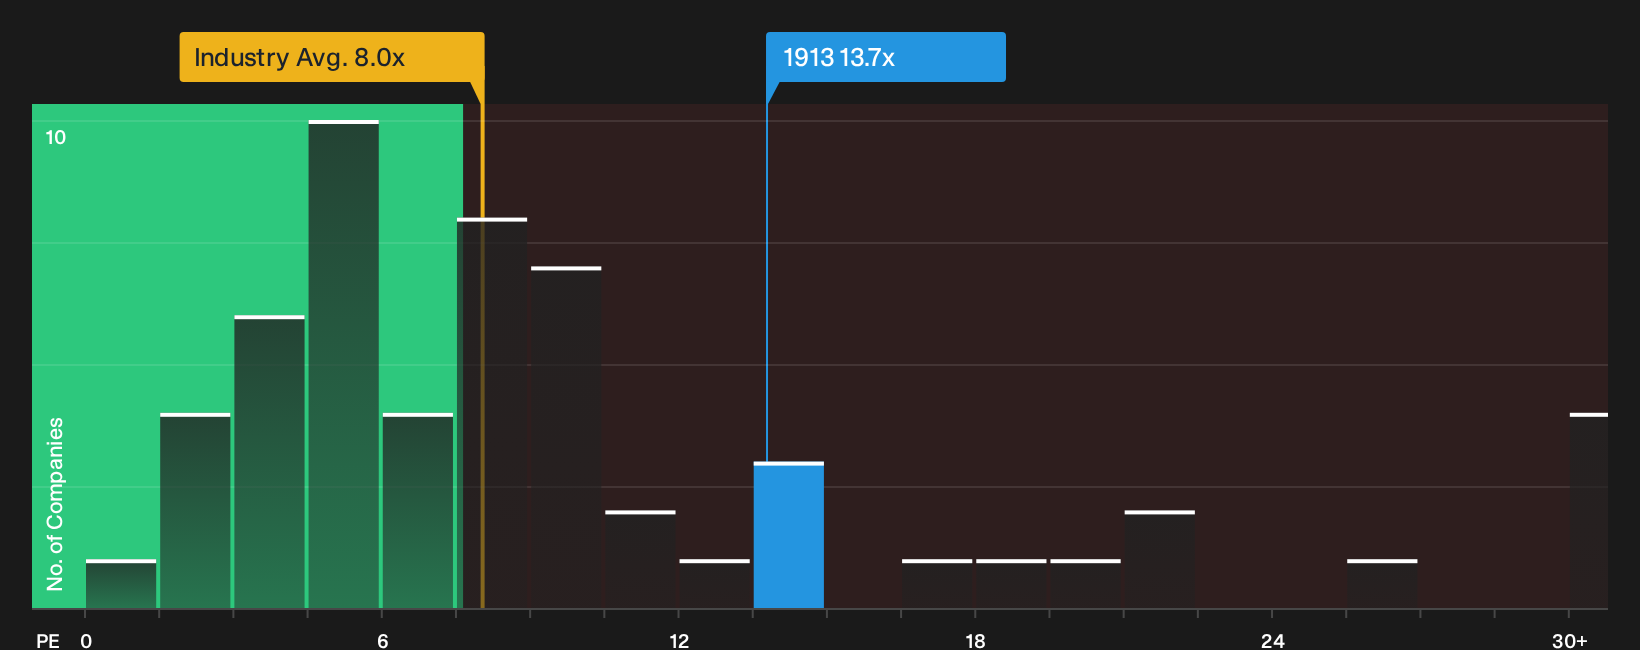
The first take presents Prada as 23.5% undervalued against a fair value of HK$49.86, yet the earnings multiple shows a tougher picture. The stock trades on a P/E of 13.7x versus 8x for the Hong Kong luxury sector and a fair ratio of 10.1x.
That gap means buyers today are paying a richer price than both peers and the fair ratio suggest, while the DCF and analyst targets point to upside. Which crowd do you trust more: the cash flow modellers or the earnings multiple comparisons?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Prada so far. If you want to move fast and base your view on the underlying numbers instead of the headline, weigh up the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Prada?
Prada’s setup may interest you, but real edge comes from lining it up against other opportunities that fit different risk profiles and return goals.
Use the Simply Wall Street Screener to compare fresh ideas side by side, so you do not miss something that fits your plan better.
- Target potential mispricing and look for quality businesses trading below estimated value by scanning 173 high quality undervalued stocks.
- Build a steadier income stream and review payout strength by exploring the 161 dividend fortresses.
- Limit unexpected setbacks and focus on sturdier balance sheets by working through the 229 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com