
ExlService Holdings (EXLS) Refreshes Its Brand, Is The Valuation Gap Too Wide?
ExlService Holdings (EXLS) is back in focus after marking its 20th year as a listed company and launching its refreshed “Go Beyond” brand, which is closely tied to its data and AI positioning.
Against that backdrop, ExlService Holdings has been volatile, with the share price down over the past month and year to date, yet showing a strong 90 day share price return. Longer term total shareholder returns over three and five years remain positive, suggesting earlier momentum is now being reassessed after recent gains.
Compare ExlService Holdings' data and AI story with other potential breakouts by scanning our hand picked list of 38 profitable AI stocks that aren't just burning cash for your watchlist.
For ExlService Holdings, a 38.1% gain over 90 days alongside a 20.2% decline over the past year leaves a simple puzzle: Is the price now tracking business progress or a sharp swing in sentiment?
Most Popular Narrative: 89% Overvalued
At a last close of $34.83 against a narrative fair value of $18.40, ExlService Holdings is framed as materially overpriced according to Esteban, who focuses on how its AI push has translated into financial quality rather than just headline growth.
Offshore analytics and managed-operations provider that runs mission-critical claims, underwriting, payment-integrity and finance workflows for large insurers, healthcare payers and banks, and is repositioning that base into data and AI-led delivery. Roughly 53% of revenue is recurring, embedded operations protected by 12 to 30 months of transition friction, which is enough to make permanent capital loss unlikely at a low entry price. It is not enough to underwrite compounding: five years of mix shift into AI-led work has produced no gross margin expansion, contracts are terminable without cause, and the AI work is re-won through pilots rather than inherited. The thesis is therefore a price thesis, not a quality thesis
See why 3 investors see ExlService Holdings as 89% overvalued.
Result: Fair Value of $18.40 (OVERVALUED)
Still, a revenue base concentrated in the US and top clients, along with contracts that can be terminated without cause, could unsettle the ExlService Holdings overvaluation case.
Find out about the key risks to this ExlService Holdings narrative.
Another View on ExlService Holdings' Valuation
Esteban sees ExlService Holdings as 89% overvalued at $34.83 versus a narrative fair value of $18.40. Our DCF model points in the opposite direction. It estimates future cash flows at $81.83 per share, which implies the current quote trades at a steep discount instead.
These are two models with two very different signals. The question is which set of assumptions you trust more when real cash flows start to show up in the numbers, and which one you want to lean on for your own process, Look into how the SWS DCF model arrives at its fair value.
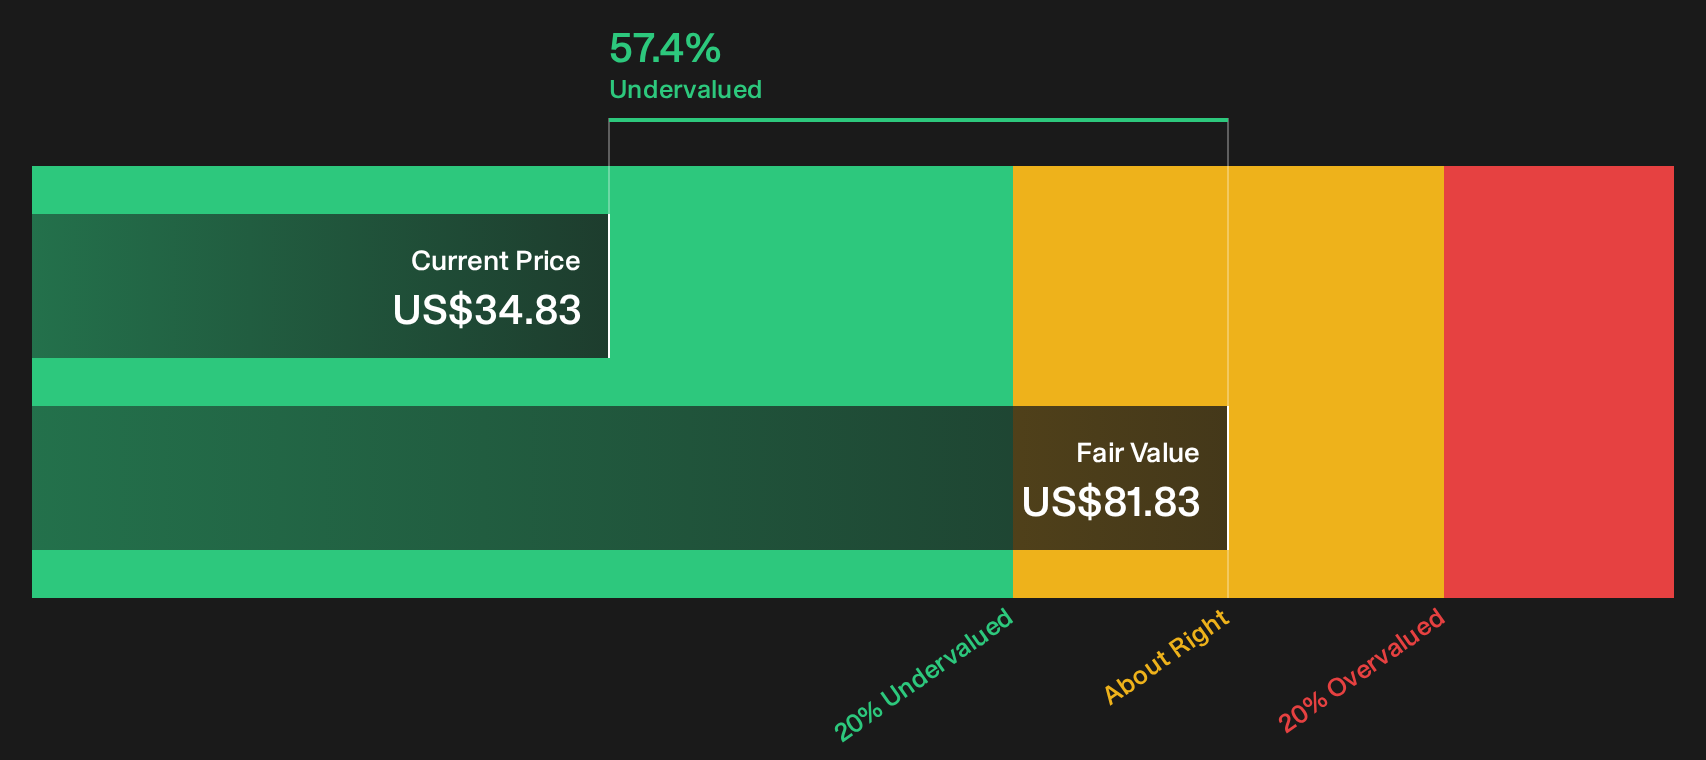
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ExlService Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The estimates point in opposite directions, so sentiment is clearly split. Act while the data is fresh and weigh the upside for yourself with 4 key rewards
Looking for more ExlService Holdings investment ideas?
If ExlService Holdings has sharpened your focus on pricing and quality, do not stop here. Broaden your watchlist now before the best ideas move away.
- Target stronger value by reviewing companies that score well on quality and valuation through the 30 high quality undervalued stocks.
- Shift toward durability by scanning a list of solid balance sheet and fundamentals (23 results) that can better handle shocks and funding pressures.
- Spot under-the-radar potential by checking a focused batch of 16 high quality undiscovered gems before they appear on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com