
New Kansas City Hospital Could Matter For Universal Health Services Stock
- Universal Health Services recently opened Three Trails Behavioral Hospital in Independence, Missouri, its first Kansas City area facility with 120 inpatient beds and outpatient programs.
- This new behavioral hospital adds physical capacity that can connect with Universal Health Services’ existing outpatient and virtual services, reinforcing the broader behavioral health strategy management has been building.
- We will now look at how Universal Health Services’ new 120 bed Three Trails facility could influence the broader investment narrative.
Examine how Universal Health Services fits into the broader hospital and behavioral health landscape by reviewing a curated set of list of solid balance sheet and fundamentals (23 results).
Universal Health Services Investment Narrative Recap
To own Universal Health Services, you need to believe the hospital and behavioral platform can keep offsetting policy and liability headwinds with execution. In the near term, the key swing factor is whether new capacity, outpatient mix and AI tools can counter expected declines in earnings of about 2.3% a year and pressure from Medicaid and ACA related reimbursement.
The Three Trails opening in Missouri adds more behavioral beds and a new intake point, but on its own it does not change the main risk. Projected cuts to Medicaid supplemental payments and rising liability expenses, running around US$175 million to US$200 million a year, still appear to be the key pressure points.
Among the earlier developments, the buildout of Universal Health Services' outpatient and virtual behavioral network, including Talkspace and Thousand Branches, ties most directly into Three Trails. The new hospital gives that outpatient system another escalation path for higher acuity patients, which matters if management wants virtual and community volumes to feed into inpatient occupancy.
The Talkspace acquisition, with roughly US$250 million of outpatient behavioral revenue and access to 6,000 therapists, is central to that plan. The main execution risk is that integration, referral flows and AI supported efficiencies do not scale fast enough to offset Medicaid payment cuts and liability cost growth. That scenario would leave the expanded bed base underutilized and earnings under pressure.
Universal Health Services' consensus narrative points to revenues of US$21.0b and earnings of US$1.3b by 2029, based on analysts assuming 5.1% yearly revenue growth and earnings moving from US$1.5b today to US$1.3b, which is a decline of US$0.2b.
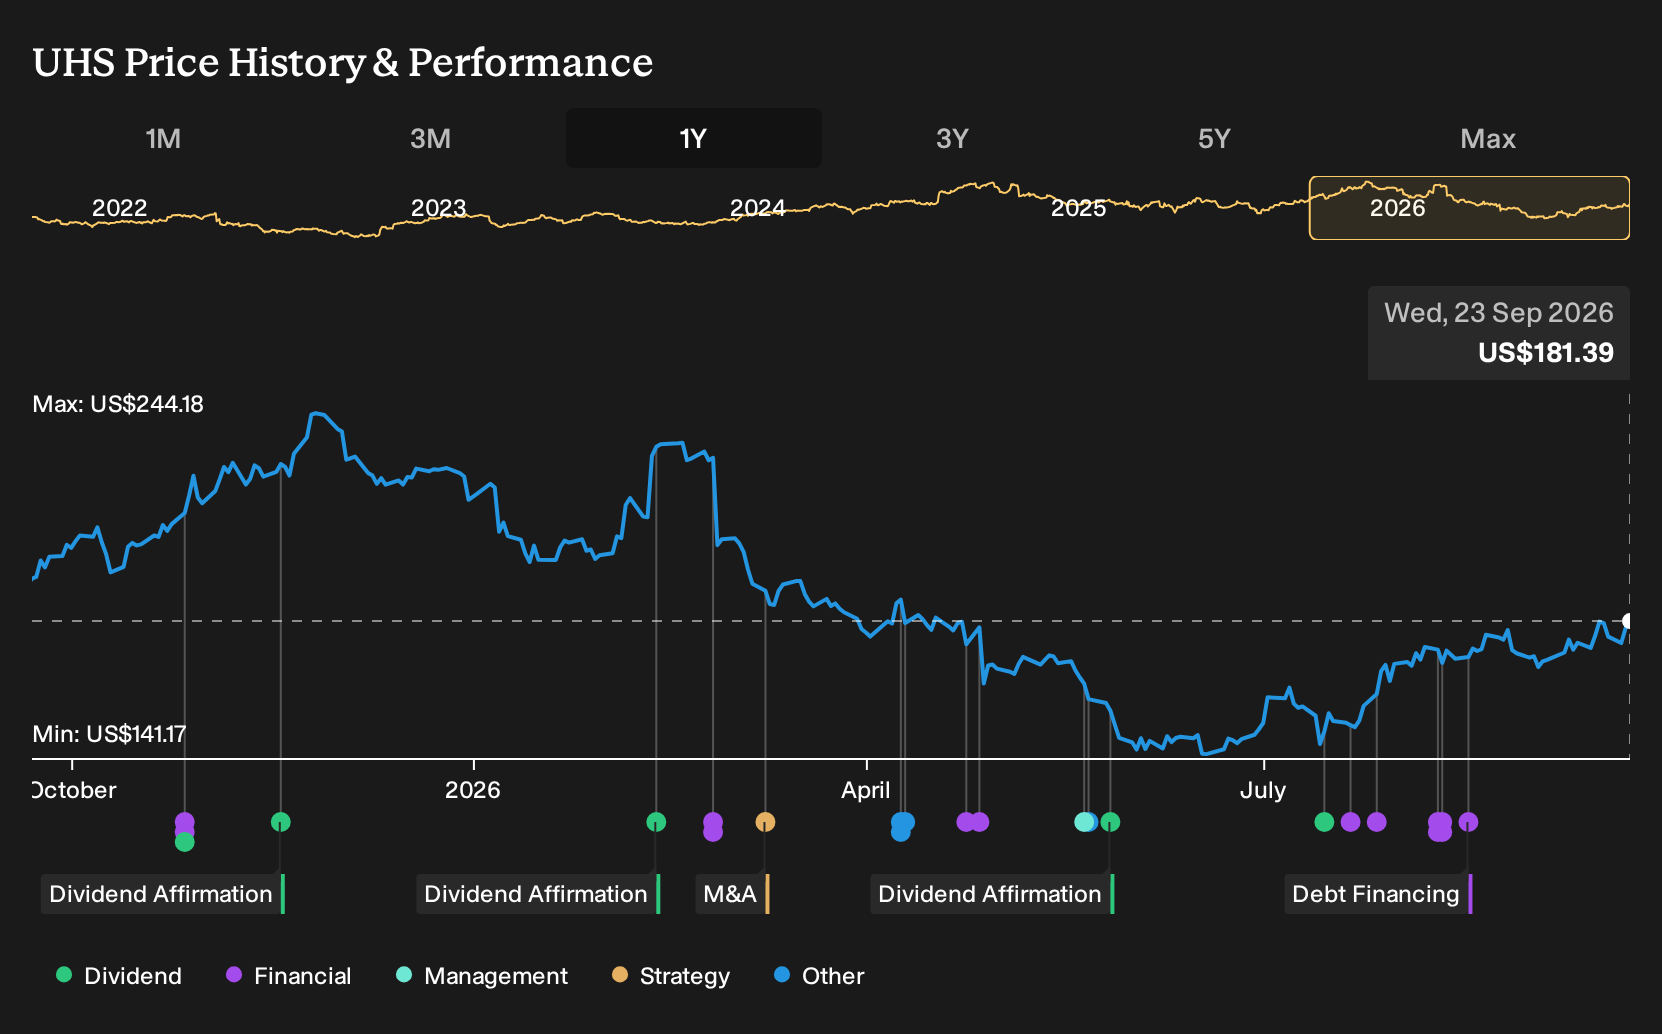
Discover how Universal Health Services' fair value indicates a 7% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Universal Health Services’ share repurchases as the bigger swing factor than reimbursement risk. They were already modeling revenue of about US$21.7b and earnings near US$1.5b by 2029 before Three Trails. You can treat this new hospital as a potential test of whether that upbeat view gains traction or gets challenged.
Explore 4 other Universal Health Services fair value estimates, including one that suggests as much as 259% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Health Services research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Health Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Health Services' overall financial health at a glance.
Looking for more Universal Health Services style investment ideas?
If Universal Health Services has you thinking about quality, resilience and cash generation, it can help to scan a broader watchlist built around the same themes using the Simply Wall St Screener.
- For investors who want quality at a reasonable price, filter for companies with strong fundamentals and potential mispricing using the 30 high quality undervalued stocks.
- If reliability matters most to you, focus on businesses that pair healthy finances with lower risk scores through the 31 resilient stocks with low risk scores.
- For those hunting for less crowded ideas, surface lesser known businesses with solid underlying metrics via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com