
How Investors Are Reacting To Murata Manufacturing (TSE:6981) AI Wearables Partnership
- On 21 September 2026, CIPRA.ai Inc. announced a collaboration with Murata Manufacturing to explore AI-powered wearable devices for continuous chronic disease monitoring using Murata’s sensing hardware and CIPRA.ai’s digital twin platform.
- The project pushes Murata Manufacturing further into healthcare technology by tying its sensor expertise to recurring software-led disease management tools that target value-based care and rural health use cases.
- We will now look at how Murata Manufacturing’s investment narrative could shift as it leans into AI-driven chronic disease wearables.
Scan how Murata Manufacturing’s healthcare pivot compares with other AI-focused hardware plays by reviewing our hand picked list of 85 AI infrastructure stocks.
What Is Murata Manufacturing's Investment Narrative?
To own Murata Manufacturing, you need to believe this is more than a parts supplier. It is a high margin component specialist with ¥1.92b in revenue and ¥265.49b in net income that is trying to extend its know how into AI wearables and healthcare software. The CIPRA.ai tie up fits that story. It links Murata sensors to a software platform without forcing the company to build all of that capability in house, which keeps capital needs contained while it tests demand.
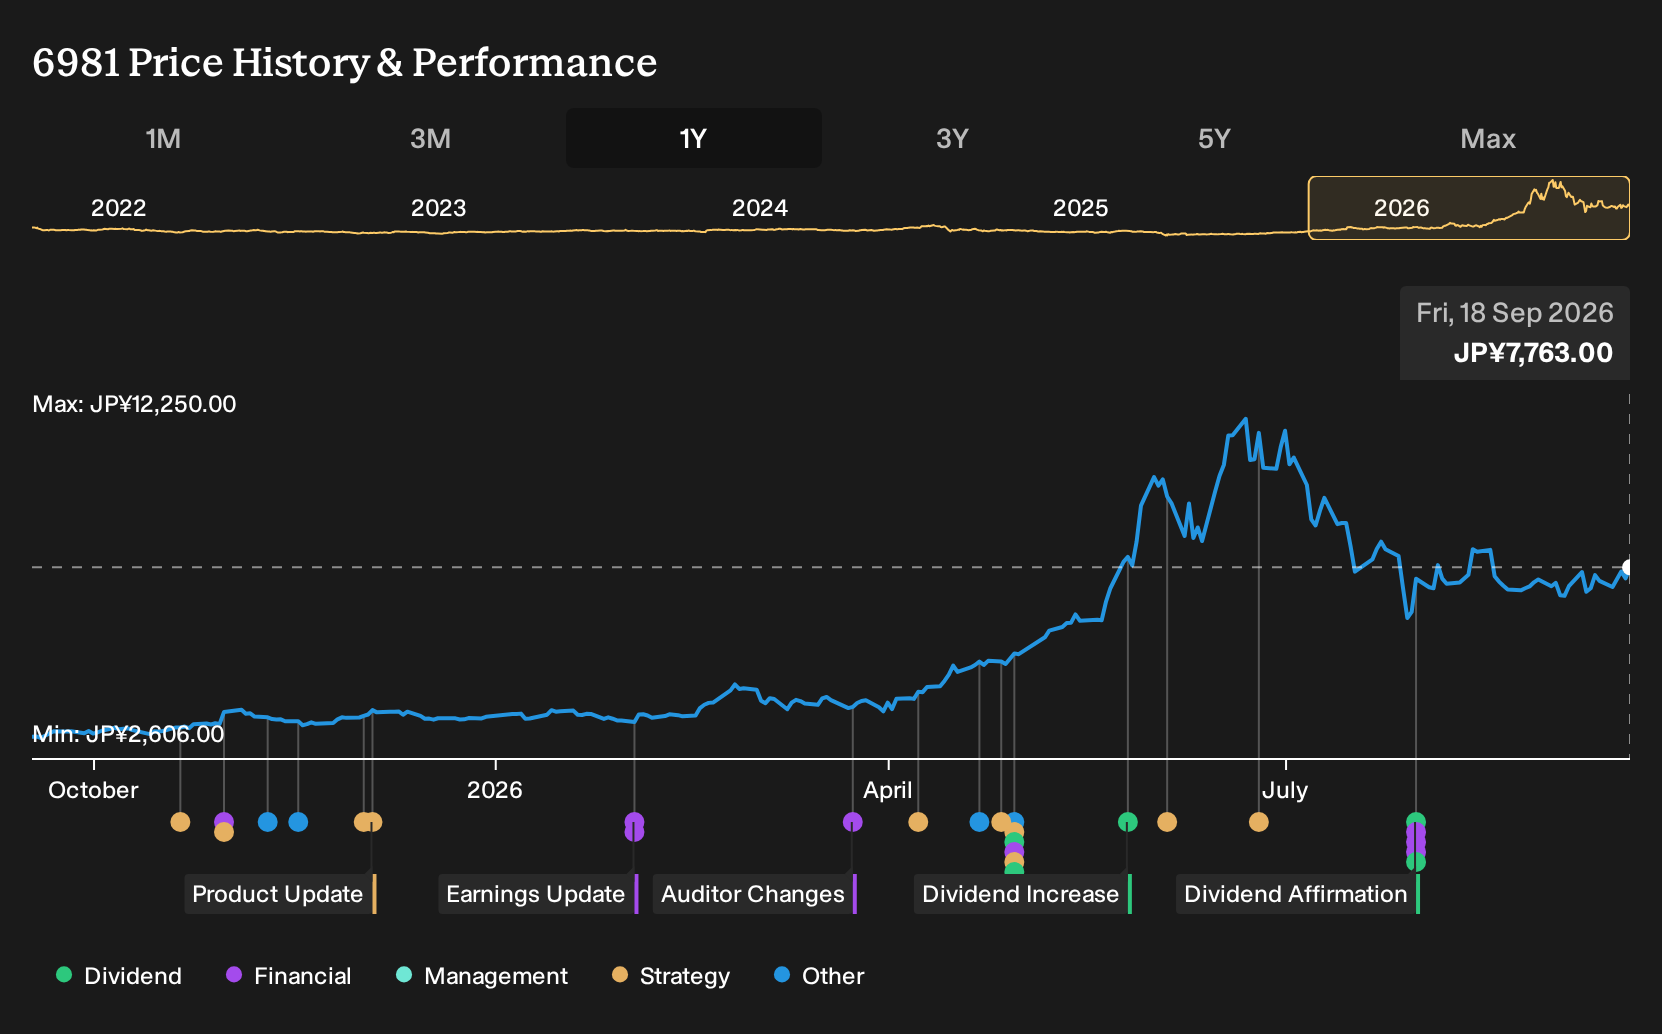
In the short term, the bigger swing factors still look like execution on core Components and Devices & Modules, pricing in consumer and communications end markets, and how investors treat a stock on a 53.2x P/E despite screens flagging it as trading below some fair value estimates. The CIPRA.ai project could broaden the wellness revenue base if it scales, although that is likely to be gradual. Volatile trading over the past three months shows sentiment can shift quickly if earnings, cash flow or capex trends disappoint.
That said, the more interesting tension for Murata Manufacturing sits in how this higher multiple, fast forecast earnings story collides with ...
There's only one way to know the right time to buy, sell or hold Murata Manufacturing. Head to Simply Wall St's company report for the latest analysis of Murata Manufacturing's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community has only two fair value estimates for Murata Manufacturing, spanning roughly ¥10,055 to ¥11,556 per share, so each view carries weight. Those opinions pre date the CIPRA.ai collaboration, which could alter revenue mix expectations. You see in real time how fast investor narratives can diverge, so exploring several viewpoints matters.
Explore another Murata Manufacturing fair value estimate, including one that suggests it could be worth just ¥10056!
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Murata Manufacturing research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Murata Manufacturing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to review Murata Manufacturing's overall financial health at a glance.
Looking For More Investment Ideas Beyond Murata Manufacturing?
If the Murata Manufacturing story has you thinking about portfolio fit, it can help to line it up against other companies with clear financial strengths or different risk profiles using the Simply Wall St Screener.
- For investors who want income with resilience, check out a set of companies offering 14 dividend fortresses that aim to combine high yield with stability.
- If capital preservation is front of mind, compare Murata Manufacturing with a 21 resilient stocks with low risk scores to see which businesses have historically steadier risk scores.
- When you are hunting for quality that is not widely followed, scan our 75 high quality undiscovered gems and see which under-the-radar stocks meet your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com