
Could Wipro STO360 Launch Deepen The SAP Stock Platform Story
- Wipro announced the launch of Wipro STO360, an SAP Endorsed App built on SAP Business Technology Platform with Aramco, aimed at modernizing Shutdown, Turnaround and Outage management for asset-intensive sectors and now listed on the SAP Store.
- The STO360 launch highlights SAP’s push to embed its cloud platform more deeply into heavy industry operations, turning complex maintenance programs into recurring, data-rich workflows that can reinforce demand for SAP Business Technology Platform services.
- We will look at how SAP's broader investment narrative around cloud platforms and recurring revenue is shaped by the Wipro STO360 launch.
SAP Investment Narrative Recap
To own SAP, you need to believe its shift toward cloud, Business AI and SAP Business Technology Platform can keep pulling more workflows and partners into its orbit. The biggest near term swing factor is execution on cloud migrations like S/4HANA and RISE with SAP while keeping implementation complexity and customer friction manageable.
The sharpest risk remains long sales cycles and regulatory demands that can inflate costs and slow bookings, especially in regions with strict data rules. The Wipro STO360 launch looks additive to the SAP BTP story but not a material catalyst on its own for near term financials.
The Trifork Group AG reseller agreement around SAP Customer Experience is the announcement that most closely aligns with the STO360 story. Both point to partners putting SAP platforms at the center of real world business processes. For you as a shareholder, that matters because it tests whether SAP can turn product breadth into deeper, recurring usage.
Customer Experience tied to SAP Sales Cloud v2 and the Retail Innovation Lab with N4XT both touch the same catalyst. The key question is whether SAP can keep embedding AI, data and process automation into front line operations in a way that keeps customers inside its ecosystem and less tempted by best of breed rivals. Execution in this area either supports the cloud and Business AI thesis or amplifies the competitive risk.
SAP Growth Assumptions Behind STO360
SAP's narrative projects €53.0 billion revenue and €11.2 billion earnings by 2029. This setup assumes 11.5% yearly revenue growth and an earnings increase of about €3.4 billion from €7.8 billion today.
Uncover why SAP's fair value indicates an 11% potential upside to its current price that could narrow quickly.
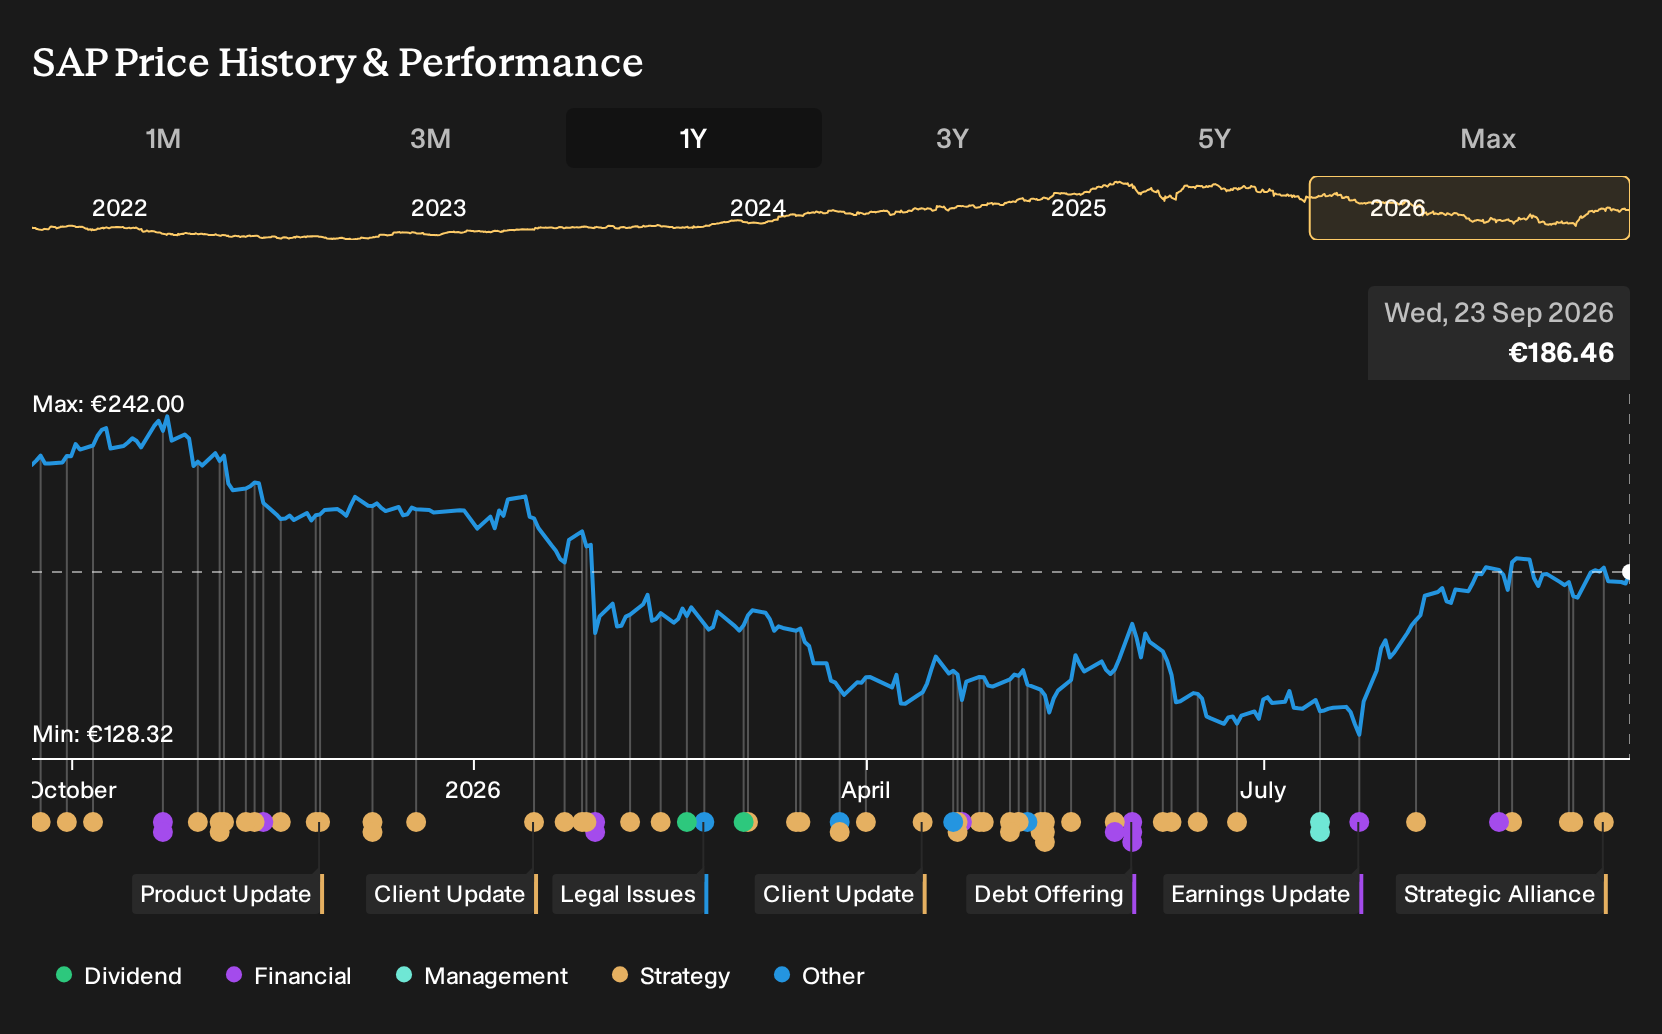
Exploring Other Perspectives
Some of the most optimistic analysts frame the key catalyst very differently. They see SAP’s cloud and AI push, now echoed by STO360 on SAP BTP, as fuel for faster expansion. Their models already penciled in €56.2b revenue and €12.5b earnings by 2029. You can treat those pre-STO360 forecasts as one possible and more aggressive scenario and compare them with your own view.
Explore 14 other SAP fair value estimates, including one that suggests an upside potential of as much as 62% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your SAP research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for SAP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to review SAP's overall financial position at a glance.
Looking For More Investment Ideas Beyond SAP?
If the SAP story has sharpened your view on platforms, risk and recurring cash flows, it can help to compare it with a wider set of businesses that share some of those traits. The Simply Wall St Screener lets you quickly filter for different qualities and then zoom into the detail when something fits your playbook.
- If you prefer steadier profiles that aim to limit downside risk while still offering equity upside potential, you might want to review our 230 resilient stocks with low risk scores that fit tighter risk criteria.
- If value is your first filter and you want businesses with stronger fundamentals than their prices suggest, start with this 173 high quality undervalued stocks that already clear quality and valuation checks.
- Income focused investors who want yield backed by underlying strength rather than stretch can scan this 161 dividend fortresses that meet a 5%+ payout hurdle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com