
Paychex (PAYX) Stock Price Reset Raises Questions After Margin Strength
Paychex holders just watched nearly 9% of the market value evaporate in a single session. That is a sharp reset for a payroll and human capital management stock that came into the print already down over the past month.
The clash is this: traders punished the shares while the company posted a Q1 headline of 6% revenue growth and roughly 14% earnings per share growth to about US$1.21. A higher margin profile and steady earnings trajectory met a price chart that traded as if there were a profit scare.
Love the higher margins and earnings progress at Paychex, but uneasy about the sharp share price reaction. Take a look at our 31 resilient stocks with low risk scores for a starting list of companies where recent price swings have been milder relative to their fundamentals.
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs. Q1 2026): US$1,630.5 million vs. US$1,540.0 million (up about 6%)
- Net Income, Excl. Extra Items (Q1 2027 vs. Q1 2026): US$429.7 million vs. US$383.8 million (up about 12%)
- Basic EPS (Q1 2027 vs. Q1 2026): US$1.21 vs. US$1.07 (up about 13%)
- Net Income Margin, Excl. Extra Items (Q1 2027 vs. Q1 2026): 26.4% vs. 24.9% (expansion of about 1.5 percentage points)
Prefer clean charts instead of another wall of earnings tables and margin figures? See Paychex’s full financial picture with a simple visual view of its valuation through our company report for Paychex.
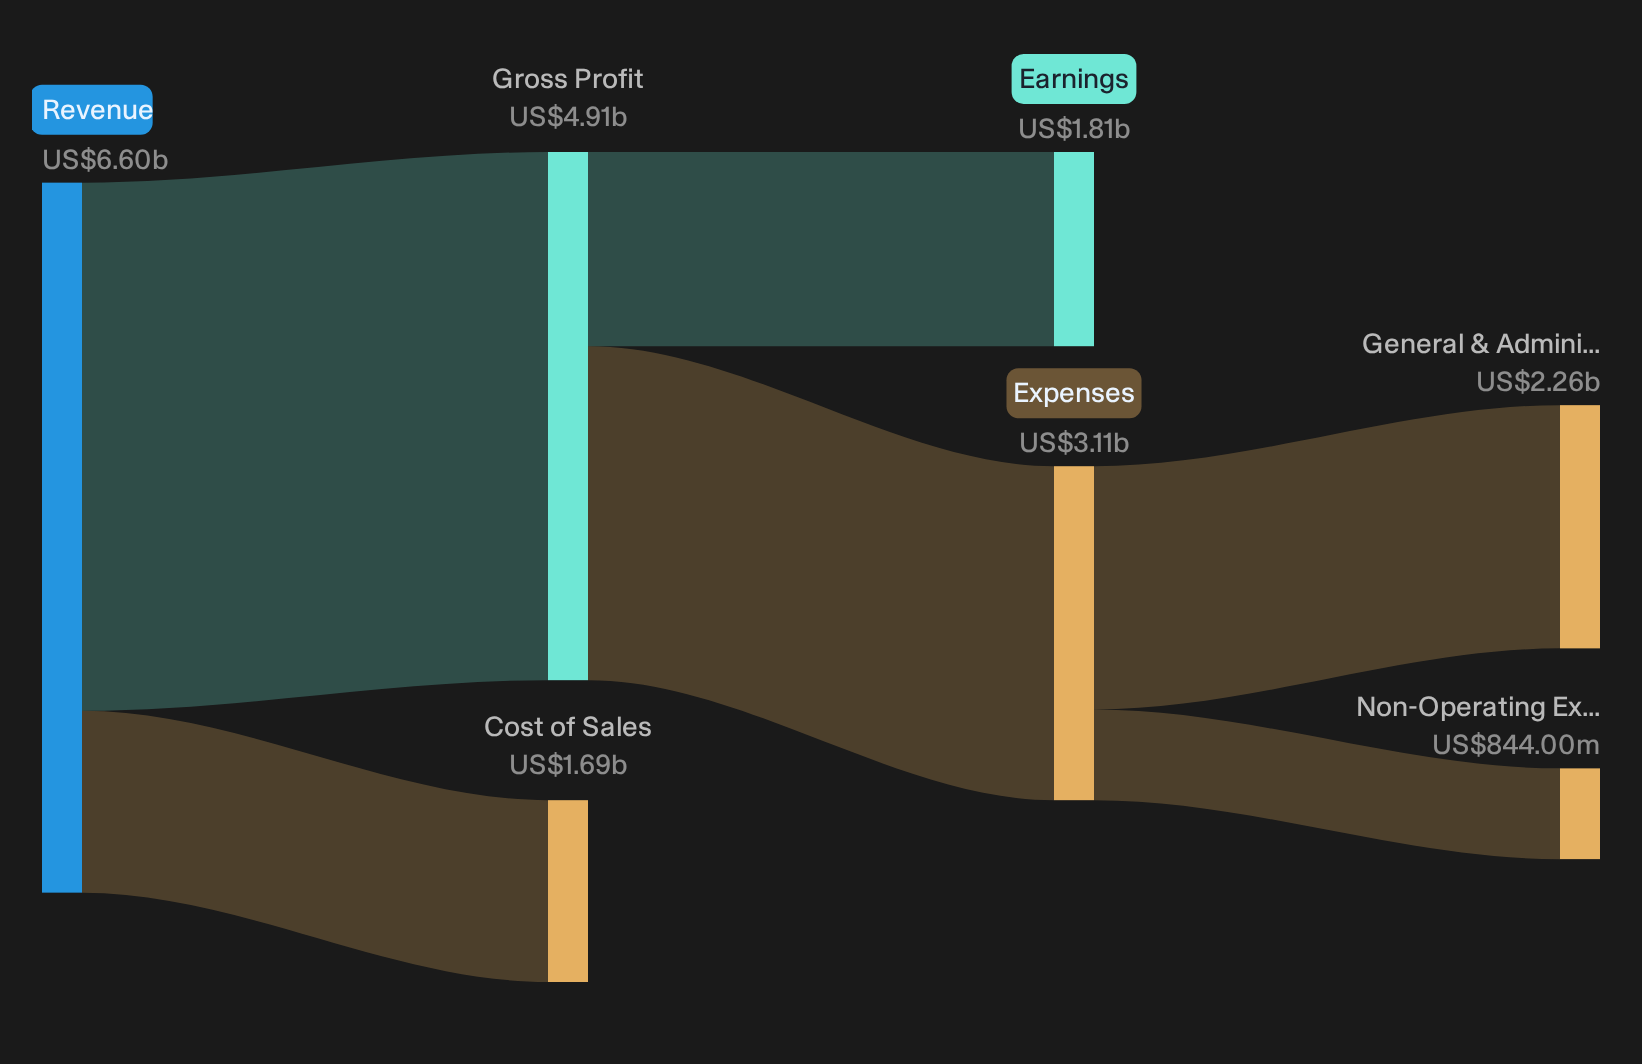
Paychex Bull Story Meets Real Operating Milestones
Supporters of Paychex argue that AI, deeper HCM penetration and the Paycor deal can lift margins and wallet share without relying on a hot economy. Q1 does supply concrete checkpoints. Adjusted operating margin moved to about 42%, while expenses rose only 1% on 6% revenue growth. That points to early productivity gains consistent with the AI and efficiency narrative.
The bullish pitch around PEO and benefits expansion also gets some backing. PEO & Insurance Solutions advanced 12% with what management describes as industry leading worksite employee growth and record retention, which lines up with the idea of higher lifetime value clients and stronger cross sell. Enterprise bookings rising at a double digit rate, plus a roughly 43% jump in broker referrals, shows the broader HCM and Paycor ecosystem is at least starting to convert into larger deals, not just headlines.
Compare Paychex’s internal progress with external expectations and see whether analysts think this margin story deserves a higher or lower bar by reviewing the consensus price target analysis for Paychex.Evaluating Paychex Bears: Growth Pacing Concerns Resurface
Bears argue Paychex is too dependent on a clean FY27 revenue glidepath, with slower conversion from bookings to reported sales and mixed execution on new initiatives. Q1 does not fully clear that hurdle. Management Solutions revenue grew about 4.3%, which management concedes was below its own internal expectations. That shortfall came even as enterprise bookings and broker referrals climbed at a double digit and roughly 43% pace. The gap between robust selling activity and mid single digit reported growth keeps the timing risk around Paycor and larger enterprise deals very much alive.
Margin bears get less validation. Total expenses rose about 1% on 6% revenue growth, adjusted operating margin reached roughly 42%, and guidance for full year margins held. The immediate pressure point is not profitability. It is whether this early AI and PEO momentum can translate into the higher FY27 top line the bearish narrative questions.
After a 9% single day share price drop and questions about how quickly Paychex can turn bookings into reported revenue, investors may want to review whether this is a one quarter timing issue or a sign of deeper pressure on the model. Expose potential structural weak spots, from execution risk to balance sheet stress, by reading the full risk analysis for Paychex which shows 1 important warning sign.Take Control Of Your Next Move
If the sharp single day drop in Paychex after solid Q1 margins has your attention, register for free with Simply Wall St and add it to a Watchlist so you can track price against fair value and watch how sentiment settles before deciding on an entry point. After you commit capital, keep a clear view of what matters by managing your holdings through the Portfolio Command Center, which cuts through noise and focuses on material developments. For longer term context, weigh your own thesis against thousands of investor views inside the Community and see how others are interpreting the same numbers. Spot potential catalysts and pressure points early, stay informed on Paychex, and give yourself a better chance of reacting before the broader market does.
Seeking Fresh Alternatives Beyond Paychex?
Some stocks are building quiet breakout momentum, while others are already moving higher and risk getting caught by the crowd. Scan fresh ideas that are still under the radar and consider your options.
- Spot income workhorses with staying power by reviewing a curated pool of resilient high yield payers through the 7 dividend fortresses.
- Explore early upside where profitability already backs the story by scanning hand picked AI operators via the 38 profitable AI stocks that aren't just burning cash.
- Focus on financially disciplined companies involved in infrastructure and electrification trends by reviewing the carefully filtered 39 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com