
Venture Global (VG) Stock Looks Reasonable Even After Its 88% Run
Venture Global has delivered a sharp share price swing this year, and the scale of that move puts a spotlight on whether its current earnings can support where the stock now trades. With recent headlines around potential long term LNG supply deals, the question becomes how much of those expectations are already reflected in the valuation.
- The stock is up 88.5% year to date, which puts recent earnings power under the microscope for anyone trying to understand what is already priced in.
- Reports that Qatar Energy is in talks with Venture Global for multi year LNG contracts may support expectations for steadier future cash generation, which matters directly for how investors frame its earnings base today.
- There is a second opinion on Venture Global worth weighing. See what analysts think Venture Global's shares could be worth.
The stock's next move may depend on whether Venture Global's current share price is aligned with what its earnings suggest is reasonable.
If you want to stress test the same earnings question that hangs over Venture Global against a wider set of LNG and energy related companies, start with 39 power grid technology and infrastructure stocks
Does Venture Global Look Undervalued on Earnings?
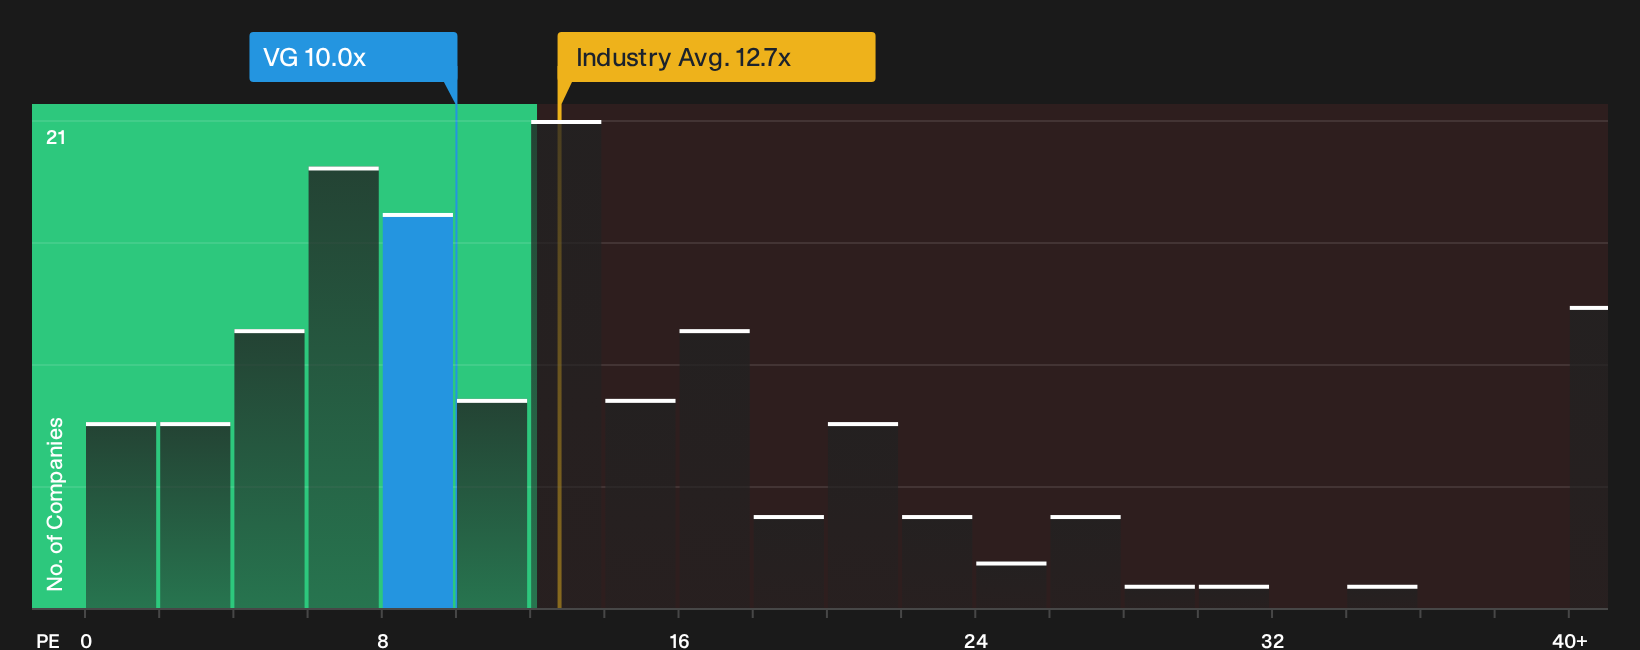
A P/E lens suits Venture Global because earnings are the main anchor for how investors value established LNG producers. The stock trades on a P/E of about 10.0x, which is below both the Oil and Gas industry average of roughly 12.7x and a wider peer group closer to 26.8x. This means the market is assigning a thinner earnings premium than many similar businesses.
Because the Fair Ratio already adjusts for Venture Global’s sector, risk profile and earnings quality, the current P/E sitting below that benchmark points to the shares screening undervalued on this metric. Reports that Qatar Energy is in talks with Venture Global for multi year LNG supply deals have lifted interest in the story. However, the multiple still prices the stock at a discount to many peers on reported earnings. Explore the numbers behind Venture Global's P/E valuation.
The Venture Global Narrative: What Would Justify Today's Price?
Venture Global's recent re-rating leaves a clear puzzle, and Simply Wall St Narratives are designed to explain which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today's price on the Community page. Each scenario links a fair value estimate to a specific mix of potential catalysts and key risks, allowing you to track over time which version of Venture Global's story is actually unfolding.
One of the top community narratives on Venture Global: 5% undervalued
"This narrative explores a more pessimistic perspective on Venture Global compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts..."
Discover why this Narrative puts Venture Global at 5% undervalued.
The Venture Global share price is only one piece of the decision
Valuation work tells you what the current numbers imply, but Venture Global also carries specific risk flags from our checks that investors may want to weigh before committing fresh capital. Take a closer look at 3 warning signs (3 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com