
Rusta (OM:RUSTA) Is Back In Focus, What Are Investors Watching?
Rusta (OM:RUSTA) has put income and governance in focus after shareholders approved a cash dividend of SEK 1.80 per share and elected Mats Rignell to the board at the 2026 AGM.
Rusta’s share price has eased in the short term, with a 30-day share price return down 6.88% and year-to-date share price performance down 9.92% at SEK 75.8. However, the 1-year total shareholder return of 24.87% points to momentum that has built over a longer stretch, helped by stronger first quarter results and the newly approved dividend.
See how Rusta compares with other retailers showing resilient earnings and shareholder payouts using our curated list of 173 high quality undervalued stocks.
Rusta has given shareholders a mix of softer recent returns and stronger reported results, along with a new dividend. The key question now is simple: is most of the upside already in the rear-view mirror, or is there still more to come from here?
Most Popular Narrative: 15% Undervalued
Against Rusta's last close of SEK 75.8, the most followed narrative points to a fair value of SEK 89.33, which frames the recent dividend and earnings strength in a context of potential upside that is not fully reflected in the current share price.
Expansion plans for opening 50 to 80 new stores over the next 3 years, including in Germany, where market conditions are becoming more favorable. This will likely drive revenue growth as the company enters new markets and increases store presence.
See why 6 investors see Rusta as 15% undervalued.
Result: Fair Value of SEK 89.33 (UNDERVALUED)
Still, currency swings and tougher conditions in Germany and Finland could pressure margins and delay the expansion story that underpins the current Rusta narrative.
Find out about the key risks to this Rusta narrative.
Another View On Rusta’s Valuation
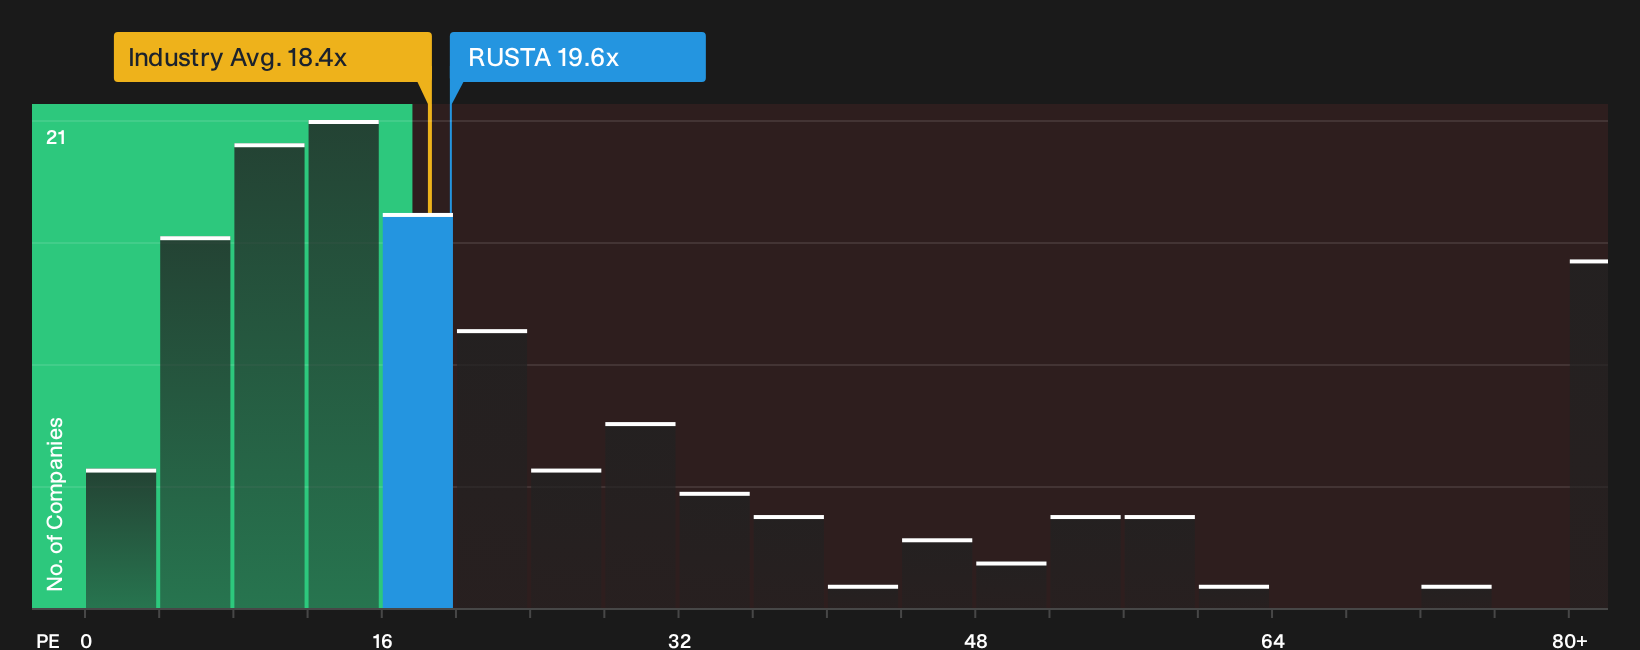
The earlier narrative leans on growth forecasts and a fair value of SEK 89.33, yet the current P/E of 19.6x tells a slightly different story. That multiple sits above the peer average of 18.5x and above the fair ratio of 19.2x, which points to a modest valuation premium rather than a clear markdown. So is Rusta priced for more than it is currently delivering, or is the extra multiple simply the cost of a quality track record and expansion plan?
For a closer look at how this price compares against earnings and peers in detail, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Rusta is mixed, which is exactly when your own homework matters most. Move quickly, review the full picture and weigh the upside by checking 3 key rewards.
Looking for more investment ideas beyond Rusta?
If Rusta has your attention, do not stop here. Broaden your watchlist with a few focused stock ideas that match different goals on your radar.
- Target steady cash returns by reviewing companies that feature 161 dividend fortresses and see which payouts look built to last.
- Strengthen downside protection by scanning a 230 resilient stocks with low risk scores that highlights businesses with more resilient profiles and lower overall risk scores.
- Get ahead of the crowd by checking a 619 high quality undiscovered gems that surfaces under-the-radar stocks with stronger fundamentals than their profiles suggest.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com