
Hess Midstream (HESM) Has Investors Looking Closer, But What Is Behind It?
Hess Midstream (HESM) just cleared a fresh second quarter earnings hurdle, topping expectations as higher tariffs and lower costs offset weaker throughput and reshaped the cash flow picture for the rest of 2026.
The latest move in Hess Midstream’s story is happening against a backdrop where the share price has eased over 1-day and 7-day periods, yet still holds an 11.92% year-to-date share price return and a 19.71% total shareholder return over 1 year. Longer multiyear total shareholder returns above 65% suggest momentum that has built over time rather than faded on short-term earnings noise.
Scan other fee-based operators with similar cash flow traits by reviewing our curated list of 31 resilient stocks with low risk scores that might echo parts of the Hess Midstream story.
Hess Midstream now trades just above the average analyst target while carrying a much deeper intrinsic value estimate, so where does a reasonable fair value range actually land once those gaps are lined up side by side?
Most Popular Narrative: 3% Overvalued
Hess Midstream closed at $38.78 against a most-followed fair value estimate of $37.50. This has the units trading slightly above that modeled range while still anchored on free cash flow strength rather than aggressive growth assumptions.
Hess Midstream is moving into a capital lighter phase as total capital expenditures are expected to fall from about US$270 million in 2025 to approximately US$150 million in 2026 and then to less than US$75 million per year in 2027 and 2028. This supports higher adjusted free cash flow and potentially stronger free cash flow based valuation multiples.
See why 36 investors see Hess Midstream as 3% overvalued.
Result: Fair Value of $37.50 (OVERVALUED)
Still, the Hess Midstream story can break if Chevron pulls back on its Bakken plan or if minimum volume coverage erodes faster than expected.
Find out about the key risks to this Hess Midstream narrative.
Another View on Hess Midstream’s Value
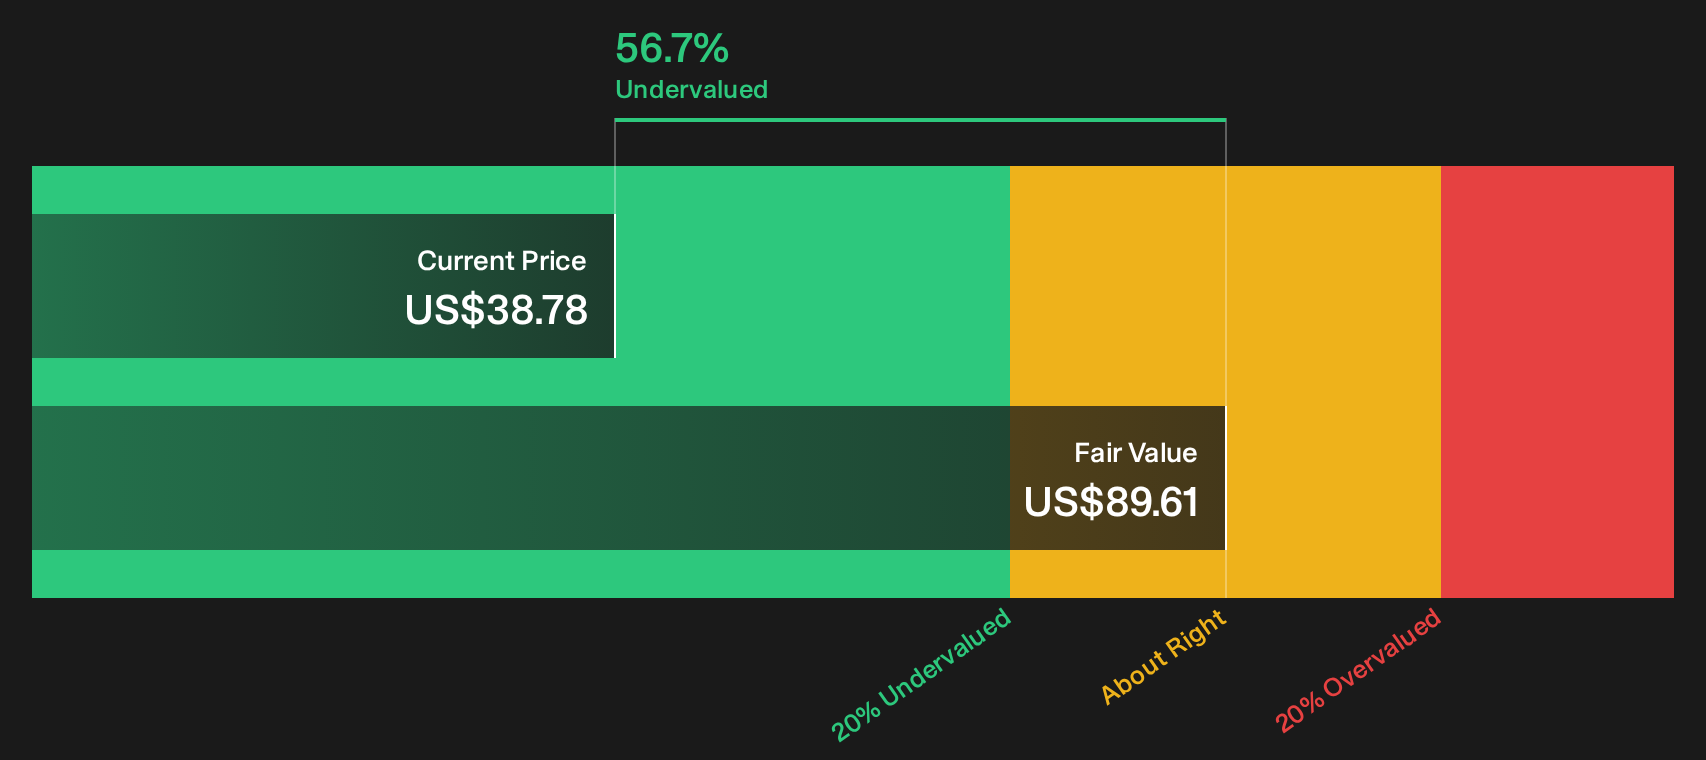
The 3% overvalued narrative hinges on a $37.50 fair value, yet our DCF assessment presents a different picture. On that model, Hess Midstream at $38.78 trades well below an estimated future cash flow value of $89.61, which points to a wide valuation gap instead of a small premium.
The SWS DCF model relies on projected cash generation rather than earnings multiples, so it is most sensitive to changes in free cash flow assumptions and discount rates rather than short term sentiment. When one framework flags modest overvaluation and another suggests substantial undervaluation, which set of assumptions do you consider more useful for your own analysis?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hess Midstream for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hess Midstream’s value story can be useful if you pressure test them against the raw numbers yourself. To see how the trade off between upside potential and downside risk stacks up in one place, review the 3 key rewards and 2 important warning signs.
Looking for more Hess Midstream style ideas?
If Hess Midstream has sharpened your focus on quality and cash flow, do not stop here. Use the Simply Wall St screener to spot other opportunities before they move.
- Target steady payers and recurring income streams by reviewing a focused set of 7 dividend fortresses designed for investors who care about consistent cash returns.
- Hunt for potential mispriced opportunities by scanning through a curated group of 16 high quality undiscovered gems that many investors may not be watching yet.
- Aim for resilience first by filtering companies with strong finances using the list of solid balance sheet and fundamentals (23 results) so you can concentrate on businesses built to endure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com