
Resource Expansion Could Change The Case For Coeur Mining Stock
- Coeur Mining reported an exploration update for its New Afton and Rainy River mines in Canada, including a record planned US$158 million exploration spend in 2026 and detailed drilling results that expand mineralized zones and support ongoing resource definition work.
- The focus on infill and expansion drilling at K-Zone, East Picrite and key Rainy River underground zones shows how Coeur Mining is concentrating capital on assets where drilling has already outlined sizeable mineralized systems with potential for further resource conversion.
- We will now look at how Coeur Mining's record 2026 exploration budget could influence the investment narrative around its Canadian assets.
Coeur Mining Investment Narrative Recap
To own Coeur Mining, you need to believe that heavy upfront exploration and development spending today can support a longer operating profile across its gold and silver portfolio. The record US$158 million exploration plan for 2026 fits that playbook. The key near term swing factor remains execution at existing mines, where cash generation needs to keep pace with that higher spend.
The biggest immediate risk is that high capital intensity and any permitting or geological setbacks drag on cash flow or push out timelines for converting resources into mine plans. This exploration update looks supportive rather than transformational. It strengthens the story around future optionality but does not remove financing, regulatory or reserve replacement risks.
The recent confirmation that Coeur Mining’s CEO will present at Mining Forum Americas ties into this exploration update in a practical way. Management now has fresh drill data and a record exploration budget to discuss with institutional investors. That gives the presentation clear operational content, including topics such as K Zone growth and Rainy River underground extensions.
For catalysts, execution around these Canadian programs, combined with any commentary at the conference on capital allocation, will be important. Investors will likely watch for how the company balances exploration outlays against its history of shareholder dilution, and how quickly results at New Afton and Rainy River might translate into mine life extensions or updated technical studies.
How Consensus Forecasts Frame Coeur Mining’s Canadian Spending
Coeur Mining's exploration push in Canada now sits alongside a fairly aggressive analyst playbook for the wider group. The consensus view ties that drilling work into a bigger story of ramped up production, expanding margins and higher earnings over the next several years.
On the top line, analysts are building their models around revenue growing by 27.8% each year over the next three years. Profitability assumptions are even more ambitious. Forecasts point to profit margins moving from 26.8% today to 44.0% in three years, which implies a much richer earnings profile if operations and costs track to plan.
Earnings expectations are a key part of that narrative. Consensus numbers call for earnings to reach US$2.9b by 2029, compared with US$850.4m today. That is an earnings increase of about US$2.0b, which is what underpins many of the long term valuation anchors currently in use for the stock.
Those same models assume Coeur Mining trades on a P/E of 13.0x on the 2029 earnings figure. That compares with 25.9x today and sits below the current P/E for the wider US metals and mining peer group at 21.4x. The gap suggests analysts see room for earnings growth to do more of the heavy lifting than multiple expansion.
Consensus valuation work also rests on revenue forecasts. To line up with analyst targets, you would be working off a 2029 revenue figure of about US$6.6b and the US$2.9b earnings estimate, both discounted back using an 8.8% rate or something similar. That framework links the exploration budget and operating execution to a specific financial destination rather than just a broad growth story.
The equity side of the equation carries its own moving parts. Forecasters expect the share count to rise by about 7.0% per year over the next three years. That means any upside from exploration success and higher production needs to be considered on a per share basis, not just in absolute profit dollars.
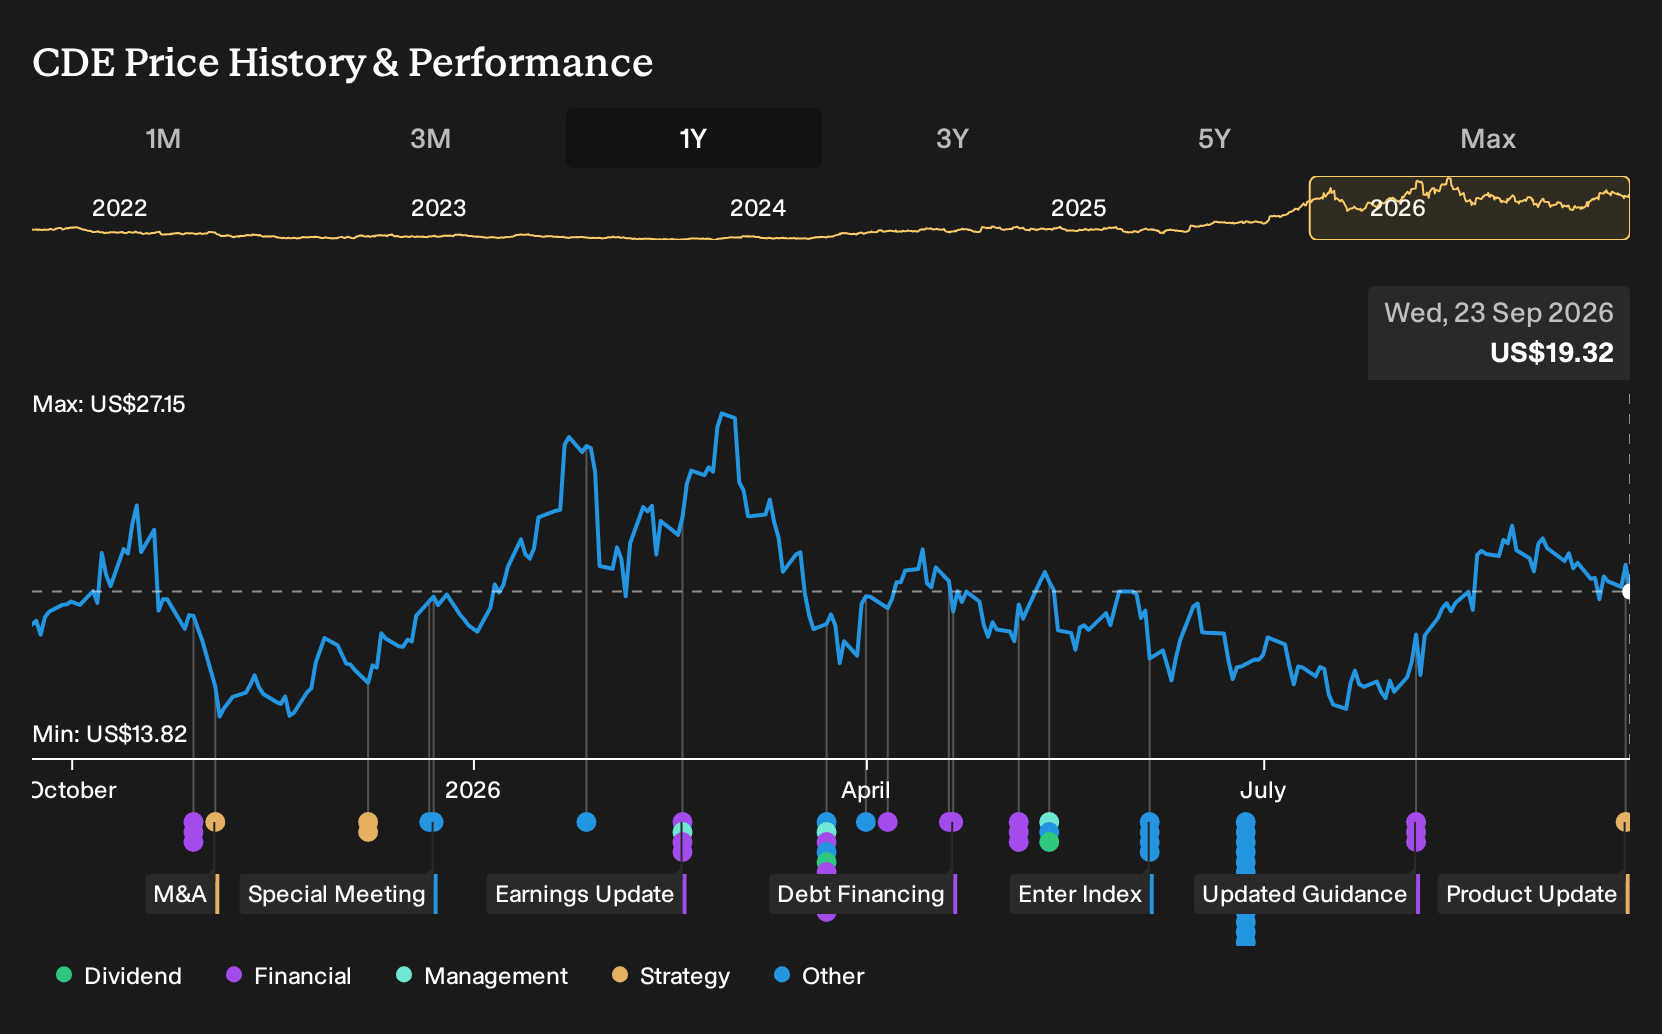
For now, the market price and the analyst spreadsheet sit relatively close together. With the stock at US$21.42 and the consensus target at US$23.32, the implied upside of 8.1% is modest. The spread suggests analysts, on average, see Coeur Mining as roughly in line with their fair value work given the current information.
Underlying all of this is a set of assumptions about what increased exploration in places like New Afton and Rainy River can contribute to the long range revenue and earnings profile. If drill results and mine plans eventually support those 2029 numbers, the heavy investment in 2026 will look like a calculated attempt to feed into that trajectory. If outcomes diverge, either through cost pressure, permitting delays or resource disappointment, the consensus path to US$6.6b of revenue and US$2.9b of earnings may need to be revisited.
Coeur Mining's narrative projects US$6.6b revenue and US$2.9b earnings by 2029. This requires 27.8% yearly revenue growth and an earnings increase of about US$2.0b from US$850.4m today.
Uncover how Coeur Mining's fair value indicates a 21% potential upside to its current price before that valuation gap starts to close.
Exploring Other Perspectives
One alternate view focuses on Rochester ramp up risk rather than exploration upside. The most cautious analysts were only penciling in about US$5.4b of 2029 revenue and US$1.9b of earnings before this Coeur Mining drill update. That is well below consensus and shows how sharply opinions can differ, so it helps to compare several viewpoints before considering what this new information might change.
Explore 5 other Coeur Mining fair value estimates, including one that suggests there may be as much as 7% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own research and judgment.
- A great starting point for your Coeur Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Coeur Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coeur Mining's overall financial health at a glance.
Looking for more Coeur Mining style investment ideas?
If the Coeur Mining story has you thinking about where else strong fundamentals and clear narratives might exist, it can help to cast a wider net using the Simply Wall St Screener. You can filter for balance sheet strength, income potential, or under the radar quality to build a watchlist that fits how you like to invest.
- For sturdier portfolios, start with businesses that prioritize financial resilience and funding flexibility by scanning our list of solid balance sheet and fundamentals (23 results).
- If you want potential value opportunities with quality characteristics, look through the 30 high quality undervalued stocks that already combine cash generation with sound fundamentals.
- For investors who prefer to keep risk in check, consider companies with steadier profiles by reviewing the 31 resilient stocks with low risk scores and see which ones merit a closer look for your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com