
Silvercorp Metals (TSX:SVM) Buyback Puts Valuation Back In Focus
Silvercorp Metals (TSX:SVM) has put shareholder returns in focus after its board approved a new normal course issuer bid to cancel up to 8,848,585 shares, equal to roughly 4% of its share count.
Recent trading has been choppy for Silvercorp Metals, with the share price falling 6.45% on the day to CA$16.24, even though the 7 day share price return is up 4.04% and the 90 day share price return is up 7.84%.
Set against that short term volatility, the 1 year total shareholder return of 99.08% and 3 year total shareholder return of about 4x suggest that momentum has been building over a longer horizon, as investors respond to buyback activity and governance changes around the postponed shareholder meeting.
Scan other precious metals producers showing similar momentum and capital return stories with the curated 10 top silver producer stocks
Silvercorp Metals has rallied hard while still trading about 30% below the average analyst price target, which is a wide gap. Does fair value lean closer to today’s CA$16.24 or the CA$21.08 consensus?
Price-to-Earnings of 81.4x: Is it justified?
Silvercorp Metals trades on a rich P/E multiple, with the market paying 81.4x current earnings at a last close of CA$16.24 while analyst targets still sit higher at CA$21.08. For investors weighing that near 30% discount to consensus, the question is whether this earnings multiple lines up with the story on profits and cash flows.
The P/E ratio compares the share price to earnings per share and is a common yardstick for miners where profits can swing with commodity prices. A higher P/E often reflects expectations for stronger future earnings, but it can also signal that current profits are temporarily low.
In Silvercorp Metals' case, that 81.4x P/E comes with some mixed signals. Earnings are forecast to grow 89.53% per year and revenue is expected to expand 28.8% per year, both ahead of the broader Canadian market. At the same time, the SWS DCF model estimates future cash flow value at CA$6.41 per share, which is well below the current CA$16.24 price. This suggests the market is paying a heavy premium to those modelled cash flows.
Compared to the Canadian Metals and Mining industry average P/E of 16.9x, Silvercorp Metals trades on a substantially higher multiple. It is also described as expensive relative to an estimated fair P/E of 64.6x. This implies the market valuation sits well above a level the ratio could move toward if expectations cooled.
Explore the SWS fair ratio for Silvercorp Metals.
Result: Price-to-Earnings of 81.4x (OVERVALUED)
Still, Silvercorp Metals faces clear pressure points if the story cools, including any setback in forecast earnings growth or a reversal in recent shareholder returns.
Find out about the key risks to this Silvercorp Metals narrative.
Another view on Silvercorp Metals’ value
The P/E discussion paints Silvercorp Metals as expensive, yet our DCF model tells a different story. On those cash flow estimates, fair value sits at CA$6.41 per share, well below the current CA$16.24 price, which suggests a premium valuation that leans heavily on future delivery. That raises the question: Are analyst forecasts and recent momentum enough to bridge such a wide gap?
Look into how the SWS DCF model arrives at its fair value.
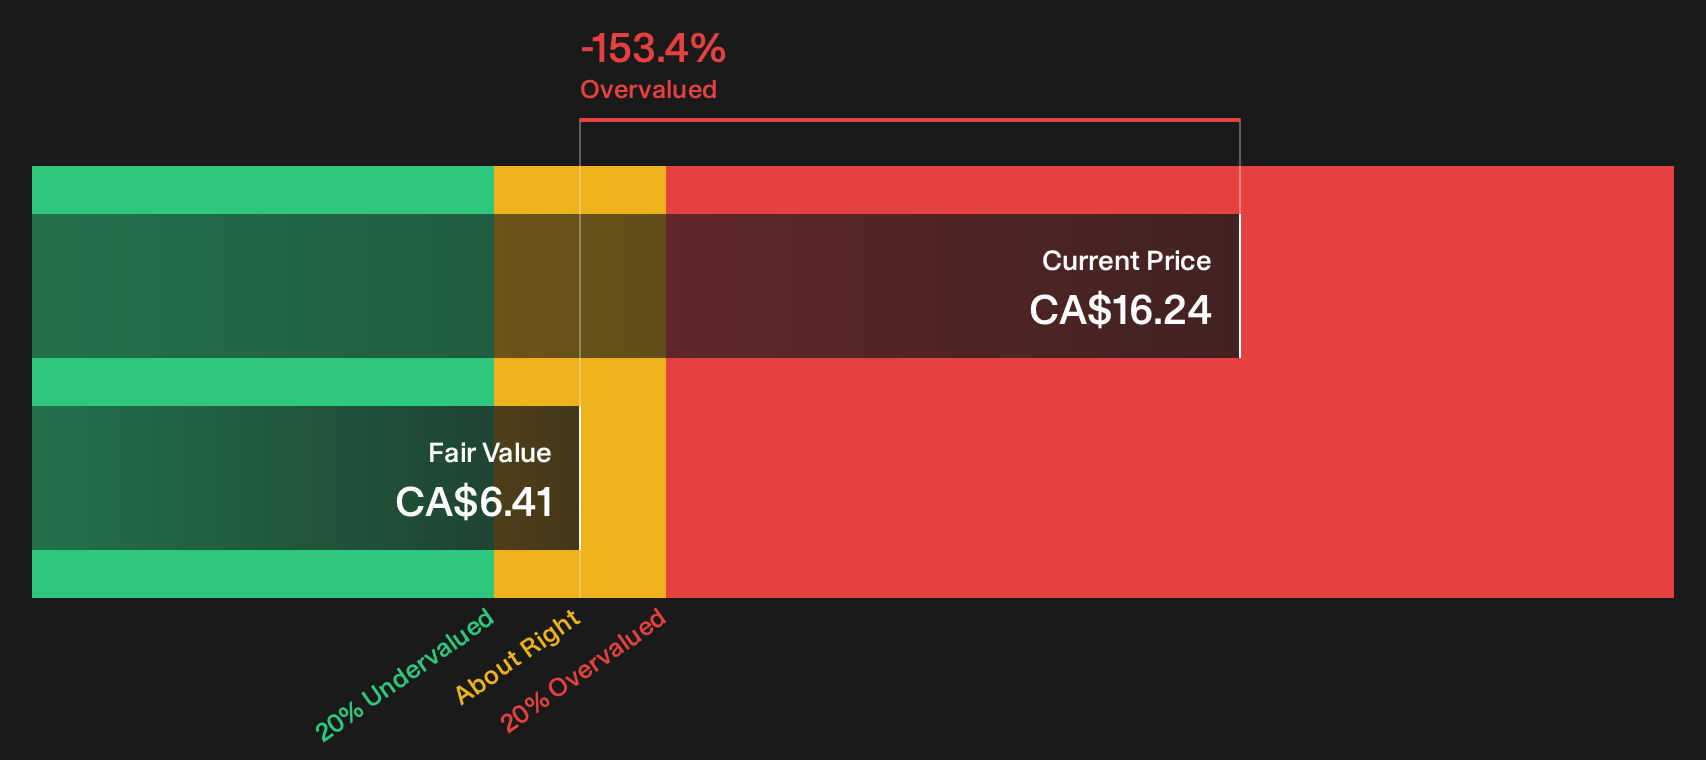
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Silvercorp Metals for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Silvercorp Metals so far. If you want to move quickly and form your own stance based on the full picture, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Silvercorp Metals?
Silvercorp Metals gives a useful reference point, but your next strong idea probably comes from widening the search and comparing a few different types of opportunities.
Use the Simply Wall St screener to quickly scan other stocks and keep your shortlist sharp before the market moves on without you.
- Target stability first and cut left-tail risk by reviewing a 8 resilient stocks with low risk scores that focuses on resilient businesses with stronger protection against shocks.
- Hunt for quality at a discount by checking the 6 high quality undervalued stocks and spotting companies where fundamentals and pricing look better aligned.
- Spot potential future leaders early by working through the 9 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com