
Should Record Oil Output Require Action From ExxonMobil (XOM) Investors?
- ExxonMobil Holdings recently reported record oil output and revenue, delivered with lower capital spending and supported by higher production from high return assets such as the Permian Basin.
- Alongside this, management raised its 2030 liquefied natural gas sales target to 50 million tons and continues to emphasize strong cash generation, dividend growth and investments in lower emission projects.
- We will now explore how ExxonMobil's record oil output from high return assets might shape the broader investment narrative that investors focus on.
Scan ExxonMobil Holdings alongside other income-focused energy players by checking our curated list of 7 dividend fortresses that link strong payouts to resilient business models.
ExxonMobil Holdings Investment Narrative Recap
To own ExxonMobil Holdings, you need to be comfortable with a long future for oil and gas alongside a measured build out of lower emission businesses. The thesis leans on high return barrels from the Permian and Guyana, ongoing cost savings and disciplined spending that supports cash generation even when pricing moves around.
The short term story still hinges on operational delivery from these flagship projects and keeping structural savings on track. Record output and revenue signal that execution is currently aligned with that view. The biggest near term risk remains policy or demand shifts that pressure hydrocarbon volumes before newer low carbon activities reach meaningful scale.
The clearest recent announcement for this story is ExxonMobil raising its 2030 liquefied natural gas sales target to 50 million tons. That goal implies a larger role for LNG in the mix, which can matter for cash flow durability if crude markets become more volatile or policy support for gas as a transition fuel holds.
This LNG focus connects directly to the current catalysts. Higher volumes from high return oil projects, cost savings nearing a US$20b target and an integrated refining and chemicals footprint already working to smooth earnings all rely on consistent execution. LNG capacity adds another operational lever, but it also brings project delivery risk and exposure to long term demand for gas.
What The Current Analyst Narrative Implies For ExxonMobil Holdings
ExxonMobil Holdings' current story in the analyst models is surprisingly simple. Modest top line growth, fatter margins and fewer shares do most of the heavy lifting in the spreadsheets.
Consensus forecasts point to revenue rising by 1.2% each year over the next three years, while net margins are assumed to move from 9.1% today to 12.2% by 2029. Analysts have earnings today at about US$32.8b and expect that figure to reach US$45.7b by 2029, which implies an increase of roughly US$12.9b in annual profit over that period.
ExxonMobil Holdings' narrative projects US$373.7b revenue and US$45.7b earnings by 2029. This rests on 1.2% yearly revenue growth and an earnings increase of about US$12.9b from US$32.8b today.
The same models assume the share count drifts down by 2.5% a year for the next three years as buybacks continue. That shrinking pool of shares is what pulls the forecast earnings per share up to US$11.67 by 2029 in the consensus case, even though the top line is growing at a low single digit pace.
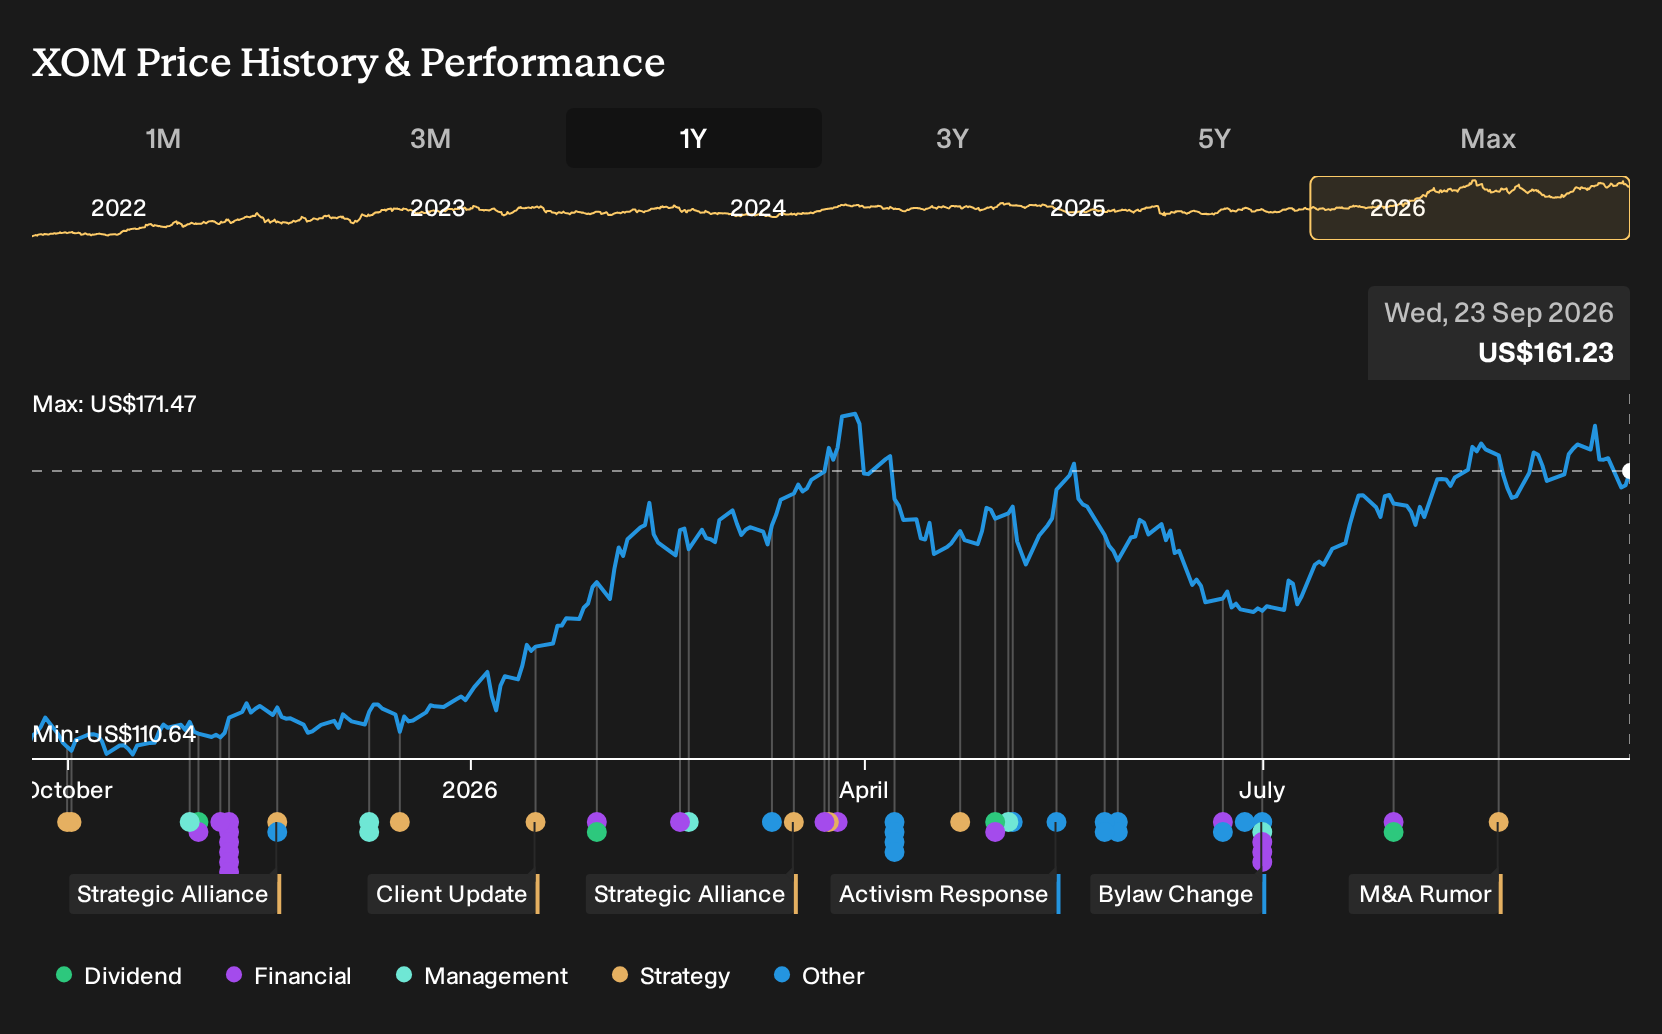
Analysts then pull all of this together into a valuation view. To line up with the current price targets, ExxonMobil Holdings would need to be earning US$45.7b on revenues of US$373.7b in 2029 and trade on a P/E of 17.6x, compared with 20.5x today and an industry level of 13.5x for US oil and gas peers. At a recent share price of US$163.54, that set of assumptions underpins a consensus target of US$170.91, only 4.3% higher.
For investors, the message is clear. The market does not appear to be baking in aggressive growth, but it is giving ExxonMobil Holdings some credit for higher profitability, steady buybacks and delivery on the record production narrative that has driven the latest results.
Uncover why ExxonMobil Holdings' fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on ExxonMobil Holdings using LNG and lower cost barrels to support much faster expansion than the base case. Before the recent record output, they were modelling revenue reaching about US$506.7b and earnings of US$55.1b by 2029. You can compare that more upbeat script with your own view, as fresh commentary from the Laguna conference and the higher LNG target filter through and potentially reset expectations.
Explore 4 other ExxonMobil Holdings fair value estimates, including one that suggests as much as 19% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ExxonMobil Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for ExxonMobil Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ExxonMobil Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond ExxonMobil Holdings?
If the ExxonMobil Holdings story has sharpened your view on income, resilience and execution risk, use that same lens across a broader watchlist. The Simply Wall St Screener can help you line up other companies against the factors that matter most to you, from balance sheet strength to dividend reliability.
- If you want resilience first and volatility second, start with a basket of businesses screened for sturdier financial foundations through our 31 resilient stocks with low risk scores.
- Income focused investors can zero in on payout strength and consistency by scanning a 7 dividend fortresses that prioritizes yield alongside staying power.
- For readers looking for potential compounders before they attract wider attention, filter the market using a 16 high quality undiscovered gems that surfaces quality fundamentals hiding in plain sight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com