
ProPetro (PUMP) Stock May Trade At A Premium On Sales
ProPetro Holding has delivered a sharp 84.2% gain over the past year, which naturally raises a question about whether the current share price lines up with the sales that support it. For an oilfield services business where revenue can swing with activity levels in the energy sector, that link between the top line and valuation matters a lot.
- The stock's 84.2% return over the last 12 months puts real pressure on the question of whether the recent share price move is still grounded in what ProPetro Holding produces in sales.
- For a contract driven services operator like ProPetro Holding, the pace and quality of revenue it can generate from its existing fleet and customer base may support or cap how far the valuation can stretch.
- The analysts covering ProPetro Holding have run their own numbers. See what analysts think ProPetro Holding's shares could be worth.
The issue now is whether ProPetro Holding's current US$9.80 share price is adequately justified by the sales it is generating today and is reasonably expected to produce.
If you want to stress test this same "is the price fair for its sales" question beyond ProPetro Holding, take a look at 30 high quality undervalued stocks
Has ProPetro Holding Run Too Far on Sales?
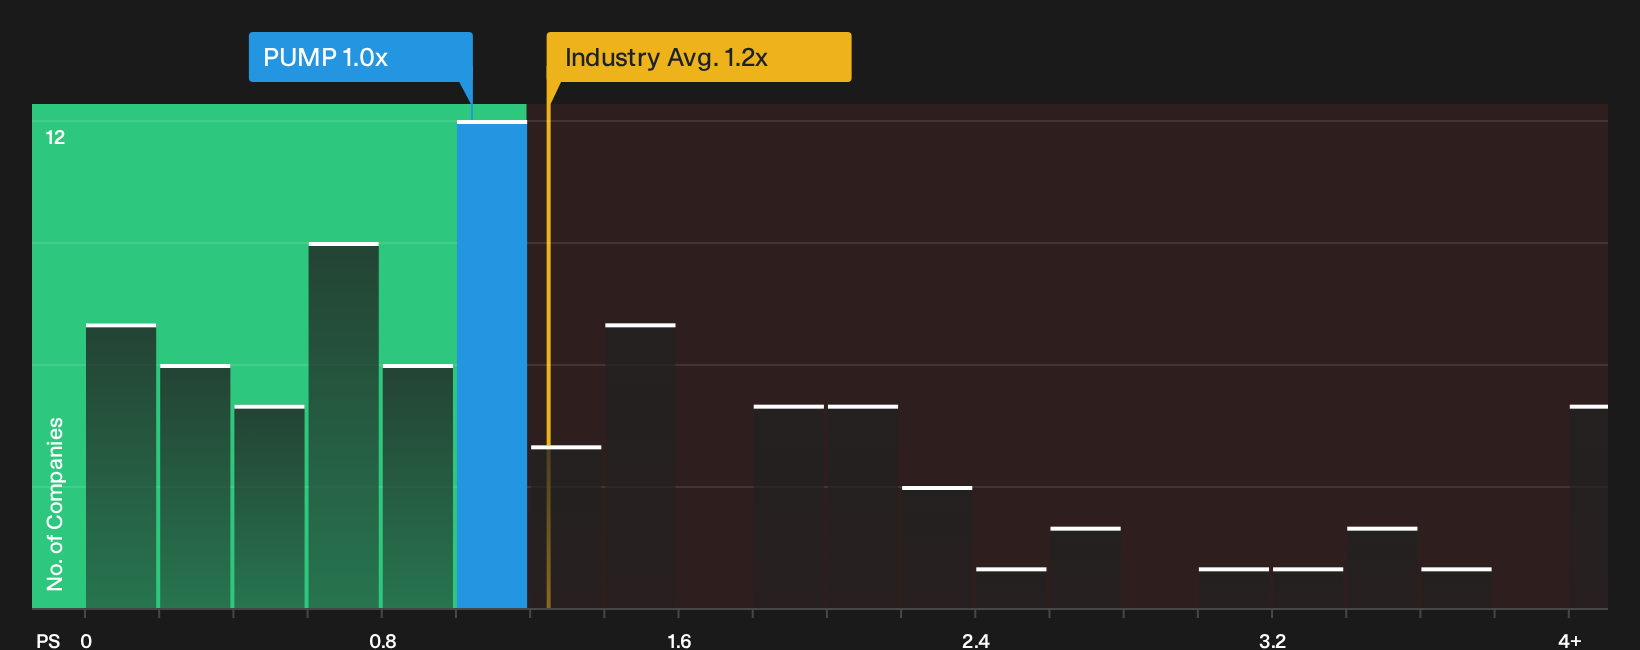
P/S is a useful lens for ProPetro Holding because investors are often paying for capacity and contract density rather than smooth profits. On this measure, the stock trades on a P/S of about 1.0x, which is above the Energy Services peer average of roughly 0.8x but below the broader industry average of around 1.2x. That mix suggests the market is pricing ProPetro somewhere between lower rated direct comparables and higher rated sector players.
The Fair Ratio model, which adjusts for the company’s own growth profile, margins, size and risk, points to a lower P/S level than the current 1.0x. On this tailored benchmark ProPetro screens as overvalued, because buyers today are paying more per dollar of revenue than the model implies is warranted once those fundamentals are taken into account. That gap is not extreme, but it does mean you need a clear view on contract quality and fleet utilization to feel comfortable with the current sales multiple. Explore the numbers behind ProPetro Holding's P/S valuation.
The ProPetro Holding Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St's Community page pick up where this valuation puzzle leaves off by explaining which paths for ProPetro Holding's growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than today. Each scenario links its figures to a specific view on how ProPetro Holding's revenue mix, profitability and risk profile could change, giving you something concrete to revisit as new information emerges.
One of the top community narratives on ProPetro Holding: 43% undervalued
"Early traction and long-term visibility in the PROPWR power business, including the recent 10-year, 80-megawatt contract, expands addressable markets..."
Discover why this Narrative puts ProPetro Holding at 43% undervalued.
One more angle on ProPetro Holding that could change the picture
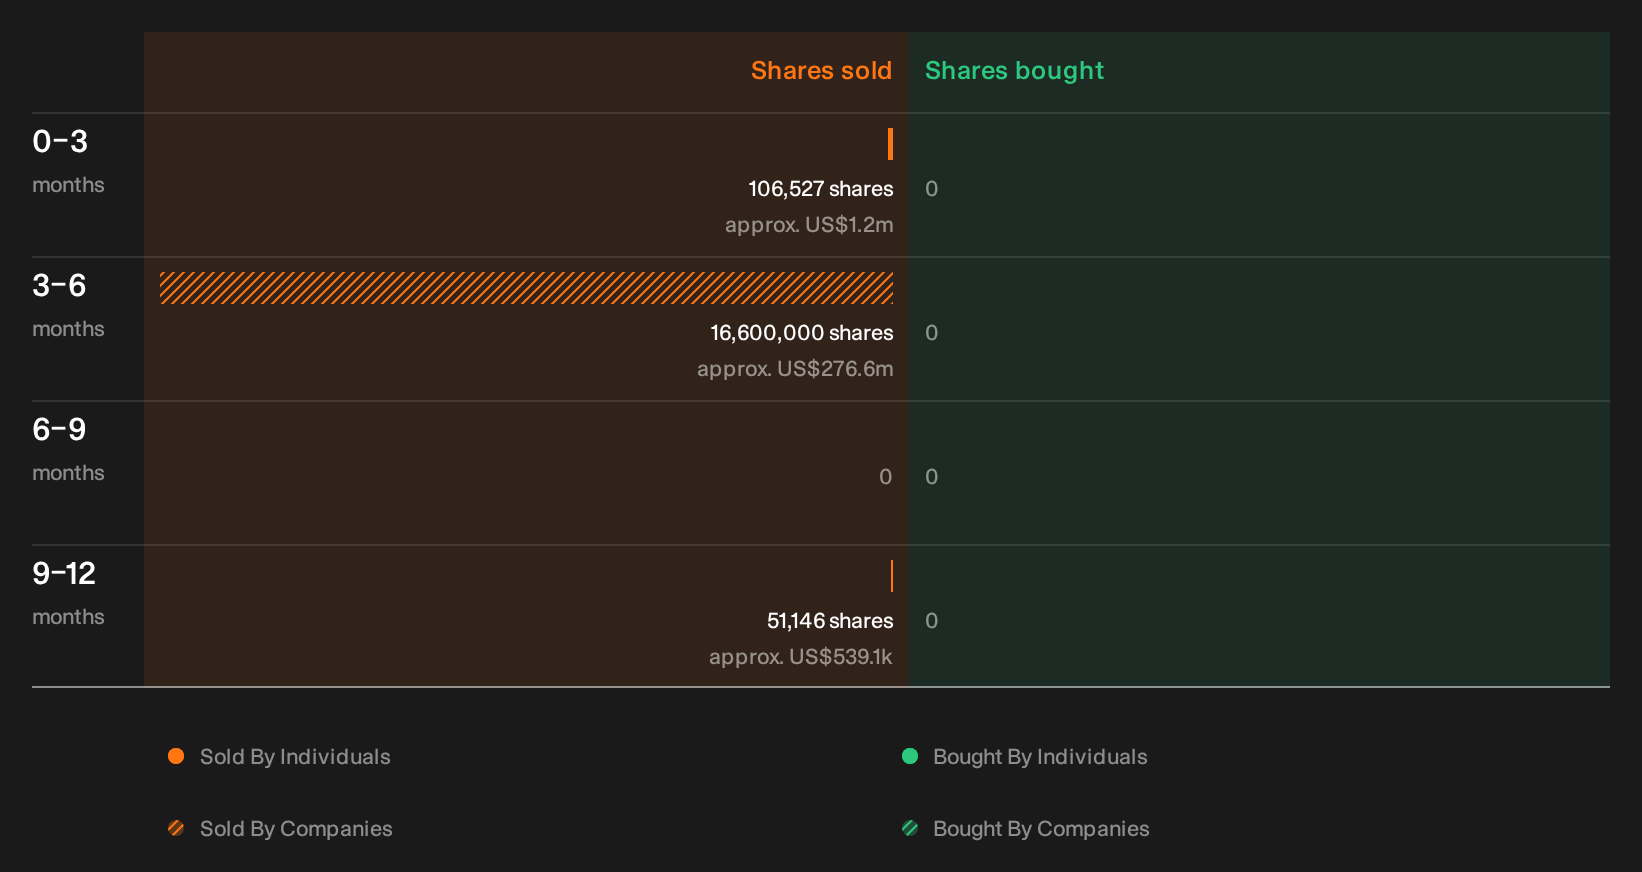
Before wrapping up your work on ProPetro Holding, it is worth knowing that recent management share transactions have been picked up by our checks, and the specific sellers, sizes and possible signals are there for you to unpack. See the recent insider selling flagged for ProPetro Holding.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com