
JOYY (JOYY) Could Be 9% Undervalued As Its AI Narrative Gains Attention
JOYY (NasdaqGS:JOYY) has drawn fresh attention after recent price moves, with the stock closing at US$80.38. Investors are weighing that share level against the platform operator’s latest financial profile and regional revenue mix.
Recent trading paints a picture of building momentum for JOYY, with a 30 day share price return of 9.41% and a 90 day gain of 21.00%. The 1 year total shareholder return of 38.91% and 3 year total shareholder return of about 13x suggest the move to US$80.38 fits into a much stronger multi year rerating story than the latest modest 1 day pullback of 0.83% would imply.
Capitalize on JOYY's recent momentum by scanning a curated set of 16 high quality undiscovered gems that share strong fundamentals yet remain off most investors' radar.After a move like JOYY’s, some investors see a lot of the easy upside as already captured, while others think the rerating has only started. Which camp does the current valuation support?
Most Popular Narrative: 8.7% Undervalued
JOYY’s most followed valuation narrative pegs fair value at about $88 per share, a touch above the recent $80.38 close. This puts more focus on how its earnings mix and regional spread could support that gap.
The company's strategic investment in AI and proprietary technology for content recommendation, user targeting, and real-time translation is creating differentiators that increase user engagement, conversion, and ARPU, while enabling JOYY to build durable competitive advantages that are likely to drive margin expansion and operating leverage.
See why 5 investors see JOYY as 9% undervalued.
Result: Fair Value of $88.01 (UNDERVALUED)
Still, that 8.7% valuation gap depends heavily on JOYY hitting ambitious analyst forecasts for revenue, margins, and BIGO Ads growth. Any shortfall could quickly test this bullish narrative.
Find out about the key risks to this JOYY narrative.
Another View on JOYY’s Valuation
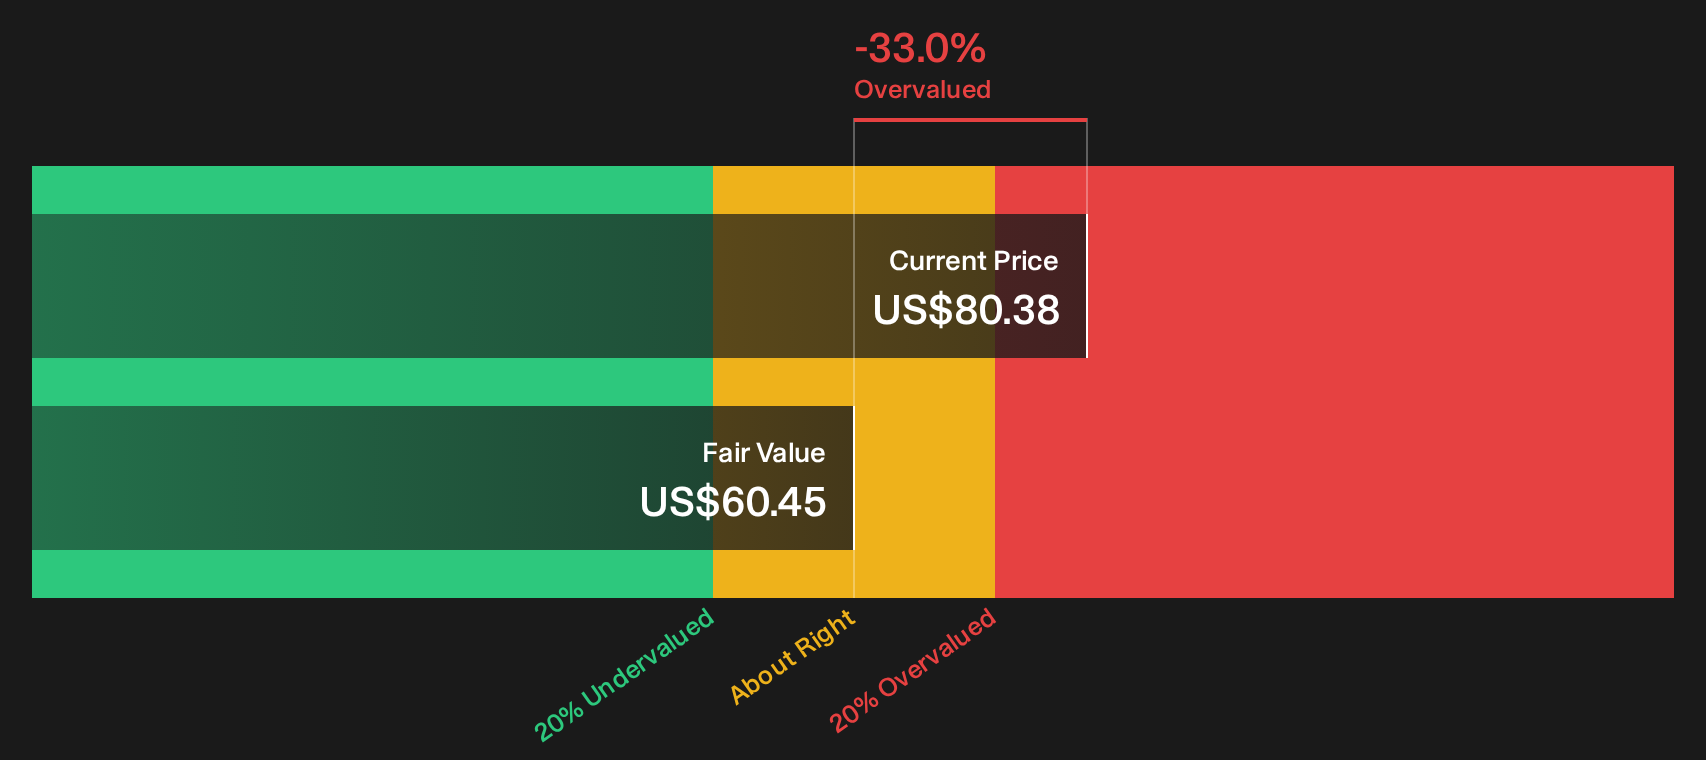
The first narrative leans on earnings forecasts and a future P/E of 19.3x to argue JOYY is about 8.7% undervalued at $80.38. Our DCF model comes to a very different conclusion, with an estimated future cash flow value of $60.45, which would frame the stock as overvalued on that basis. Which yardstick do you trust more when the signals clash this clearly?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages in the JOYY story so far. If you want to move quickly and build your own stance, start by weighing the 1 key reward and 1 important warning sign.
Looking for more JOYY style investment ideas?
Do not stop at JOYY. Use the Simply Wall Street screener to quickly surface fresh opportunities before they are crowded and potential mispricings narrow.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (23 results). This can help anchor the more volatile parts of your portfolio.
- Hunt for mispriced opportunities with a 30 high quality undervalued stocks. These may offer stronger fundamentals than their current share prices suggest.
- Dial down portfolio stress by focusing on a 31 resilient stocks with low risk scores. It screens for sturdier financial profiles and more measured risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com