
Beam Therapeutics (BEAM) Stock Looks Fully Valued Despite In Vivo Gene Editing Growth
Beam Therapeutics has been through a rough long term stretch, with the share price moving sharply over the past five years, so the question now is whether the current valuation lines up with the sales the business is actually generating. With the stock back around the mid US$20s, investors are re-checking what they are really paying for in terms of revenue from Beam's gene editing platform.
- The share price is down 72.1% over the past five years, which puts the focus squarely on whether the underlying sales story can justify where the stock trades today.
- Recent industry research flags Beam Therapeutics as a key player in in vivo gene editing, which can shape expectations for how quickly its commercial pipeline might translate into meaningful revenue and influence what investors are willing to pay for each dollar of sales.
- There is a second opinion on Beam Therapeutics worth weighing. See what analysts think Beam Therapeutics's shares could be worth.
The issue now is whether Beam Therapeutics' current share price is reasonable when judged against the sales the company is producing today and what that implies for its P/S multiple.
If you want to test the same "price versus sales" question beyond Beam Therapeutics, compare it with companies filtered by our 30 high quality undervalued stocks
Has Beam Therapeutics Run Too Far on Sales?
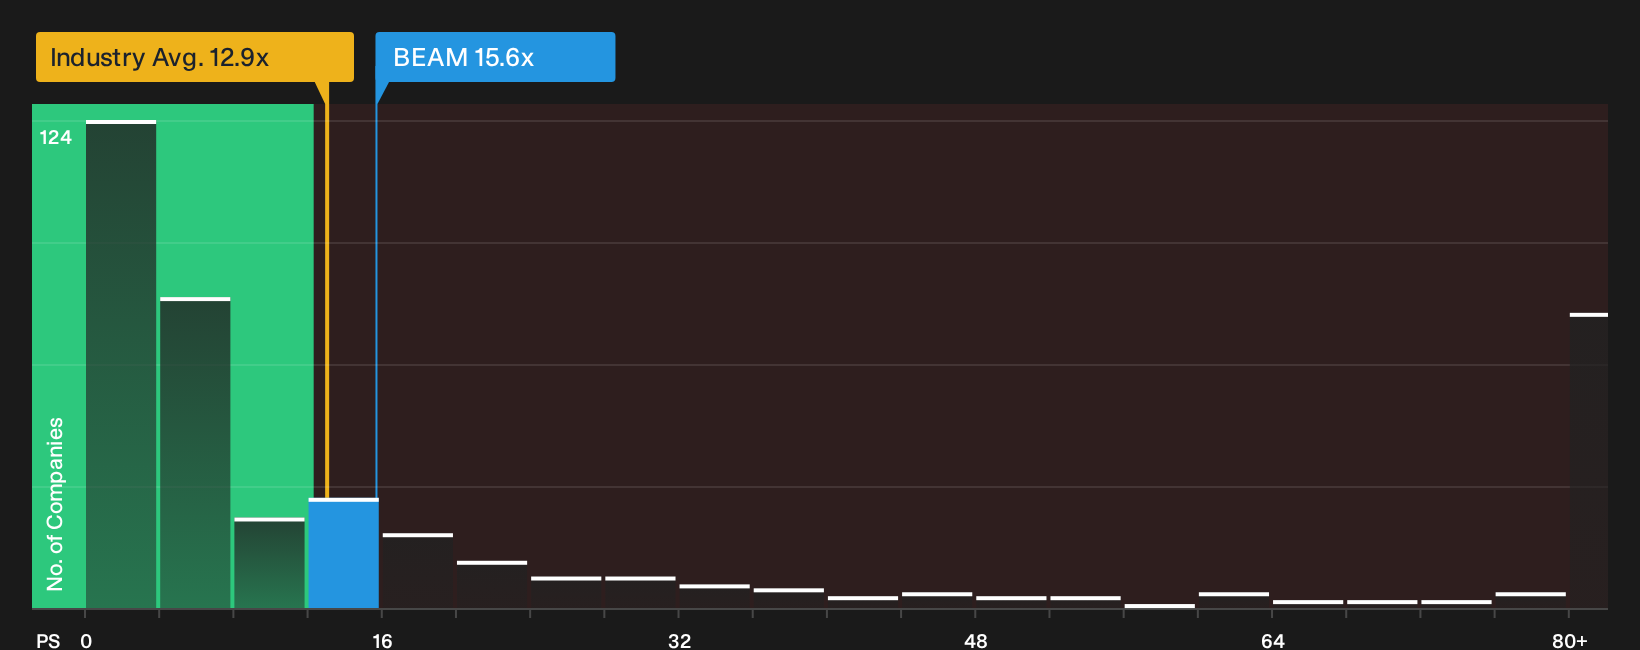
P/S is a useful lens for Beam Therapeutics because the business is still loss making and investors are largely paying for revenue and pipeline potential rather than current earnings. Beam is trading on a P/S of 15.6x, which is above the wider biotech industry average of about 12.9x and sits below the peer group average of roughly 18.8x for similar gene editing and biotech stocks.
The Fair Ratio model, which adjusts for Beam Therapeutics' growth profile, margins, scale and risk, flags today’s P/S as higher than the level that framework would typically support and the gap is wide enough that the model effectively treats the shares as screening very expensively on a sales basis. Recent research highlighting Beam as a key player in in vivo gene editing helps explain why investors are willing to pay a premium P/S multiple; yet the current price still embeds a rich expectation for how efficiently future sales might be converted into cash. Explore the numbers behind Beam Therapeutics's P/S valuation.
The Beam Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Beam Therapeutics pick up where the P/S debate leaves off and spell out the specific growth, margin and earnings paths that would need to play out for the stock to be worth materially more or less than it is today. Rather than just giving a single output from a ratio or model, they set out the future that number depends on, so you can watch over time whether those conditions still line up. Narratives sit on Simply Wall St's Community page and give you a structured way to weigh the different scenarios already implied in Beam Therapeutics' current valuation.
One of the top community narratives on Beam Therapeutics: 84% undervalued
"Beam represents "Gene Editing 2.0". Its base editing platform is a "molecular pencil", a precision instrument that chemically rewrites a single "letter" of the genetic code…
Discover why this Narrative puts Beam Therapeutics at 84% undervalued.
For Beam Therapeutics, who is steering the ship and how are they rewarded?
Valuation only tells you what the market is willing to pay today. The people in charge of Beam Therapeutics and the way their pay is structured can heavily influence what happens next. See who runs Beam Therapeutics and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com