
What Just Happened With Solaris Energy Infrastructure (SEI)?
Solaris Energy Infrastructure (SEI) just priced an upsized US$1.25b offering of 7.000% Senior Notes due 2032, a move that reshapes its funding mix and signals fresh capital for expansion.
Recent trading has been volatile for Solaris Energy Infrastructure, with the share price up 2.68% over the last day and 25.97% over 30 days, yet down 15.11% across 90 days. At the same time, the 1 year total shareholder return of 81.80% and very large 3 and 5 year total shareholder returns point to momentum that has built over a longer horizon.
Scan beyond Solaris Energy Infrastructure and compare this refinancing story with other power, grid and energy infrastructure plays in the curated 39 power grid technology and infrastructure stocks now shaping the next leg of the cycle.
Solaris Energy Infrastructure now trades well below both analyst targets and one intrinsic value estimate, after a sharp run over the past month. Is that gap a genuine margin of safety or a mirage?
Most Popular Narrative: 8% Undervalued
Solaris Energy Infrastructure closed at $67.43 against a widely followed fair value narrative of $73.00, so the note pricing now sits within a framework that already incorporates higher required returns and more cautious growth assumptions.
Despite ongoing strength in demand for infrastructure supporting data center electrification and manufacturing reshoring, tightening supply chains for critical power generation equipment have led to longer lead times and potential constraints on Solaris's ability to deploy new capacity. This could ultimately cap near-term revenue expansion and compress margins if costs rise faster than anticipated.
See why 3 investors see Solaris Energy Infrastructure as 8% undervalued.
Result: Fair Value of $73.00 (UNDERVALUED)
Still, that 8% undervaluation story could unravel quickly if Solaris Energy Infrastructure’s heavy reliance on one data center client or tightening turbine supply chains starts to bite.
Find out about the key risks to this Solaris Energy Infrastructure narrative.
Another View On Solaris Energy Infrastructure’s Valuation
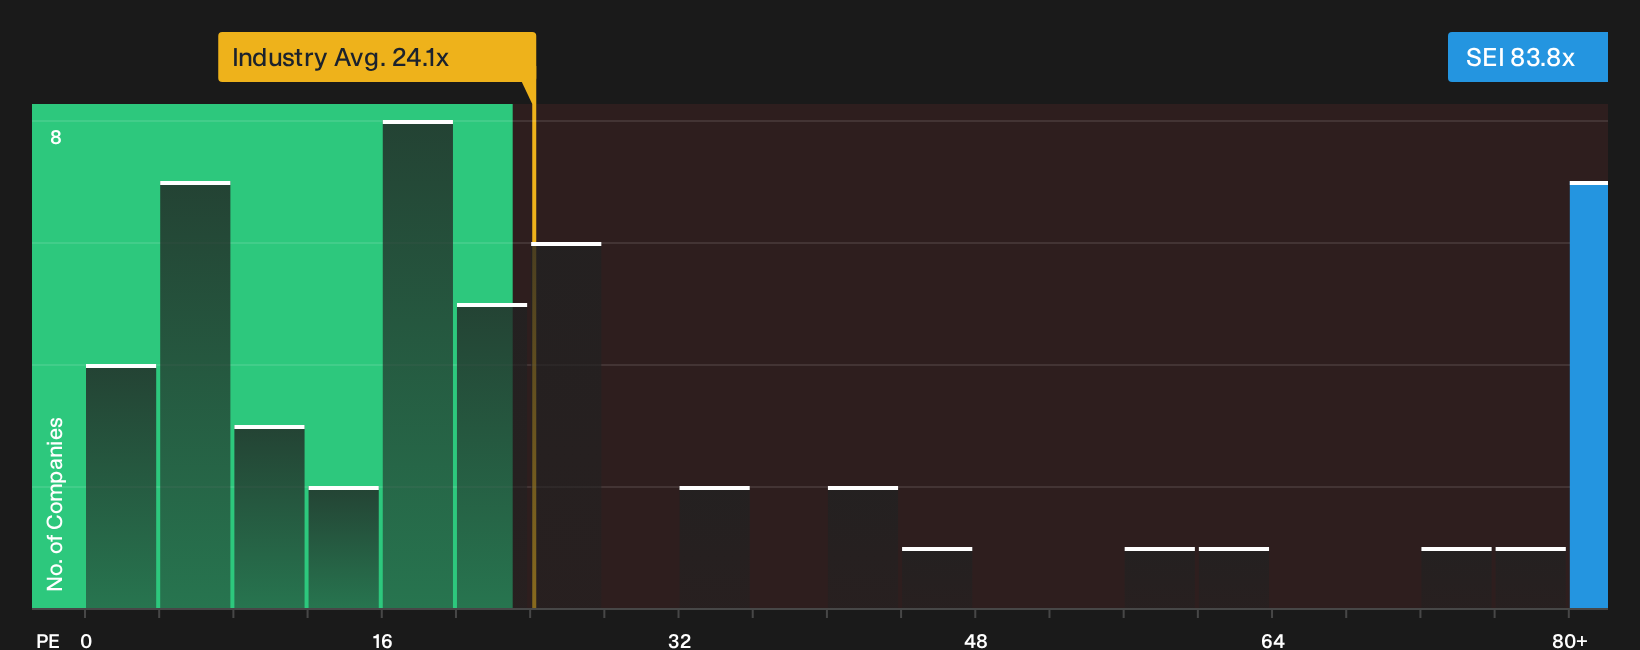
The fair value story of $73.00 suggests Solaris Energy Infrastructure looks modestly undervalued on future earnings and contracts. A quick check against the current P/E of 83.8x, an industry average of 24.1x, and a fair ratio of 28x tells a different story, with a wide gap that raises real valuation risk if sentiment cools.
That kind of premium can reward investors if the growth narrative lands perfectly, but it can also unwind fast if expectations reset or execution slips. Which side of that trade do you want to be on when the next round of numbers hits?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Solaris Energy Infrastructure so far, right, with rich expectations but also real operational and client concentration questions pushing at the edges of the story. Move quickly, review the underlying numbers, then weigh the 4 key rewards and 3 important warning signs.
Looking for more Solaris Energy Infrastructure style ideas?
If Solaris Energy Infrastructure has your attention, do not stop here. Broaden your watchlist now or you risk missing better risk reward trade offs.
- Target potential mispricing by scanning a curated set of 30 high quality undervalued stocks that pair strong fundamentals with more grounded expectations.
- Prioritize resilience by focusing on a list of solid balance sheet and fundamentals (23 results) that can better handle funding shocks and tougher credit conditions.
- Spot earlier-stage opportunities by reviewing a 9 elite penny stocks with strong financials that already show improving quality instead of relying purely on hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com