
Replimune Group (REPL) Could Be 46% Undervalued Following FDA Lawsuit Questions
Why Replimune Group Stock Is Back in Focus
Replimune Group (REPL) is back under the microscope after a securities class action accused the biotech of withholding specific FDA criticisms tied to the study design and data analyses for its RP1 cancer therapy candidate.
The lawsuit lands after a busy stretch for Replimune Group, which recently doubled its authorized share count to 300,000,000 and has seen its 90 day share price return rise 16.44% and its 1 year total shareholder return surge 211.54%. However, the 5 year total shareholder return is down 56.11% and the stock has slipped 11.90% on a 30 day share price basis to close at US$12.96.
Scan beyond Replimune Group and see how other high potential businesses under pressure are trading with our hand picked 16 high quality undiscovered gems right now.
Bulls see Replimune Group’s pullback and lawsuit as noise around a long term cancer platform story. Bears point to fresh legal and dilution risks. Which case does the current valuation support?
Most Popular Narrative: 46% Undervalued
Replimune Group last closed at $12.96, while the most followed valuation story pins fair value at $24.00 using a 7.63% discount rate. That gap turns the recent pullback and lawsuit into side notes for investors who focus on the long term melanoma franchise.
The TUDRIQEV label allows injection of superficial, deep and visceral lesions with flexible dosing and retreatment beyond the initial eight doses for patients who keep responding, which can support higher utilization per eligible advanced melanoma patient and therefore greater potential revenue per account over time.
See why 0 investors see Replimune Group as 46% undervalued.
Result: Fair Value of $24.00 (UNDERVALUED)
Still, the Replimune Group story hinges on TUDRIQEV’s confirmatory survival data and the fallout from class action lawsuits. Either factor could puncture this bullish narrative.
Find out about the key risks to this Replimune Group narrative.
Another View on Replimune Group’s Valuation
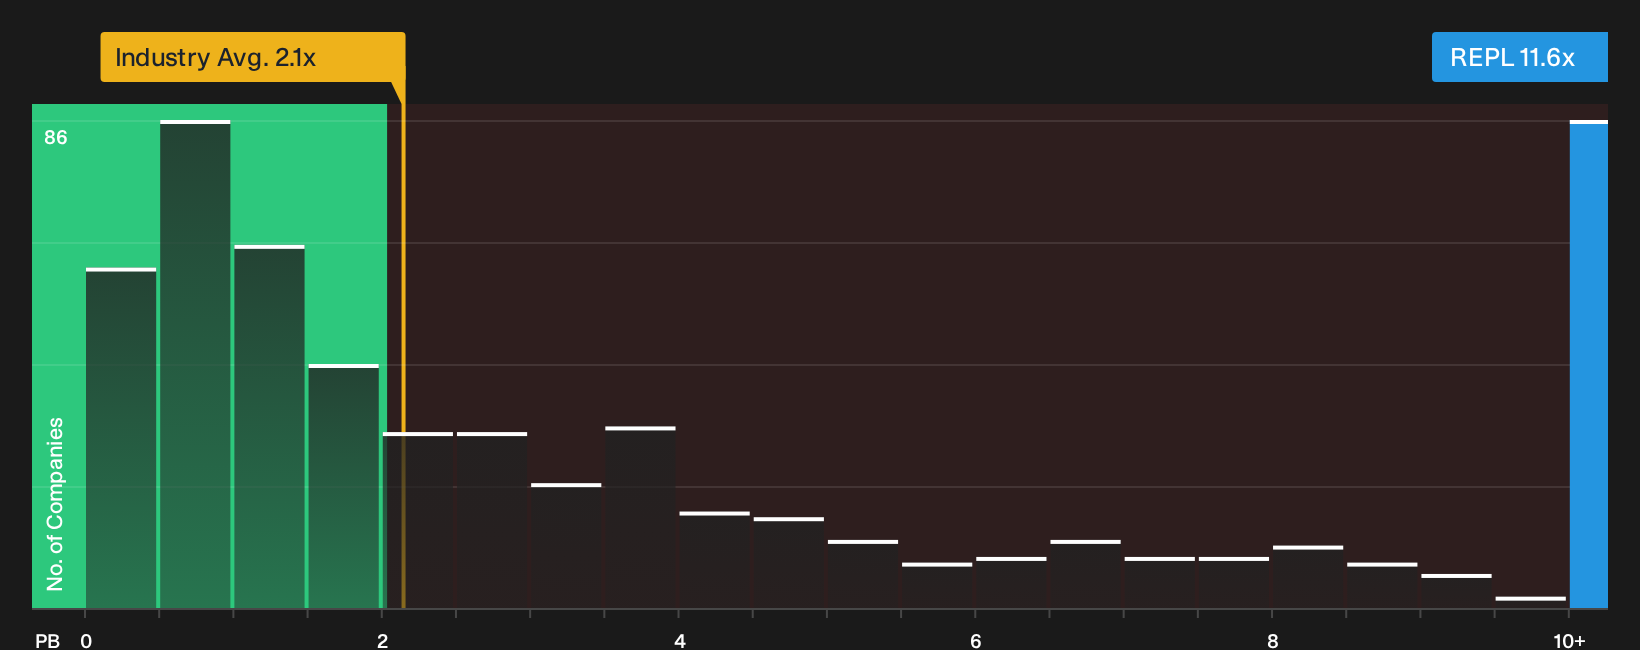
The earlier fair value story leans heavily on future earnings power. A different lens comes from looking at Replimune Group’s current P/B of 11.6x, which sits well above both the US Biotechs industry at 2.2x and peer average at 3.1x, so the multiple already prices in a lot of optimism.
If the share price drifts back toward those lower P/B levels, investors who rely only on optimistic earnings forecasts could face a painful reset in expectations. The question is whether you believe today’s premium truly reflects the long runway that bullish analysts are building into their models.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Replimune Group so far. If you care about both the upside story and the potential downside, move quickly and weigh the 2 key rewards and 5 important warning signs
Looking for more Replimune Group style investment ideas?
If Replimune Group has your attention, do not stop here. The market is full of other opportunities that could better match your risk and return goals.
- Target steadier potential with a focus on quality and value by scanning our 30 high quality undervalued stocks for ideas that may already be priced conservatively.
- Build a portfolio with fewer unpleasant surprises by reviewing the 31 resilient stocks with low risk scores and concentrating on businesses with stronger overall risk profiles.
- Get ahead of the crowd by hunting through the 16 high quality undiscovered gems where smaller, less followed stocks might align with your return ambitions before others notice.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com