
Stewart Information Services (STC) Stock Looks Hard To Call On Its 53% Run
Stewart Information Services has slipped in recent months after a strong multi year run, which puts fresh attention on whether the current share price lines up with what its earnings can reasonably support. With the stock now trading around US$61.98, the key issue is how that recent share performance squares with the profit power of the underlying business.
- The share price has gained 52.6% over the past 3 years, which raises the question of how much earnings strength is already reflected in the valuation.
- The group relies heavily on converting fee based title and real estate related revenue into consistent profits, so the durability of those earnings streams may support or constrain what investors are willing to pay for each dollar of income.
- The analysts covering Stewart Information Services have run their own numbers. See what analysts think Stewart Information Services's shares could be worth.
The stock's next move may depend on whether Stewart Information Services' current earnings are strong and reliable enough to justify where the shares trade today.
If you want to stress test this same earnings question beyond Stewart Information Services, run the numbers across 30 high quality undervalued stocks to see how other companies line up against their profit power.
Where Does Stewart Information Services Sit on Earnings?
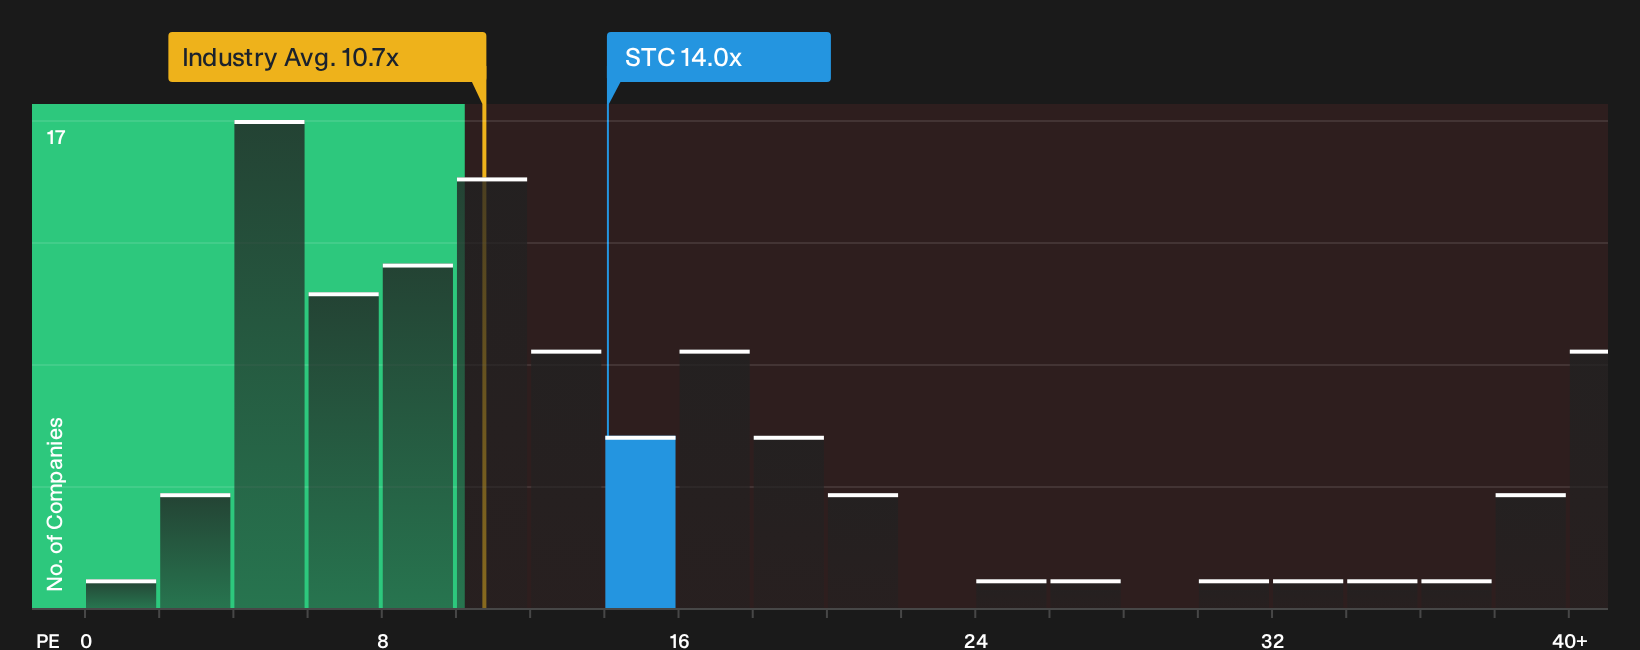
The P/E ratio works well for Stewart Information Services because earnings are a key yardstick for fee based, financial businesses. On this metric, the stock trades on roughly 14.0x trailing earnings. That is higher than the Insurance industry average of about 10.7x and also above the peer group around 11.0x, so the shares change hands at a premium to many comparable insurers.
The valuation model that blends Stewart Information Services' growth profile, profitability record, size and risk points to a fair P/E that sits very close to the current figure. That leaves the multiple looking about right on this framework, with little clear signal that the price is either stretched or particularly cheap without going deeper into the quality and stability of those earnings. Explore the numbers behind Stewart Information Services's P/E valuation.
The Stewart Information Services Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Stewart Information Services pick up where the valuation work leaves off by translating that 14.0x P/E and the current share price into clear assumptions about future growth, profitability and earnings that would need to play out for the stock to be worth substantially more or less than today. Instead of a single ratio or model outcome, they lay out the underlying future it relies on, so you can watch how reality tracks against those expectations on the Community page.
One of the top community narratives on Stewart Information Services: 25% undervalued
"The Real Estate Solutions business line sees opportunities for growth through expanding lender relationships and cross-selling products, which could stabilize and eventually increase net margins…"
Discover why this Narrative puts Stewart Information Services at 25% undervalued.
One more Stewart Information Services check that belongs next to the P/E
Price comparisons tell you what investors pay today, but the projected earnings path a few years out shows what analysts think that cash machine might look like next. Explore where analysts expect Stewart Information Services to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com