
Invisio (OM:IVSO) Could Be 26% Undervalued Following Defence Tech Tailwinds
Sector tailwinds put Invisio in focus
Fresh attention on European defence technology, highlighted by Tekever’s reported $6.4b valuation and $580m funding round, has drawn investors back to Invisio (OM:IVSO) as governments lift security spending.
Recent moves in Invisio’s share price tell a mixed story. The stock has climbed over the past month, with a 30 day share price return of 5.03% and a 90 day gain of 10.70%. However, it remains down 9.38% year to date, and the 1 year total shareholder return has declined 28.56%. This leaves longer term holders with a 41.79% total shareholder return over five years as defence tech interest resurfaces.
Scan the sector tailwinds lifting Invisio and compare it with a hand-picked group of defence and security contractors in our list of solid balance sheet and fundamentals (198 results)
Invisio has rebounded in recent weeks yet still carries a weaker 1 year record, so is the recent rerating just the start, or already most of the opportunity?
Most Popular Narrative: 26% Undervalued
Analysts following Invisio see a gap between the current share price of SEK233.8 and a narrative fair value of SEK316.43, with that view shaped by how quickly defence communication upgrades might convert into firm orders.
Ongoing soldier modernization and digitization programs are fueling demand for integrated communication and hearing protection systems. Invisio's rapid pace of product innovation (e.g., the X7 in-ear headset, Intercom Link, and recent UltraLYNX acquisition) positions the company to capture a larger share of upcoming multi-year upgrade cycles, supporting future revenue expansion and margin stability.
See why 13 investors see Invisio as 26% undervalued.
Result: Fair Value of SEK316.43 (UNDERVALUED)
Still, Invisio’s reliance on chunky government contracts and rising operating costs could quickly upset the bullish narrative if orders slow or pricing pressure increases.
Find out about the key risks to this Invisio narrative.
Another View on Invisio’s valuation
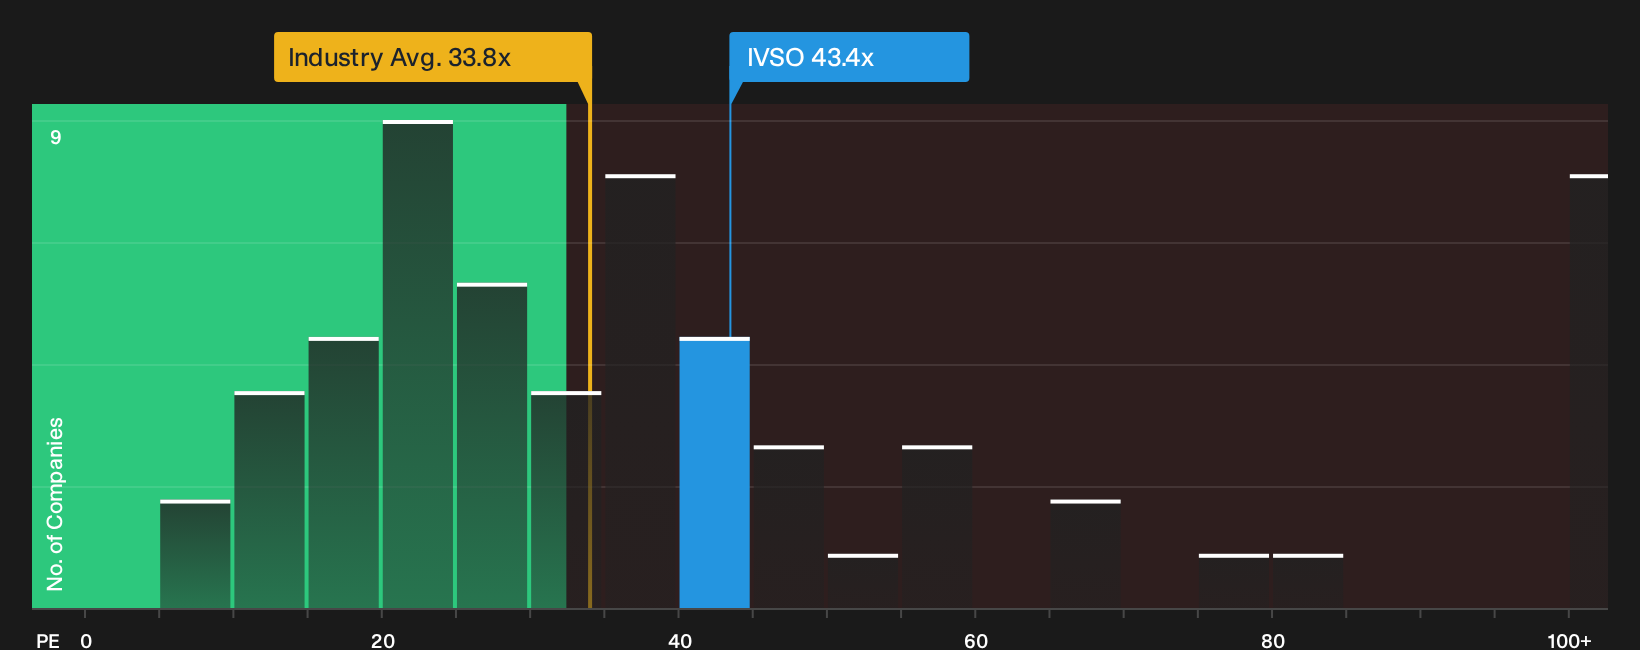
The fair value story for Invisio looks very different when shifting to earnings multiples. The stock trades on a P/E of 43.4x, compared with 33.8x for the wider European Aerospace & Defense group, and a fair ratio of 38.7x that our model suggests the market could move toward.
Peers on average sit even higher at 70.6x, so Invisio lands between a richer sector valuation and a lower internal fair ratio. This positioning hints at real pricing risk if sentiment cools or earnings expectations soften. The key question is whether you think Invisio’s forecast profit growth and quality justify staying above that fair ratio threshold.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early opportunity? If Invisio’s story has you on the fence, pull up the full data set, stress test the assumptions, and weigh the 3 key rewards.
Looking for more investment ideas beyond Invisio?
If Invisio has sharpened your focus on defence and quality, do not stop there. Broaden your watchlist so you are not late to the next opportunity.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (198 results).
- Hunt for mispriced opportunities with strong quality markers using the 171 high quality undervalued stocks.
- Build a foundation of cash returns by checking companies in the 161 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com