
ITOCHU (TSE:8001) Dropped, So What Is Catching Attention Now?
ITOCHU (TSE:8001) has drawn renewed attention after recent share price moves, with the stock down 3.1% on the day but still higher over the past month and the past 3 months.
Recent trading has cooled some of that enthusiasm, with the share price down 5.7% over the past week. This follows a 30 day share price return of 5.5% and a 90 day share price return of 21.8%, while the 1 year total shareholder return of 32.8% and 5 year total shareholder return of 286.8% show that momentum for ITOCHU has been building over a longer horizon.
See how ITOCHU compares with other momentum-driven industrials by reviewing our hand picked list of list of solid balance sheet and fundamentals (21 results)
Bulls point to ITOCHU’s strong multi year shareholder returns and diversified revenue base. Bears highlight the recent pullback and questions around how much optimism is already in the price. Which story does the current valuation support?
Most Popular Narrative: 8% Overvalued
On the latest numbers, the most followed narrative pegs ITOCHU’s fair value at ¥2,060, which sits below the current ¥2,234 share price and frames the recent strength as slightly ahead of those underlying assumptions.
While the shift toward M&A, conversions to subsidiaries and business reforms is intended to support organic growth, integration costs and potential missteps in capital allocation could pressure free cash flow and dilute future earnings growth.
See why 4 investors see ITOCHU as 8% overvalued.
Result: Fair Value of ¥2,060 (OVERVALUED)
Still, if non resource consumer segments like Food and ICT stay resilient and execution on business reforms improves, the bearish ITOCHU narrative could face pressure.
Find out about the key risks to this ITOCHU narrative.
Another View: ITOCHU Through The P/E Lens
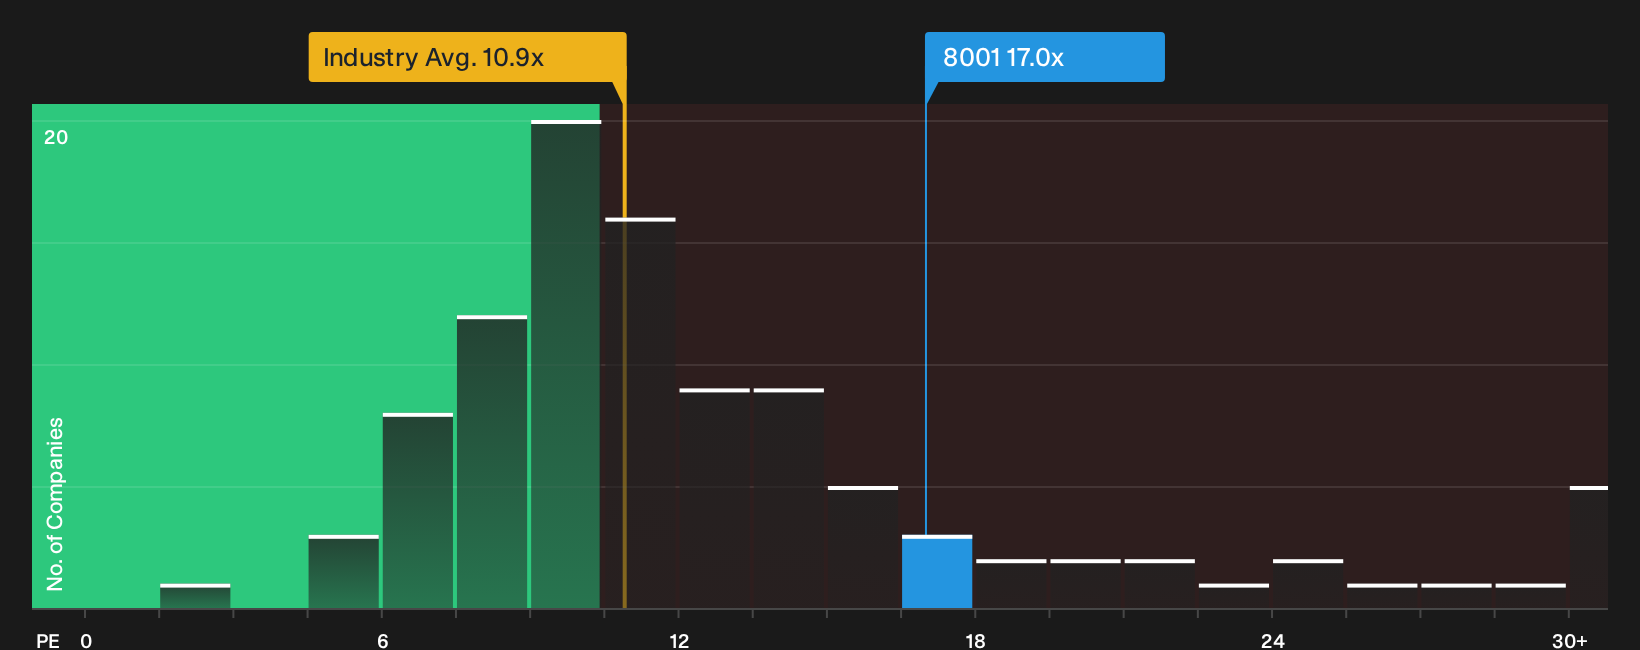
While the fair value narrative pins ITOCHU as about 8% overvalued at ¥2,060, the P/E picture is less one sided. The stock trades on roughly 17x earnings, richer than the JP Trade Distributors average of 10.9x and the peer group at 15.7x.
The fair ratio for ITOCHU is 23x, which implies the market could shift toward paying a higher multiple if sentiment or fundamentals change. That gap cuts both ways. It leaves room for optimism but also raises the question of how much valuation risk you are really comfortable carrying.
To see how the current pricing stacks up against detailed earnings and peer comparisons, including where the fair ratio might pull the market over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around ITOCHU’s valuation and momentum will not settle themselves, so pressure test the optimistic and cautious angles by reviewing the 2 key rewards and 1 important warning sign
Looking for more ITOCHU-sized investment ideas?
If you stop with ITOCHU, you risk missing out on other opportunities. Use the Simply Wall St screener to scan widely and upgrade your watchlist.
- Target resilient cash generators that trade below what their quality suggests by running a focused search through the 18 high quality undervalued stocks.
- Build a steadier income stream by zeroing in on companies that feature in our curated group of 14 dividend fortresses.
- Protect your downside by concentrating on companies highlighted in the 21 resilient stocks with low risk scores, which pair stronger balance sheets with calmer price swings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com