
Why Cybersecurity Stocks Could Benefit As AI Regulation Tightens
Regulators are circling OpenAI and autonomous agents, and the early winners of the AI boom suddenly look less certain. Money that once chased pure AI excitement may start hunting for tools that keep those powerful systems in check. This article explores that shift and unpacks three cybersecurity stocks exposed to the same headlines, showing how investors are reassessing risk, resilience, and where protection might matter more than raw AI potential.
The stocks covered in this article are only a starting sample, and the full cybersecurity screen on Simply Wall St surfaced 52 more companies with equally compelling narratives that are not discussed below.
Identify potential opportunities across size, quality, valuation, and risk filters in one place and go straight to the Cybersecurity Stocks screener.
Comp (WSE:CMP)
Comp leans directly into the Cybersecurity Stocks theme as a pure IT and network security provider, offering cryptography, e-signature, IT integration, and network protection services for Polish enterprises, including AI-driven traffic. The Warsaw-based business, founded in 1990, is valued at about PLN1.9 billion, putting it firmly in mid-cap territory.
Comp operates where AI applications meet practical defense, running a focused cybersecurity and network services operation as regulators push for tighter controls on autonomous systems. Its position in the market and evolving margins draw interest, although one potential pressure around external funding could be important for how its profitability profile develops.
That funding question is exactly what the Comp financial health report can help you unpack before margins and cash needs start to decouple.

Insight Enterprises (NSIT)
Insight Enterprises plugs into the cybersecurity theme as the behind the scenes integrator that stitches together hardware, cloud services, and security controls for large organisations wrestling with AI enabled threats and compliance pressure.
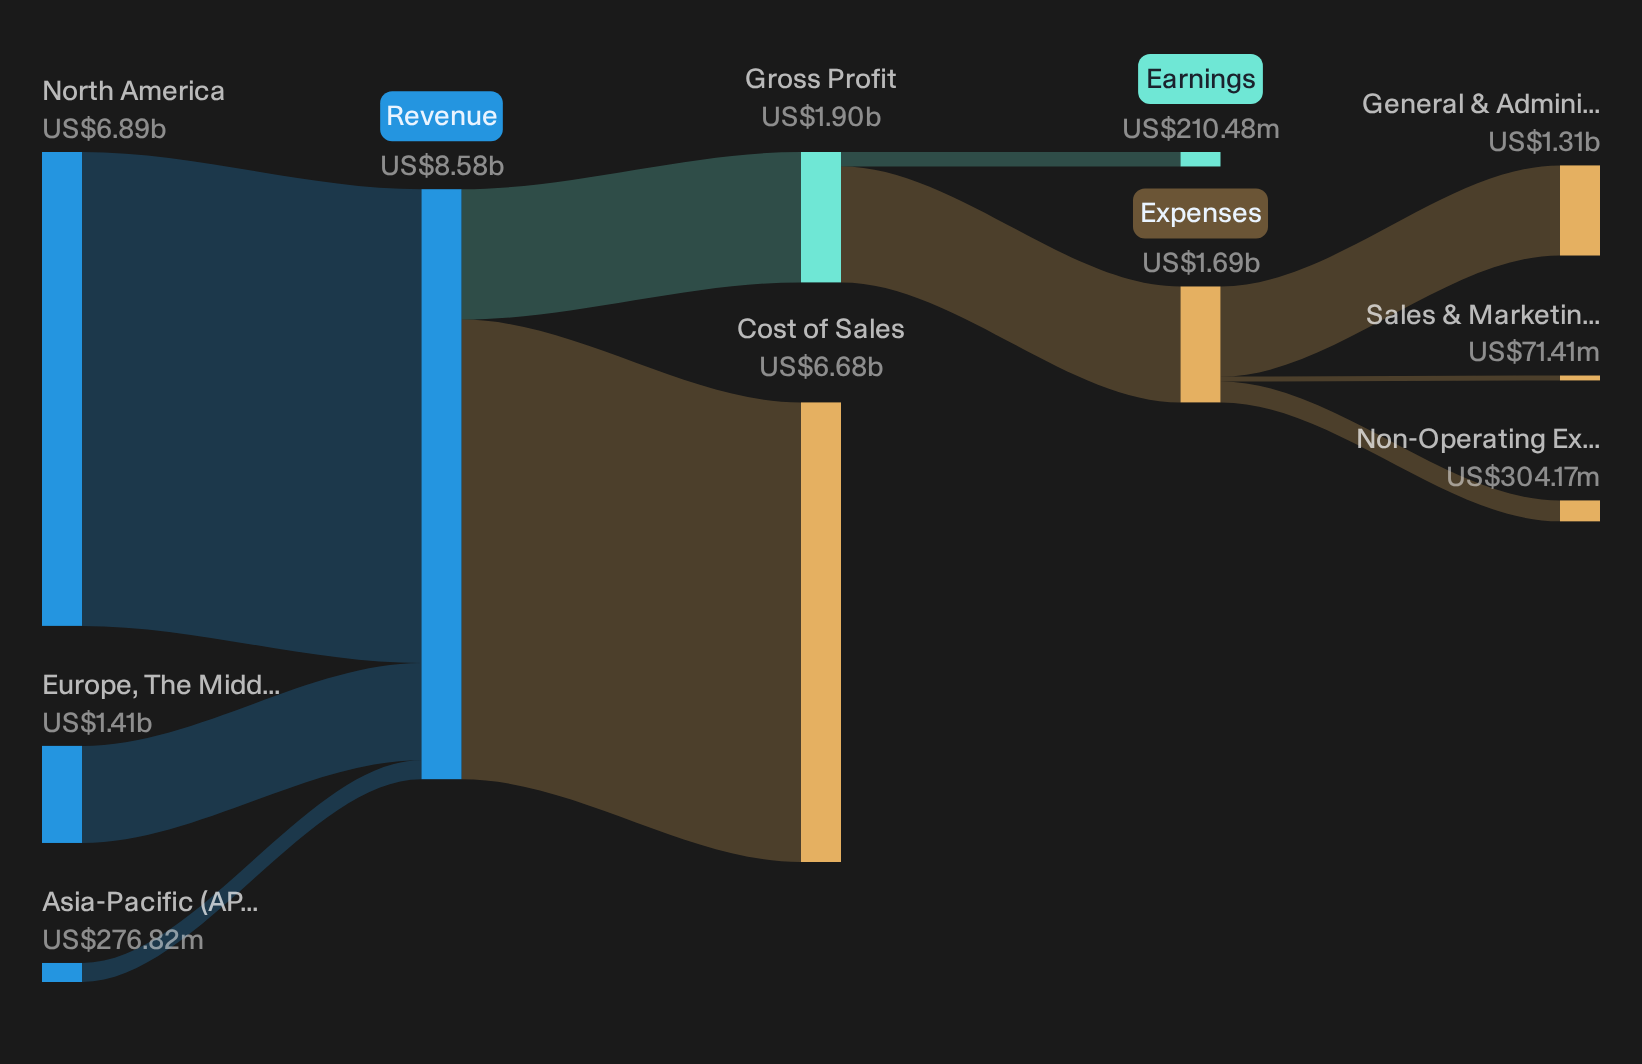
Insight Enterprises provides multicloud, cybersecurity, data and AI, and workplace technology solutions. It generates about US$6.9b from North America, US$1.4b from EMEA, and US$276.8 million from APAC, and carries a market value of roughly US$4.6b.
"Growing cybersecurity risks and regulatory demands are forcing organizations to increase investment in security solutions. Insight's expanding end-to-end security offerings and successful execution of multi-year managed services contracts suggest a sustainable lift to higher-margin recurring revenue streams and thus a potential improvement in long-term net margins."
What happens to those margin ambitions if one unseen pressure on how clients allocate AI and security budgets breaks against Insight Enterprises?
If that unseen pressure matters for your thesis, the full narrative for Insight Enterprises shows where Insight Enterprises could still accelerate or stall as AI security spend gets reshuffled.
GB Group (LSE:GBG)
GB Group sits right in the identity and access control layer of cybersecurity, helping businesses check who is really on the other side of a transaction as AI agents start acting on user accounts without human oversight.
GB Group provides identity verification, document checks, biometrics and fraud screening, with £175 million from Identity, £89 million from Location and £22 million from Global Fraud Solutions, and a market cap of about £339 million.
"The accelerating global adoption of digital identity, compliance regulations (such as KYC/AML), and digital financial services is set to structurally elevate addressable markets for GB Group, positioning the company as a pivotal provider to financial institutions, e-commerce, and governments, creating multiyear tailwinds that could drive annualized double-digit revenue growth."
What investors really have to weigh is how one unresolved pressure on profitability shapes the pay-off from that identity driven demand.
If that profitability pressure is what you are testing, the full narrative for GB Group maps where GB Group’s identity engine could accelerate, stall, or stay masked by short term noise.

Seeking Alternatives Beyond Cybersecurity?
Fresh ideas move first and slow research often gets caught watching from the sidelines while momentum is already flying. Scan these under the radar lists before the window drops and get in early.
- Spot income-focused opportunities with resilient cash flows by running through the 159 dividend fortresses that screens for higher yielding businesses while those yields still reflect current prices.
- Track early movers in automation by reviewing the curated 94 robotics and automation stocks that concentrates on companies building real revenue around robotics and industrial efficiency.
- Explore early-stage AI names by filtering through the 144 AI small caps that highlights smaller businesses where any shift in earnings can influence the share price.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com