
Is Higher Earnings Forecasts Altering The Investment Case For Knight Swift Stock (KNX)?
- Knight-Swift Transportation Holdings recently attracted attention after analysts raised earnings estimates for 2026 and 2027, tying those projections to acquisition activity, tractor fleet management, and expectations for better operating margins.
- The fresh broker outlook highlights how Knight-Swift’s mix of acquisitions, cost discipline, and consistent dividends and buybacks is shaping expectations for its longer term cash generation profile.
- We will now look at how Knight-Swift Transportation Holdings' investment narrative is affected by higher earnings forecasts tied to acquisition execution.
Knight-Swift Transportation Holdings Investment Narrative Recap
For Knight-Swift Transportation Holdings to make sense in your portfolio, you need to be comfortable with a freight carrier that is investing heavily in LTL expansion, technology and network efficiency while margins sit at 0.6% and trail last year’s 2.2%. The core belief is that today’s integration headaches and upfront costs can eventually translate into better asset use and steadier free cash generation.
The share price has already climbed about 72.2% over the past year. The key near term swing factor is whether freight volumes and pricing are strong enough to support that optimism around future cash flows. The biggest operational risk is that LTL integration and cost reduction projects stay messy for longer, which would keep profitability subdued while fixed costs and capital spending remain high.
The most relevant recent development for this story is the cluster of higher earnings estimates for 2026 and 2027 tied to Knight-Swift Transportation Holdings’ acquisition activity and tractor fleet management. Those projections lean heavily on smoother LTL integration, better network density, and more efficient use of the existing fleet to support margins that are currently under pressure.
For you as a shareholder, the question is how that outlook lines up with the DCF assumptions that already bake in free cash flow expansion into the later 2020s. If integration drags, if freight demand stays soft, or if tech and cost initiatives require more capital than expected, the actual cash generation profile could end up out of sync with what the upgraded models are implying today.
Knight-Swift Transportation Holdings' narrative projects US$9.5b revenue and US$719.3m earnings by 2029. This projection assumes 7.0% yearly revenue growth and an earnings increase of about US$676.4m from US$42.9m today.
Uncover why Knight-Swift Transportation Holdings' fair value indicates a 32% potential upside to its current price and a valuation gap that could narrow quickly.
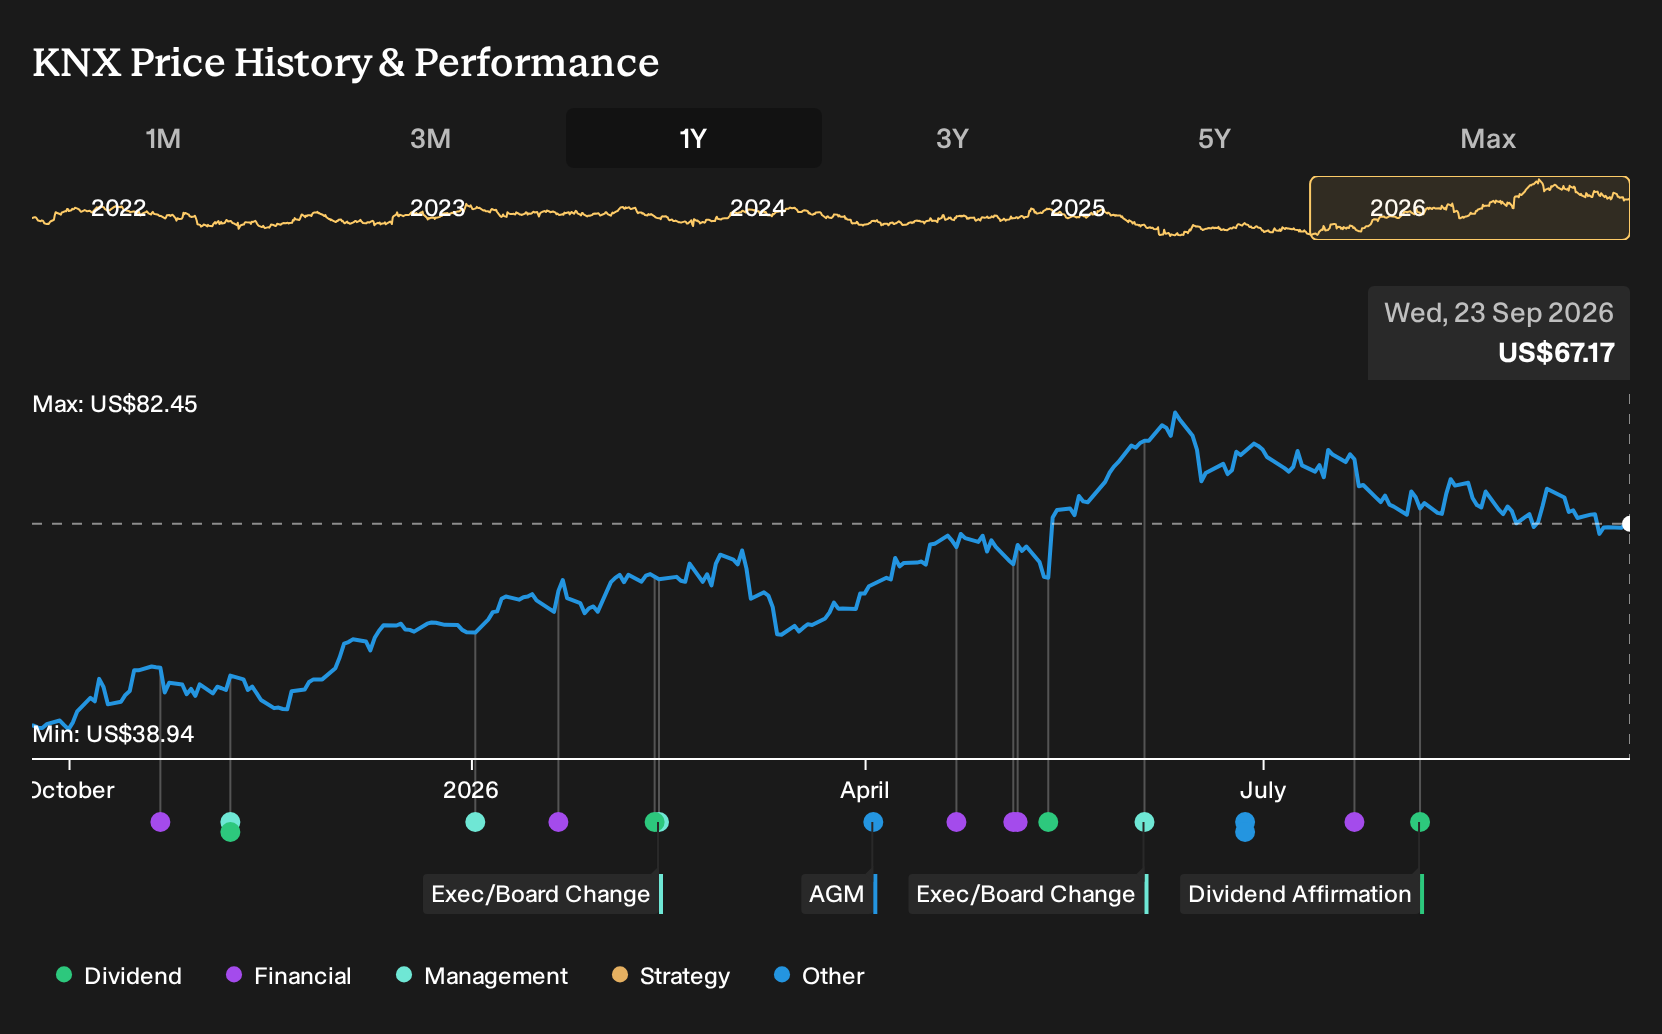
Exploring Other Perspectives
One alternate angle on Knight-Swift Transportation Holdings focuses on the bullish catalyst of higher long term margins. Before this news, the most optimistic analysts were already penciling in US$10.6b of revenue and US$1.1b of earnings by 2029. That outlook is much more upbeat than consensus, and fresh information could nudge both narratives in new directions.
Explore 3 other Knight-Swift Transportation Holdings fair value estimates, including one that suggests up to 78% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Knight-Swift Transportation Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Knight-Swift Transportation Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Knight-Swift Transportation Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Knight-Swift Transportation Holdings?
If Knight-Swift Transportation Holdings caught your eye but you want a broader watchlist, the Simply Wall St Screener can help you quickly spot other businesses with return profiles and balance sheets that match your own risk appetite.
- If you prefer resilient operators that focus on capital strength and staying power over headline growth stories, start with this 31 resilient stocks with low risk scores to see which candidates fit that brief.
- If income is a priority and you want payouts that might complement Knight-Swift Transportation Holdings in your portfolio, you can shortlist companies from this group of 7 dividend fortresses.
- Investors who care most about solid finances and robust fundamentals can build a watchlist straight from this list of solid balance sheet and fundamentals (23 results) and then filter down from there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com