
Global Ship Lease (GSL) Stock May Still Offer Value As Charter Strength Faces A 203% Run
Global Ship Lease has delivered a powerful run for shareholders in recent years, which naturally puts the focus on whether the current US$44.54 share price is supported by the earnings behind it. With the stock having already created substantial gains for long term holders, the question now is how much of the underlying profit story is already reflected in the multiple investors are paying today.
- Over the past 3 years, Global Ship Lease has returned about 202.7%, which raises the stakes on whether the present earnings profile can carry that kind of value creation forward.
- The business relies heavily on contracted charter income and capital intensive vessels, so the timing and durability of its earnings, as well as ongoing fleet investment needs, can have a direct impact on what looks like a reasonable P/E at today’s share price.
- Your read on Global Ship Lease is one view; the desks covering it have another. See what analysts think Global Ship Lease's shares could be worth.
For investors, the debate is whether Global Ship Lease’s current share price is adequately explained by the earnings it is generating today and is expected to produce over time.
If you want a broader set of ideas while you assess whether Global Ship Lease’s earnings justify its run, a focused stock screen built around 30 high quality undervalued stocks can be a useful next step.
Is Global Ship Lease Still Cheap on Earnings?
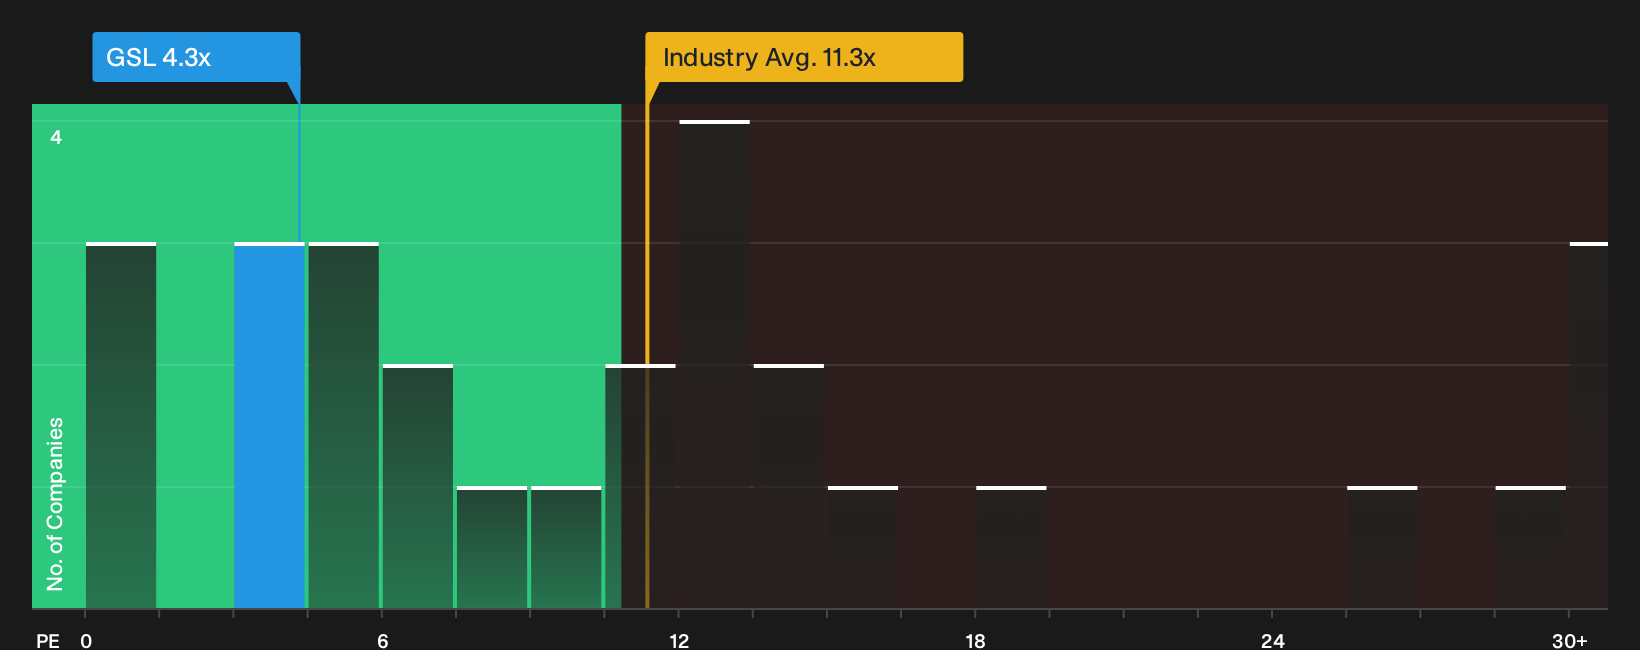
The P/E lens fits Global Ship Lease because earnings are a central reference point for how investors value its contracted charter income. On this measure, the stock trades on about 4.3x earnings, which is well below the broader shipping industry average of roughly 11.3x and also below a peer group near 14.9x. That gap indicates the market is applying a heavy discount to each dollar of profit the business currently generates.
A tailored fair P/E based on Global Ship Lease’s own profile sits above where the shares change hands today, so the current multiple appears undervalued against that benchmark. For a capital intensive owner of container vessels, such a low earnings tag leaves a lot of the judgment with you. The key question is whether the charter book, balance sheet and reinvestment needs justify the market’s caution, or whether the lower P/E offers compensation for those risks. Explore the numbers behind Global Ship Lease's P/E valuation.
The Global Ship Lease Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Global Ship Lease leaves off by spelling out which earnings, margin and growth assumptions would need to hold for the stock to be worth materially more or less than the current price, and they sit on the Community page. Rather than a single P/E or model line, each scenario lays out the key inputs behind its fair value so you can compare those assumptions with actual results over time.
One of the top community narratives on Global Ship Lease: 13% undervalued
"GSL's disciplined capital allocation and opportunistic fleet renewal strategy is increasing overall fleet efficiency and lowering average operating costs…"
Discover why this Narrative puts Global Ship Lease at 13% undervalued.
Global Ship Lease’s valuation still hinges on who is steering the ship
Before you decide what Global Ship Lease is worth, it helps to know who is making the big capital calls and how their incentives line up with your outcomes. See who runs Global Ship Lease and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com