
Penske Automotive Group (PAG) Could Be Fully Valued Following Its Recent Run
Penske Automotive Group (PAG) has drawn fresh attention after recent share performance, with the price closing at US$209.66 and showing mixed short term moves alongside stronger longer term total returns.
Short term, Penske Automotive Group has given back some ground with the share price down 2.1% over the past week and 3.9% over the past month. That pullback comes after a strong run, including a 90 day share price return of 14.0% and a 1 year total shareholder return of 24.6%. This suggests momentum has been positive even as recent moves hint at investors reassessing risk and future expectations around the current US$209.66 level.
Compare Penske Automotive Group's recent run with a hand picked group of companies showing strong price momentum and fundamentals using the 16 high quality undiscovered gems.
Penske Automotive Group has cooled off after a strong run, which leaves a practical choice for investors: lean into the current price, or wait and hope for a cleaner entry that valuation can justify next.
Most Popular Narrative: 1% Undervalued
The most followed narrative pegs Penske Automotive Group's fair value at $211.25, very close to the last close at $209.66. This frames the current debate less around a big discount and more around how durable its cash generation and earnings quality really are.
Record growth in service and parts revenue (+7%) and gross profit (+9%) is being driven by the aging vehicle fleet (average age now over 6 years), increased vehicle complexity, and higher warranty and customer-pay work. This creates durable, recurring revenue streams and supports expanding net margins as the average vehicle age rises in both the U.S. and Europe.
See why 5 investors see Penske Automotive Group as 1% undervalued.
Result: Fair Value of $211.25 (ABOUT RIGHT)
Still, Penske Automotive Group faces meaningful risks if premium and luxury demand weakens, or if EV shifts and direct sales models reduce dealership profitability more quickly than analysts expect.
Find out about the key risks to this Penske Automotive Group narrative.
Another View On Penske Automotive Group's Valuation
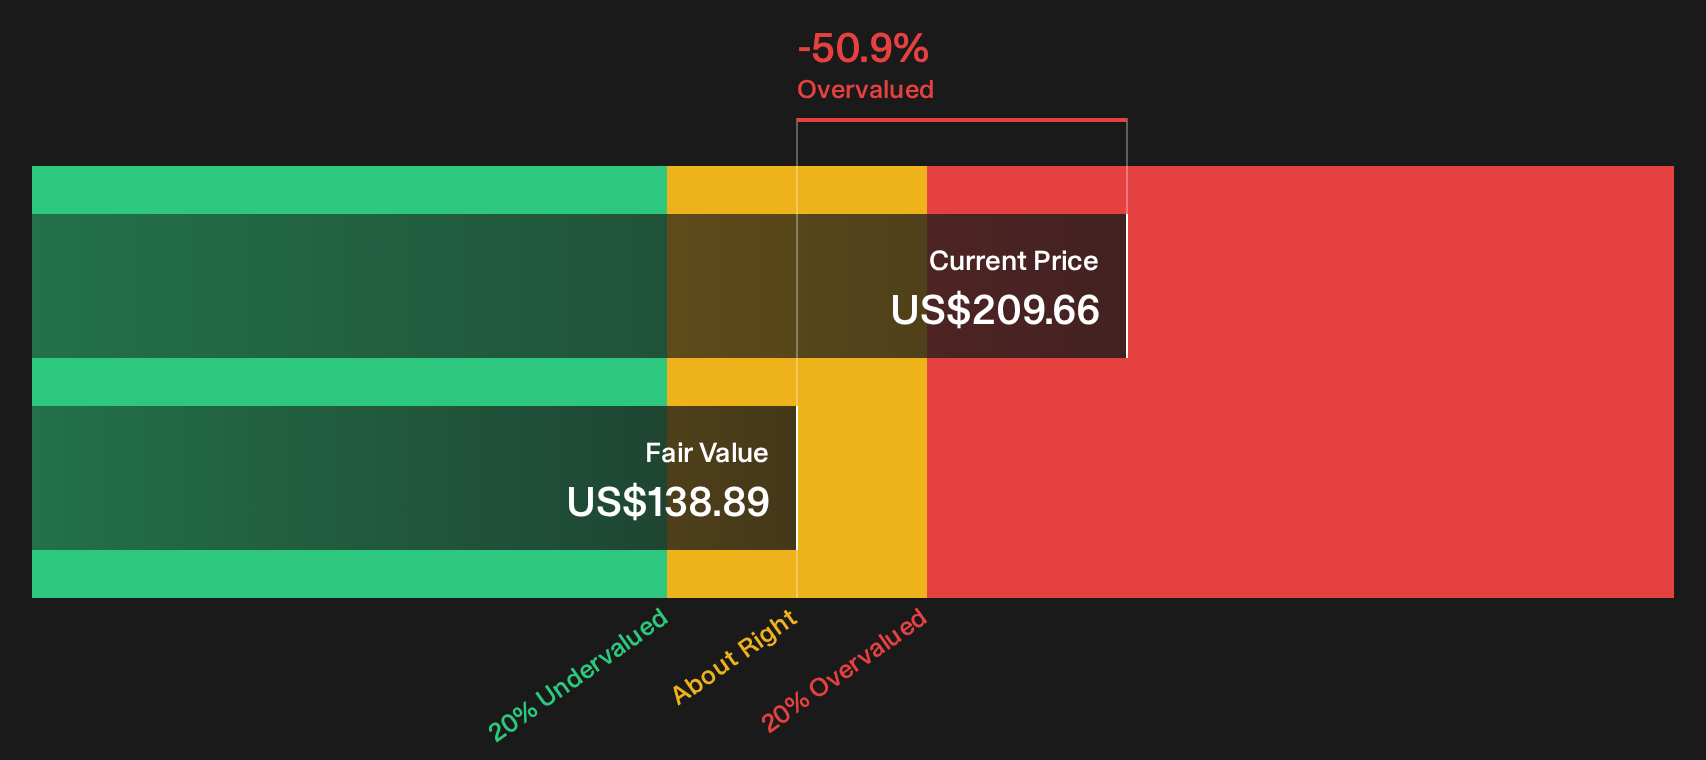
Analyst work around Penske Automotive Group leans on detailed earnings forecasts and a target price near $211, yet the SWS DCF model paints a different picture by putting future cash flow value closer to $138.89, which points to the shares trading at a premium instead of a discount.
For any investor weighing those two signals, the real question is which set of assumptions feels closer to how Penske Automotive Group can actually perform over the next few years, and where that leaves your own margin of safety.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Penske Automotive Group can create hesitation, yet the only view that matters is your own. Move quickly, review the full mix of risk and reward data, and weigh the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Penske Automotive Group?
Do not stop with Penske Automotive Group. Use the Simply Wall St screener to hunt for fresh opportunities, compare quality, and pressure test your next move.
- Target resilient opportunities that balance upside with capital preservation by scanning a curated set of 31 resilient stocks with low risk scores.
- Zero in on compelling value by filtering for companies that look mispriced on quality and fundamentals with the 30 high quality undervalued stocks.
- Build a watchlist of potential future winners before they become widely followed by checking out the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com