
Afya (AFYA) Stock Could Be Undervalued Despite Its 26% Five Year Slump
Afya has seen its share price under pressure in recent years, and a pending merger with Brazilian education group Yduqs has put an even brighter spotlight on whether the current valuation is properly grounded in the business's earnings power. With the stock drifting lower again this year, investors are asking how much of Afya's profit profile is already reflected in the price.
- Afya's share price has fallen 25.6% over the past 5 years. This raises the question of whether the earnings outlook has weakened enough to justify that kind of long run reset.
- The agreed merger into Yduqs may reshape how Afya's medical education earnings are shared and reinvested. This can influence what multiple the market is willing to pay for those profits.
- There is a second opinion on Afya worth weighing. See what analysts think Afya's shares could be worth.
The issue now is whether Afya's current share price is appropriately aligned with the earnings it generates today and what the market expects those earnings to look like over time.
To sense check whether Afya's earnings-driven valuation still stacks up, it helps to compare it with other companies screened for 30 high quality undervalued stocks
Does Afya Look Undervalued on Earnings?
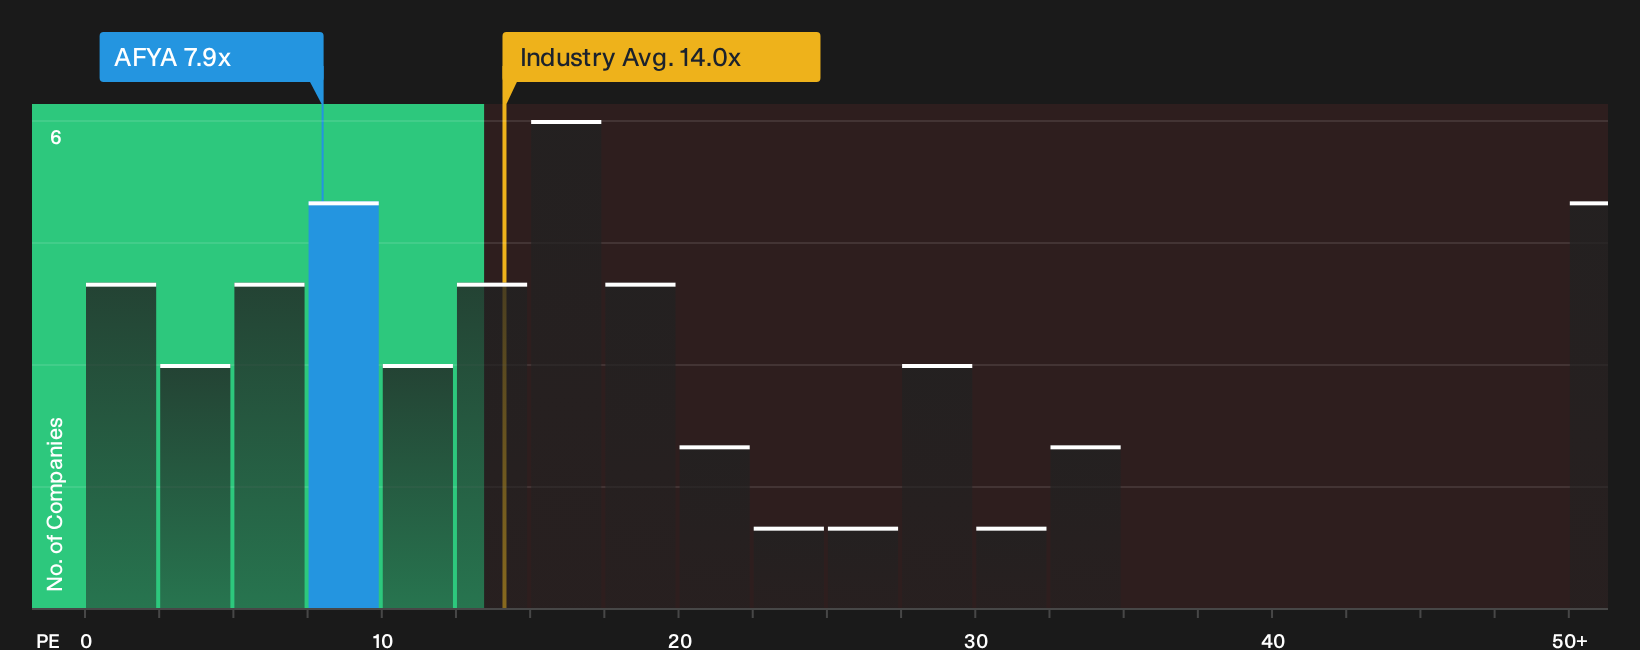
The P/E ratio is a useful lens for Afya because earnings remain a central reference point for how investors frame its value. On this measure, Afya trades on roughly 7.9x earnings, which is meaningfully lower than the Consumer Services sector average of about 14.0x and well below the peer group average near 22.6x. For a reader, that gap signals that the market is currently paying less for each dollar of Afya’s profit than it does for many comparable education and service companies.
Because the Fair Ratio framework blends factors such as profitability, risk and size into a customised yardstick, the model points to Afya screening as undervalued on this earnings multiple. Despite the pending merger into Yduqs, which is concentrating trading in Brazil and adding deal uncertainty, the current P/E still leaves Afya priced at a discount to both its sector and peer benchmarks. This suggests the market is assigning a cautious tag to its earnings stream. Explore the numbers behind Afya's P/E valuation.
The Afya Narrative: What Would Justify Today's Price?
Afya’s valuation puzzle sets up a natural next step for readers who want to spell out what would need to happen for the current P/E discount to close or widen. Simply Wall St Narratives on Afya turn that question into specific future paths for earnings, margins and growth that could justify a higher or lower share price, and each links its number to a clear view of how growth, profitability and risk might evolve as new information arrives.
One of the top community narratives on Afya: 7% undervalued
"This narrative explores a more pessimistic perspective on Afya compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts…"
Discover why this Narrative puts Afya at 7% undervalued.
One more Afya check that sits beside the earnings multiple
Price ratios only tell part of Afya's story, because the people choosing where to deploy cash and how to share the rewards can tilt the risk and return profile in ways the P/E alone cannot. See who runs Afya and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com