
How Analyst Downgrade At Cisco Systems (CSCO) Has Changed Its Investment Story
- Cisco Systems recently introduced Splunk AI capabilities for on premises customers through Cisco AI POD for Splunk, expanded observability tools, and new agent driven security features, while also partnering with Infleqtion on research to connect and scale distributed quantum systems.
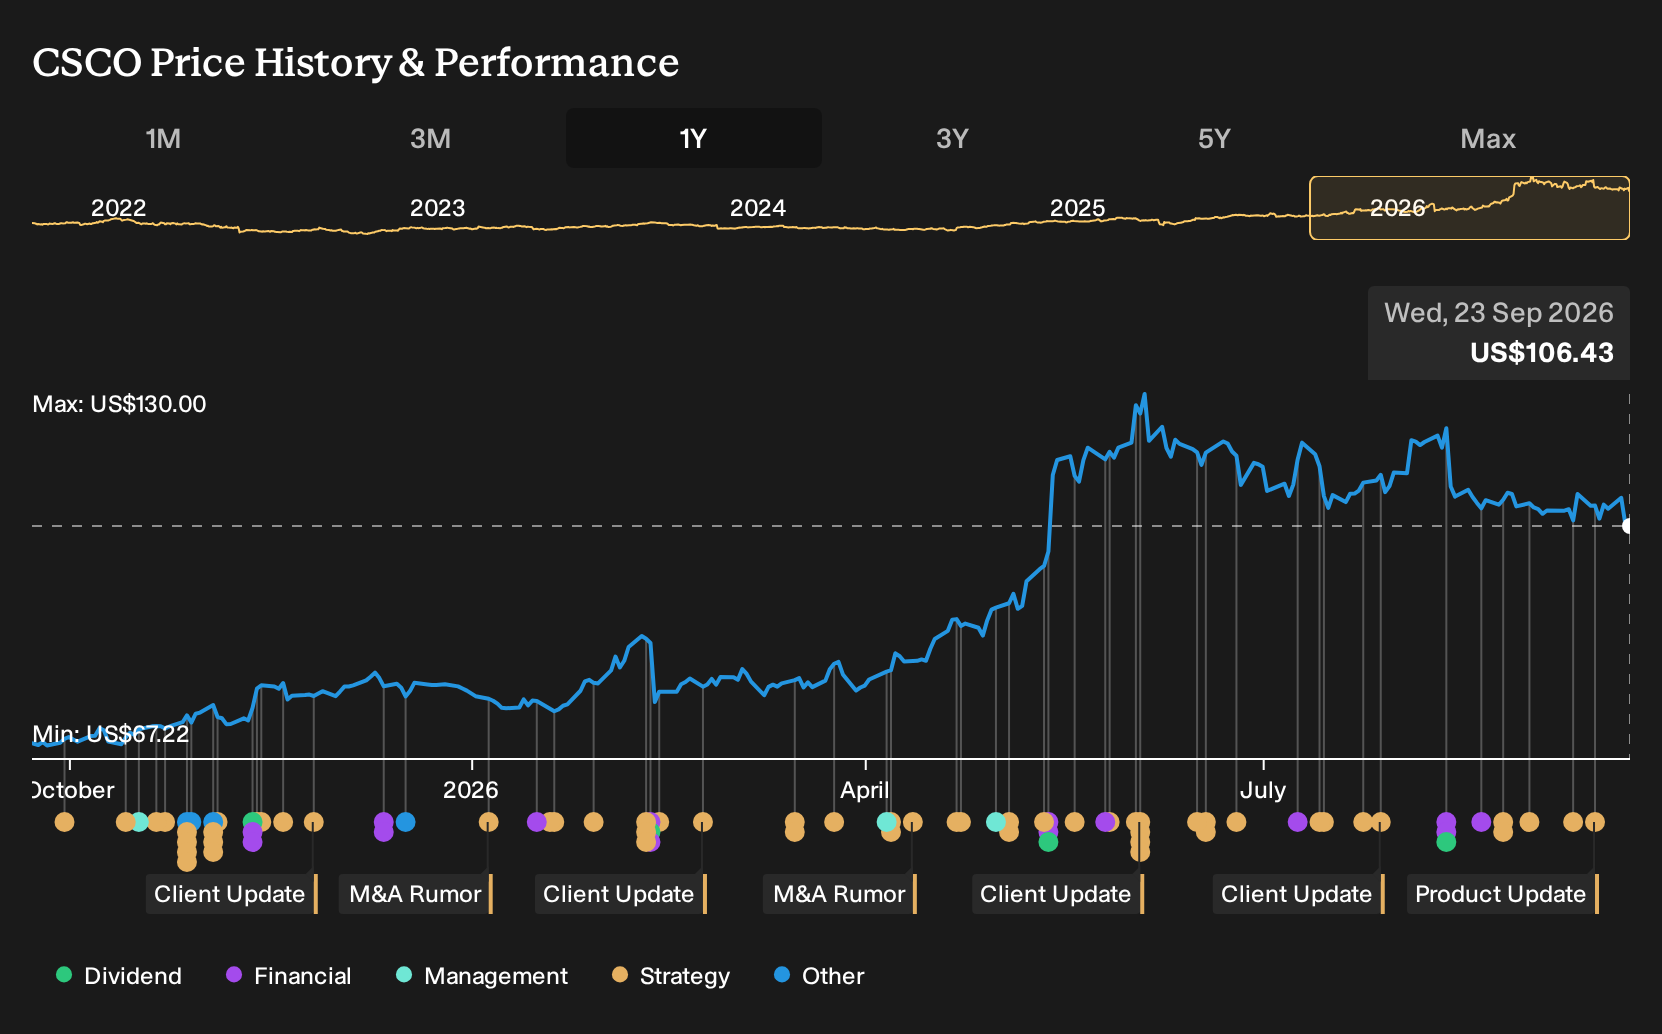
- These moves push Cisco Systems deeper into AI centric networking, observability, and early stage quantum networking research at the same time that one major broker expressed concern about the durability of its growth profile and competitive position.
- We will now assess how Cisco Systems' push into AI powered observability and security operations could influence its broader investment narrative.
Scan how Cisco Systems' AI push compares with other infrastructure and security plays by reviewing a curated set of 85 AI infrastructure stocks poised around similar data center and observability themes.
Cisco Systems Investment Narrative Recap
To hold Cisco Systems today, you need to believe the AI infrastructure cycle, security spending, and network refresh tailwinds are strong enough to offset near term pressure on gross margin from a heavier hardware mix and higher memory costs. The Splunk AI rollout and Secure AI Factory framing keep the focus firmly on AI led networking and security rather than legacy routing alone.
The most important short term catalyst remains how quickly hyperscale AI orders and broader enterprise demand turn into revenue without eroding operating margin. The biggest near term risk is that costs tied to AI hardware and secure infrastructure outpace pricing power, which would blunt the earnings impact of this product momentum.
Among the recent announcements, Cisco AI POD for Splunk looks closest to the heart of the story. It wraps Cisco infrastructure, NVIDIA accelerated computing, and Kubernetes into a pre validated stack for self managed Splunk AI across on premises, private cloud, and air gapped environments, which matters for customers that keep sensitive data in house.
Operationally, this extends Cisco Systems deeper into observability, AI cost tracking, and agentic SOC workflows while tying AI workloads to its own hardware and software portfolio. Execution risk sits in proving that tools like Splunk Agent Observability and Tokenomics actually help customers control AI spend and trust automated security, because that outcome shapes how durable this AI centric narrative becomes.
Cisco Systems AI Story Through The Numbers
Cisco Systems' narrative projects US$83.4b revenue and US$20.1b earnings by 2029. Analysts are assuming 9.6% yearly revenue growth and an earnings increase of about US$6.8b from US$13.3b today.
Uncover why Cisco Systems' fair value indicates a 29% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate narrative leans hard into Cisco Systems as an upside story, focusing on hyperscale AI demand and security rather than margin strain. The most optimistic analysts were penciling in revenue of about US$90.6b and earnings near US$23.0b by 2029, before this Splunk and quantum news, so their views could shift further as AI and observability products evolve.
Explore 5 other Cisco Systems fair value estimates, including one that suggests as much as 29% potential increase from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cisco Systems research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Cisco Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cisco Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cisco Systems?
Cisco Systems may be central to your watchlist right now, but you can spread your research across other sectors and balance different types of risk and income profiles using the Simply Wall St Screener.
- For investors hunting for potential mispricings, scan a curated 30 high quality undervalued stocks that pair strong fundamentals with what may be more modest expectations baked into current prices.
- If stability matters more than excitement, filter for 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength to help smooth out portfolio volatility.
- When you want to get ahead of the crowd, track a focused 16 high quality undiscovered gems that combines quality metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com