
New Pump Launch Might Change The Case For Investing In SKF Stock
- AB SKF recently launched its Progressive Lubrication Pump, an automatic system aimed at improving machine reliability, cutting manual servicing, and simplifying installation for both industrial and mobile equipment users.
- The PLP range is the first built on SKF's new lubrication platform, signaling a push toward modular, connected solutions that can support automation and long-term maintenance contracts.
- We will now explore how AB SKF's investment narrative could be affected by launching a modular, connectivity ready Progressive Lubrication Pump.
Scan beyond AB SKF and see how other automation focused industrials are positioned by reviewing our curated list of 93 robotics and automation stocks.
AB SKF Investment Narrative Recap
To buy into AB SKF as a shareholder, you need to believe the industrial side can keep compounding value through automation, digital services, and more reliable equipment for customers. That story leans heavily on areas like smart bearings, condition monitoring, and now more advanced lubrication. The new Progressive Lubrication Pump fits that direction but does not suddenly change the investment case on its own.
The more immediate swing factor is execution on margin improvement while separating the weaker automotive activities and absorbing restructuring costs. FX headwinds, softer automotive demand, and uneven regional orders still sit on the risk side. PLP can support the industrial narrative, yet the key near term test remains consistent profitability progress rather than a single product launch.
The PLP launch ties closest to SKF's push into automation and digitalization of maintenance. Automatic lubrication is designed to cut manual work, reduce unplanned downtime, and give better data on machine health. That links directly to the aim of raising the share of higher margin services and solutions over time and stabilising earnings.
For catalysts, this kind of modular, connectivity ready platform gives SKF more ways to bundle bearings, sensors, and service contracts with industrial clients. Execution still matters. Management needs to show that products like PLP translate into stronger industrial segment profitability while the group manages automotive separation risk, FX pressure, and the cash cost of restructuring.
AB SKF's narrative projects SEK 96.2b revenue and SEK 9.4b earnings by 2029. This implies 2.4% yearly revenue growth and an earnings increase of SEK 4.9b from SEK 4.5b today.
Uncover why AB SKF's fair value indicates it is in line with its current price.
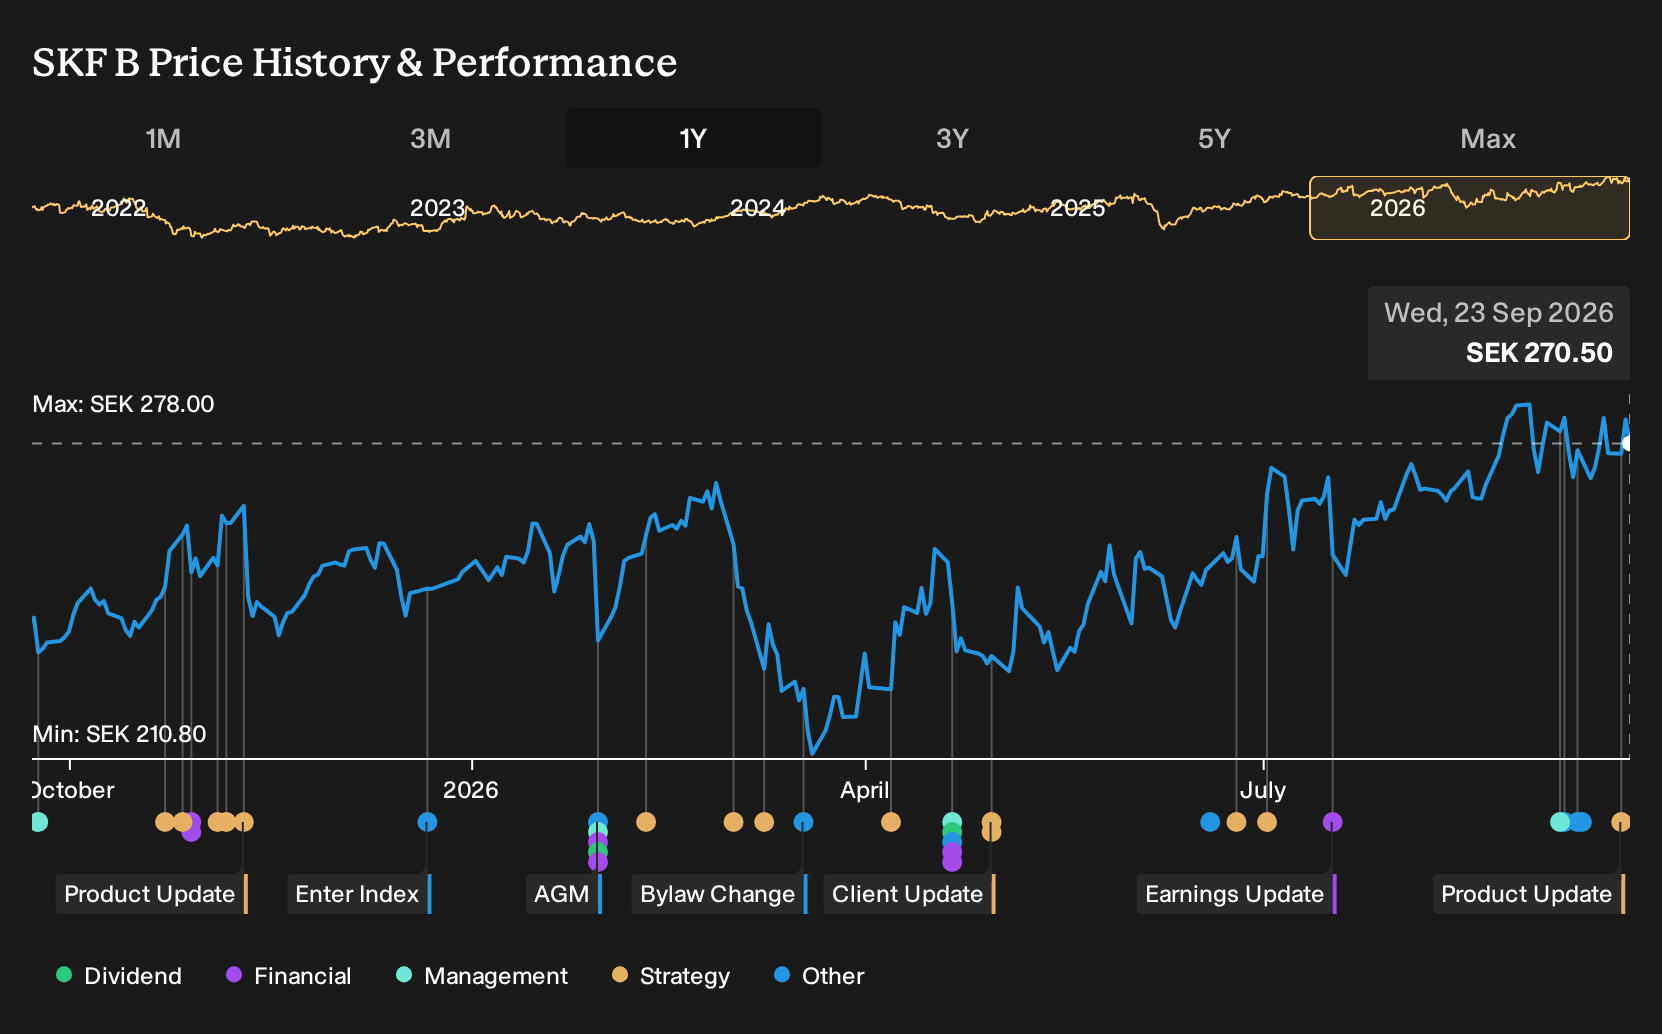
Exploring Other Perspectives
Some of the lowest AB SKF analysts focus on revenue risk rather than automation upside. They were pencilling in SEK 76.1b of sales and SEK 8.7b of earnings for 2029 before this PLP news, which is far more cautious than consensus. Use that gap as a prompt to compare several narratives for yourself.
Explore 2 other AB SKF fair value estimates, including one that suggests it could be worth just SEK266.06.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis and instincts.
- A great starting point for your AB SKF research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AB SKF. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AB SKF's overall financial health at a glance.
Looking For More AB SKF Investment Ideas?
If the AB SKF story has sharpened your thinking about automation, reliability, and long term returns, it can be useful to stress test that framework against other opportunities. The Simply Wall St Screener lets you filter for different types of businesses so you can compare quality, risk, and income potential side by side.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (199 results) that can help you focus on companies with stronger fundamentals.
- If you are hunting for quality at a potentially attractive price, sort through a 174 high quality undervalued stocks and see which businesses might line up with your return and risk expectations.
- Income focused investors can zero in on steady cash returns by reviewing a 157 dividend fortresses that prioritises companies with higher yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com