
CGI Partnership Might Change The Case For Investing In D Wave Quantum (QBTS)
- CGI Inc. announced a partnership with D-Wave Quantum to integrate D-Wave's Advantage2 system and hybrid solvers into CGI's services, targeting complex optimization problems in logistics, transportation and retail.
- The focus on co-developing quantum-enabled rail and retail workflows signals that D-Wave Quantum is increasingly embedded in real operational planning rather than isolated proofs of concept.
- We will now assess how D-Wave Quantum's investment narrative could shift as CGI begins integrating its quantum systems into client workflows.
D-Wave Quantum Investment Narrative Recap
To own D-Wave Quantum, you need to believe that quantum optimization moves from experiments to repeat, real world workflows and that this shift eventually supports a larger, steadier QCaaS base. The CGI partnership points in that direction, but the most important near term catalyst is still clear evidence of customers scaling from pilots to multi application, multi year usage.
The biggest near term risk hardly changes. Revenue still leans on a few large, lumpy contracts, while the business remains loss making with widening historical losses. If spending on R&D and go to market fails to convert into more repeatable deals, the path to a more self sustaining model stays uncertain despite the CGI news.
The CGI agreement is the announcement that fits this story best. It directly targets some of D-Wave Quantum core use cases, including logistics, rail operations and retail planning. That matters because the long term thesis depends on quantum optimization becoming embedded in high value, operational workflows rather than remaining isolated proofs of concept.
For catalysts, the CGI relationship gives D-Wave Quantum a route into clients that already buy complex IT and analytics services. It may help address the risk that many customers remain stuck at small, experimental deals. Execution still has to deliver real deployments and measurable outcomes at scale; otherwise, the partnership stays more marketing than inflection point.
D-Wave Quantum's narrative projects US$201.1 million revenue and US$23.0 million earnings by 2029. This projection assumes revenue growth of 152.9% per year and an earnings improvement of about US$271.7 million from a loss of US$248.7 million today.
Uncover why D-Wave Quantum's fair value indicates a 110% potential upside to its current price that could narrow quickly.
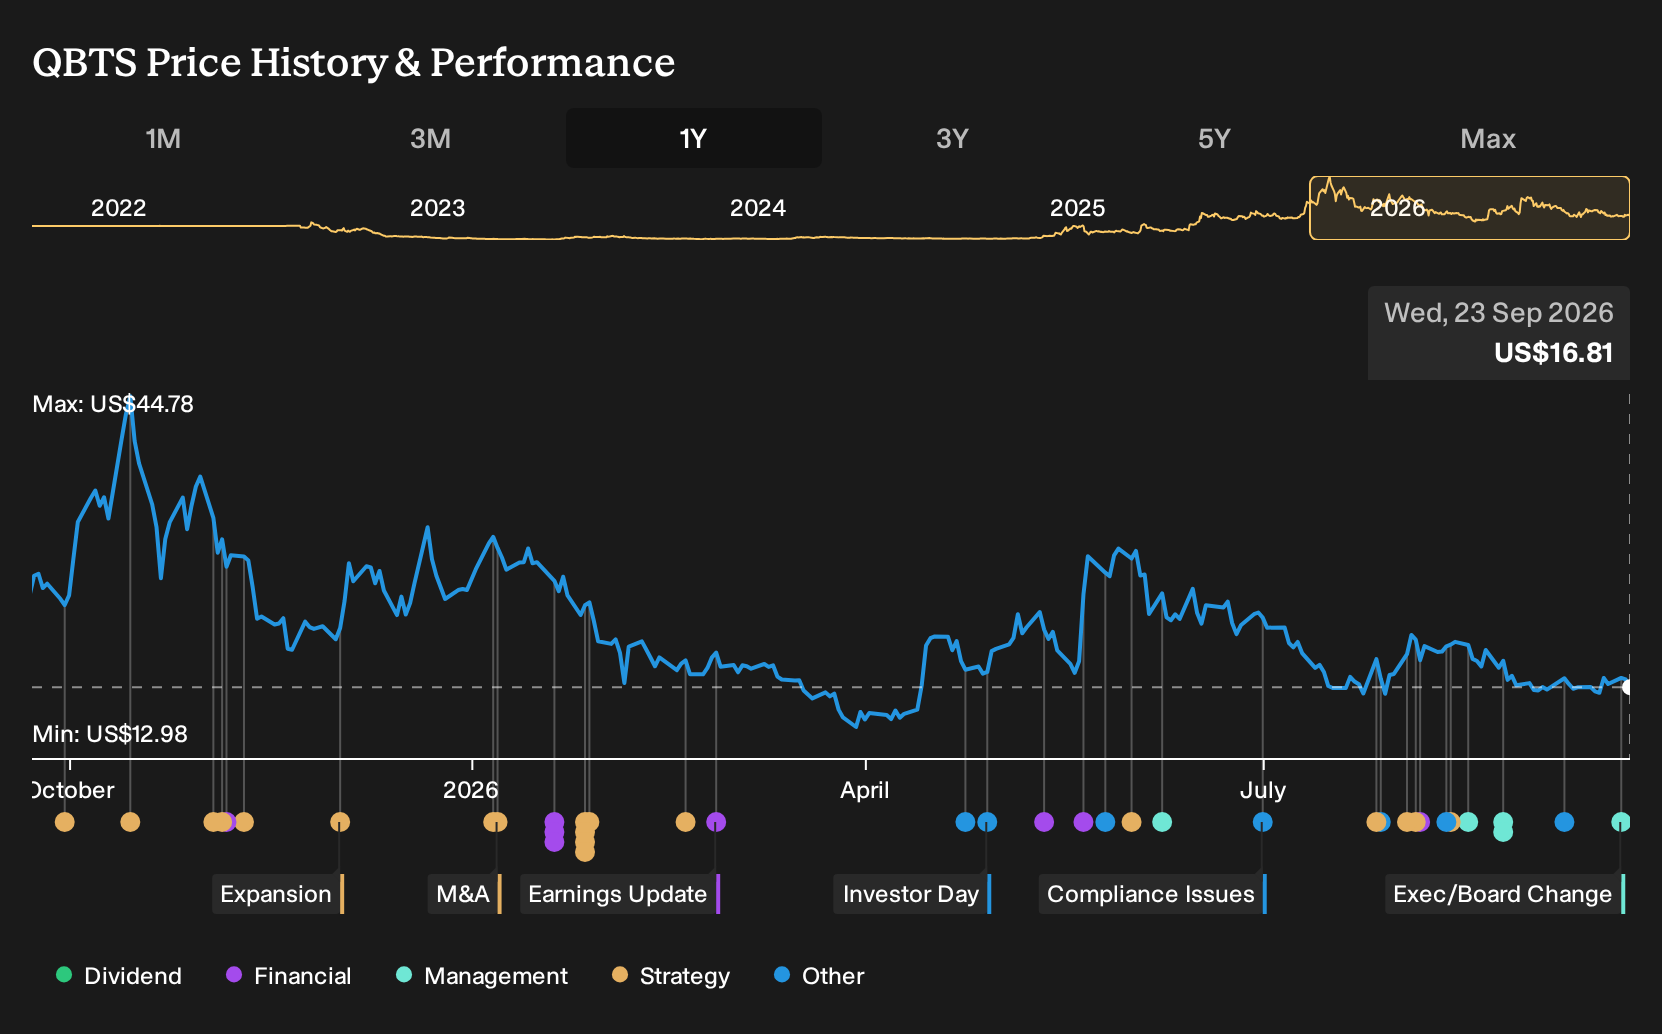
Exploring Other Perspectives
One alternate read on D-Wave Quantum focuses on execution risk rather than new contracts. The most pessimistic analysts were already cautious even while consensus talked about US$201.1 million of revenue and US$23.0 million of earnings by 2029. With the CGI deal now public, those views may shift, so treat this as a prompt to compare several angles yourself.
Explore 9 other D-Wave Quantum fair value estimates, including one that suggests as much as 686% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your D-Wave Quantum research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for D-Wave Quantum. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate D-Wave Quantum's overall financial health at a glance.
Looking for more investment ideas beyond D-Wave Quantum?
If the D-Wave Quantum story has you thinking about where quantum, software and infrastructure might intersect next, it can help to scan a broader watchlist built around clear financial traits instead of headlines alone.
- If you want businesses that combine income potential with resilience, review a focused set of 7 dividend fortresses that concentrate yield and balance sheet strength.
- For investors who care most about downside protection, start with companies that score well on stability and financial robustness using a 31 resilient stocks with low risk scores as your hunting ground.
- Readers looking for future compounders with solid fundamentals but limited attention from the market can cast a wider net across 16 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com