
Is Woolworths Group (ASX:WOW) Fairly Valued After Its Supply Chain Upgrade Story?
Woolworths Group (ASX:WOW) is back in focus after investors revisited the supermarket operator’s core Australian and New Zealand retail operations, prompting fresh questions about valuation, income potential and the stock’s recent share price performance.
Recent trading has been choppy for Woolworths Group, with the share price at A$38.27 after a 1-day share price return of 0.71% and a year-to-date share price return of 30.04%. The 1-year total shareholder return of 46.45% hints at momentum that investors are still willing to reward despite softer 90-day share price performance.
Scan Woolworths Group alongside a curated 7 resilient stocks with low risk scores that could appeal to investors who care about resilience as much as recent share price momentum.
After a 46.45% total return over the past year and a market value of about A$46.3b, Woolworths Group now poses a simple question for new investors: Is the current price still offering enough upside for the risk involved?
Most Popular Narrative: 2% Undervalued
On the most followed valuation view, Woolworths Group is trading slightly below an estimated fair value of about A$39.20, compared with the current A$38.27 share price. This puts more focus on how its operations might support that gap.
The ongoing investment and upgrades in Woolworths' supply chain automation and distribution centers are expected to drive significant operational efficiencies and margin improvement over the next few years, as dual running and commissioning costs roll off and new facilities like Moorebank and Auburn CFCs deliver returns, likely supporting higher future EBIT and ROIC.
See why 82 investors see Woolworths Group as 2% undervalued.
Result: Fair Value of A$39.20 (UNDERVALUED)
Still, the Woolworths Group story can slip if higher labor costs are more significant than expected or if weaker BIG W performance continues to drag on group margins.
Find out about the key risks to this Woolworths Group narrative.
Another View On Woolworths Group Valuation
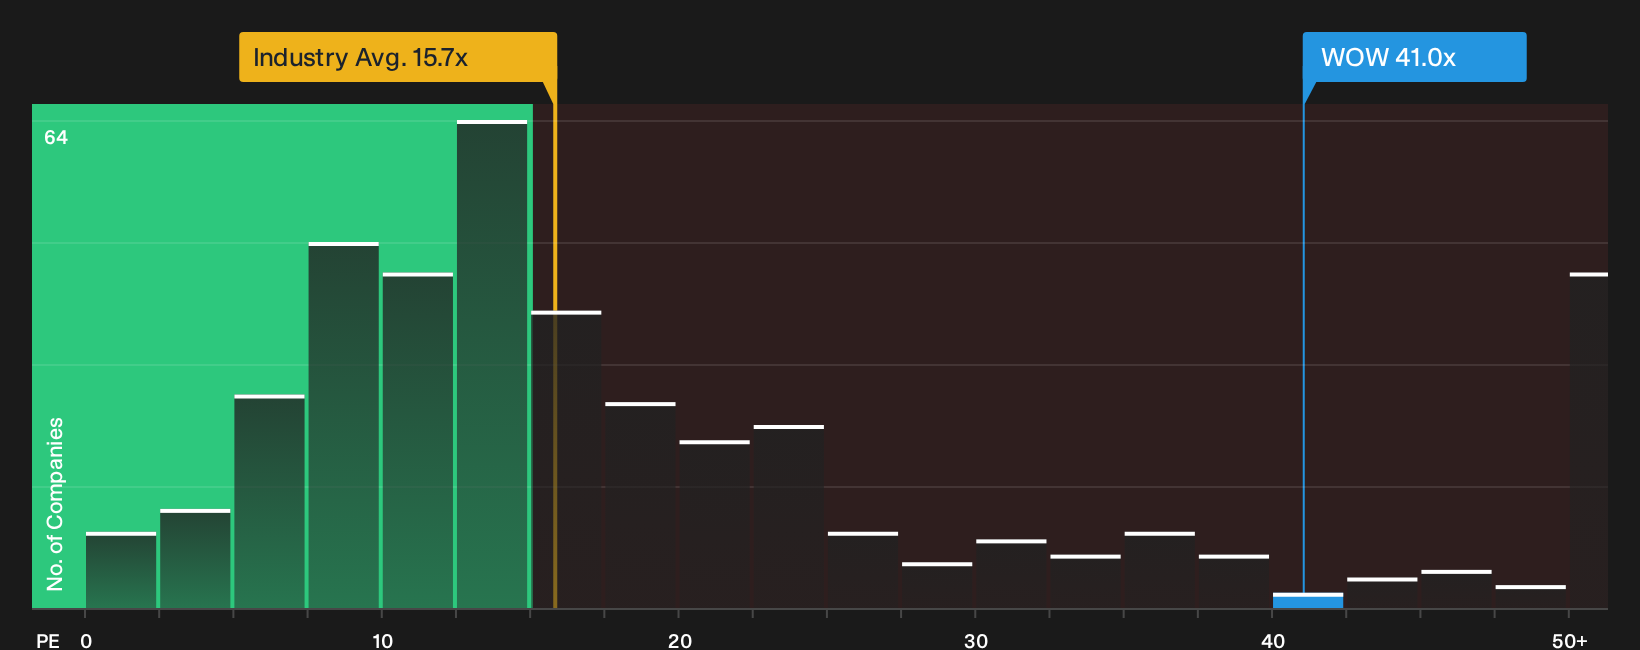
Look past the A$39.20 fair value and a different picture appears. On simple P/E math, Woolworths Group trades on about 41x earnings, compared with an estimated fair ratio of 29.6x and a global Consumer Retailing average of 15.7x. That is a rich premium. Is the quality premium big enough for you?
To weigh up that pricing gap in more detail, take a closer look at how the earnings multiple stacks up against peers and the fair ratio, and what that might mean for future returns via the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Woolworths Group can make the story feel finely balanced. Move fast, test the data yourself and pressure test both sides of the argument using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Woolworths Group?
If you stop with Woolworths Group, you risk missing other opportunities. Use the Simply Wall St screener to compare different businesses, themes and potential return profiles.
- Target potential mispricing by scanning a focused 6 high quality undervalued stocks that filters for quality companies trading below their estimated worth.
- Prioritise resilience by reviewing a carefully built list of solid balance sheet and fundamentals (12 results) so you can focus on businesses with stronger financial footing.
- Get ahead of the crowd by searching a curated 16 high quality undiscovered gems where fundamentals matter more than headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com