
Why WEX (WEX) Is Getting Attention Today
WEX (WEX) has rolled out cardless fuel payments through its CardControl app, allowing over-the-road drivers to generate single-use fueling codes that aim to reduce physical card fraud.
The new cardless fuel rollout lands at a time when WEX’s share price is US$184.54, with a 1-day share price return of 1.83% offering a brief lift after a 7-day share price decline of 6.41% and a 30-day share price drop of 9.21%.
Over a longer stretch, momentum has leaned more positive, with a 90-day share price return of 38.67% and a year-to-date share price gain of 24.36%. The 1-year total shareholder return of 14.32% and 5-year total shareholder return of 5.37% point to a mixed record for longer term holders.
Scan beyond WEX and compare this fraud-focused rollout with other payment and fintech players screened in our hand-picked 16 high quality undiscovered gems to see which platforms are building similar defenses into their models.
After a sharp run over 90 days and a recent pullback, WEX now sits in an awkward middle ground. Investors may wonder whether most of the easier upside is already behind the stock or if the valuation still suggests room ahead.
Most Popular Narrative: 5% Undervalued
Against WEX’s last close of $184.54, the most followed narrative points to a fair value of about $193.91 using an 8.61% discount rate, which frames the stock as modestly undervalued on that set of long term cash flow assumptions.
Product and geographic diversification highlighted by continued growth outside North America, a surging pipeline of non-travel AP/embedded payment customers, and the launch of new funding/multi-currency capabilities broadens WEX's total addressable market and creates multiple vectors for long-term revenue growth and reduced earnings volatility as digital commerce and global e-payments proliferate.
See why 8 investors see WEX as 5% undervalued.
Result: Fair Value of $193.91 (UNDERVALUED)
Still, the reliance on traditional fuel card activity and the pressure from larger payment platforms mean WEX’s growth narrative could look very different if either factor moves against it.
Find out about the key risks to this WEX narrative.
Another View On WEX Valuation
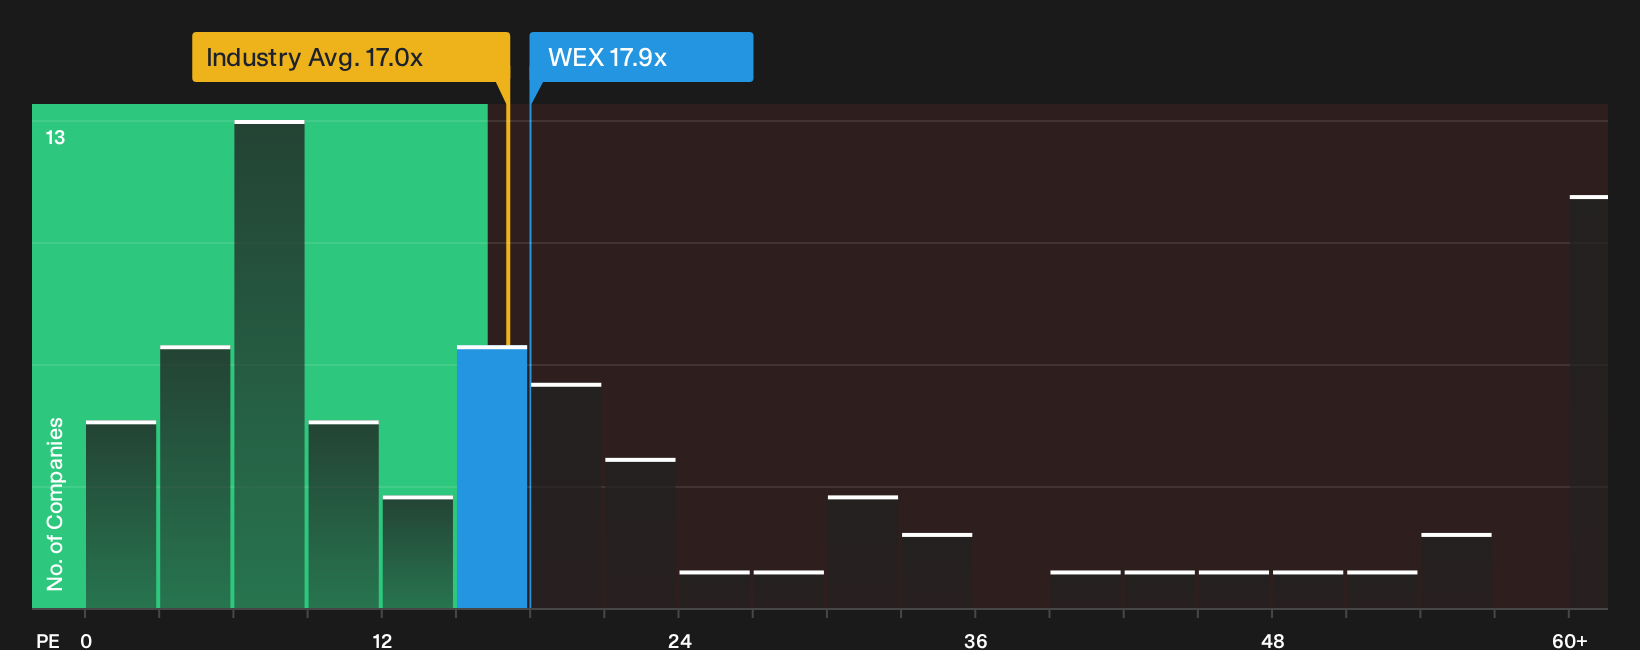
The first narrative paints WEX as modestly undervalued on future cash flows, yet the market is pricing the shares at a P/E of 17.9x. That is higher than the US Diversified Financial industry at 17.1x, the peer group at 16.6x, and the fair ratio estimate of 14.7x. This points to a richer tag on current earnings and raises the question of whether investors are already paying up for much of the good news.
For a closer look at how that price tag compares and where the ratio could drift over time, take a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around WEX can be unsettling. Move quickly, review the underlying numbers and commentary, and then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WEX?
Do not stop your research at WEX when some of the most interesting opportunities often sit just outside the headlines on thoughtful stock shortlists.
- Strengthen your search for value by scanning a focused set of underappreciated quality companies through the 30 high quality undervalued stocks.
- Build a sturdier portfolio core by reviewing companies screened for strong balance sheets and fundamentals in the list of solid balance sheet and fundamentals (23 results).
- Explore targeted growth potential by checking a curated group of lesser known opportunities using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com