
Bangkok Hotel Debut Could Be A Big Deal For EVT Stock (ASX:EVT)
- EVT is expanding its LyLo lifestyle budget hotel brand beyond Australia and New Zealand, with a 387 bed property in Bangkok planned to open in 2028 under a management agreement, supported by a new Bangkok office for South East Asia operations.
- The Bangkok launch underscores EVT's push to grow LyLo through an asset light model, which keeps real estate off the balance sheet while still building fee based income from managed properties.
- This development raises questions about how EVT's investment narrative could be influenced by LyLo's Bangkok expansion and new regional office footprint.
What Is EVT's Investment Narrative?
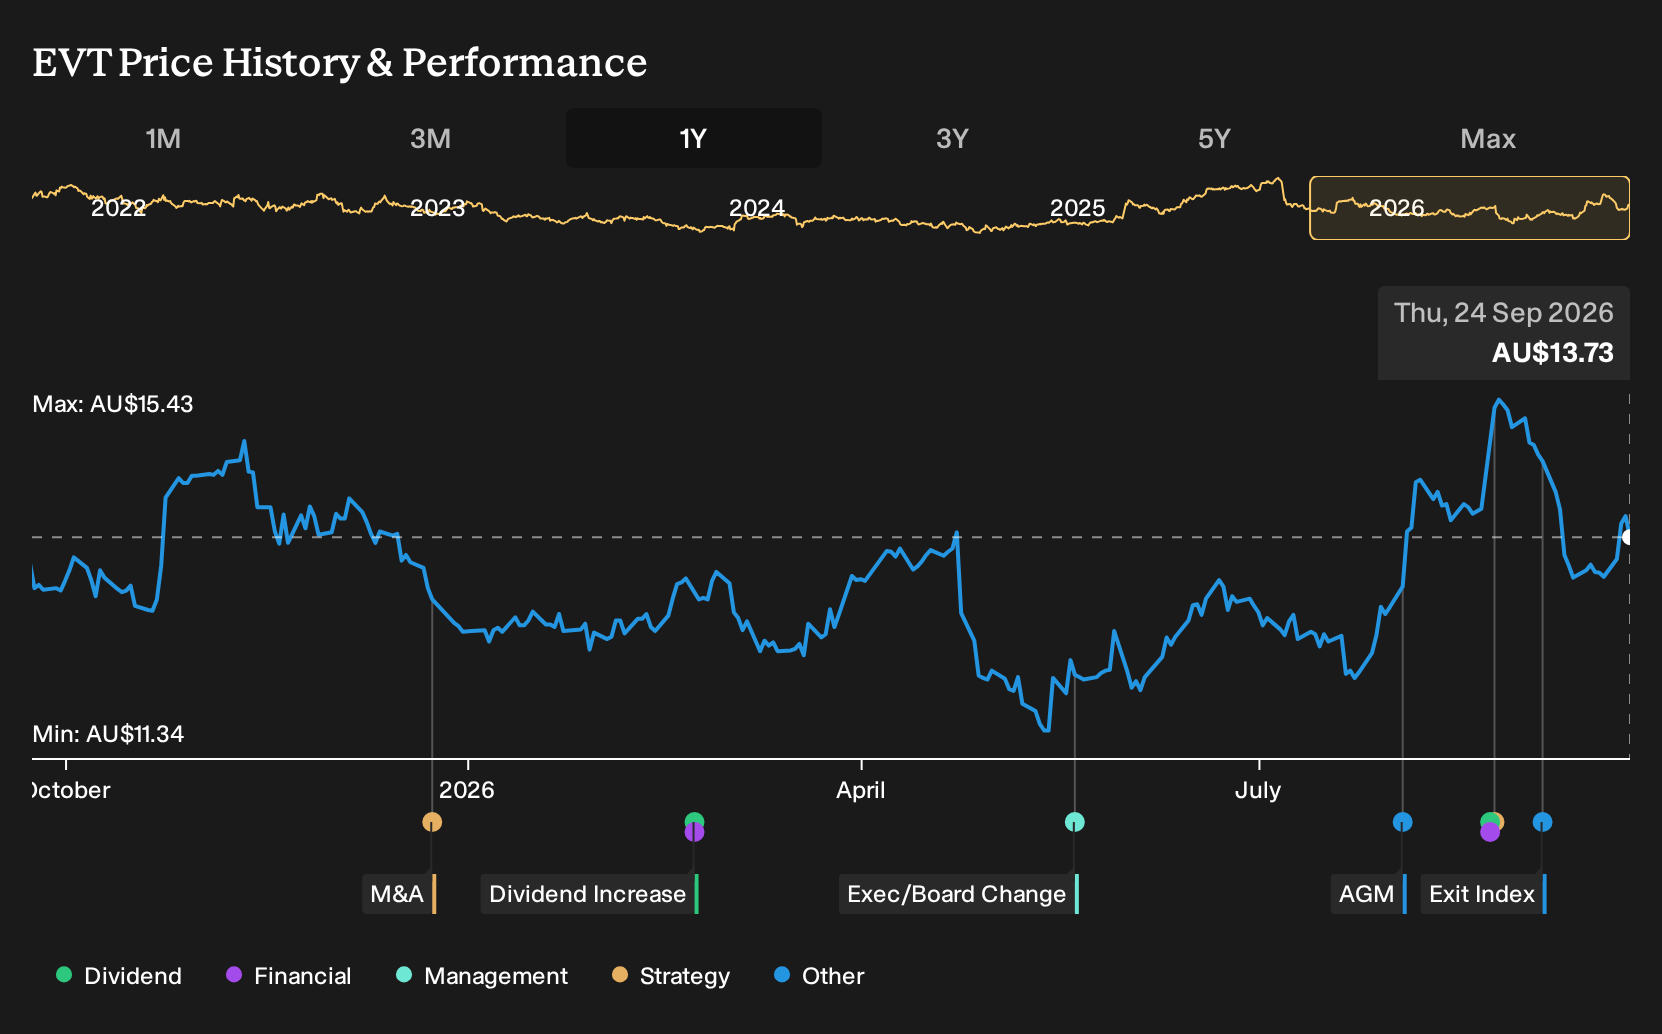
Owning EVT is really a bet that its mix of cinemas, hotels, resorts and property can keep turning solid operating execution into growing earnings, without stretching the balance sheet too far. The LyLo Bangkok move fits that story. A management agreement keeps capital intensity lower, while still adding potential fee income and scale to the Hotels division, which already generates A$434.5m of revenue out of A$1.31b across the group.
In the short term, the Bangkok project is too far out and asset light to change near catalysts around trading conditions, debt costs and how comfortably EVT covers interest and its 2.99% dividend. The bigger swing factor is whether management can sustain earnings growth, given the stock trades on a 44x P/E versus lower peer and industry multiples.
That said, the risk profile looks different once you weigh that elevated valuation against EVT's interest cover and ...
There's only one way to know the right time to buy, sell or hold EVT. Head to Simply Wall St's company report for the latest analysis of EVT's Fair Value.
Exploring Other Perspectives
For EVT, the big swing in the alternate, more optimistic narrative is earnings power. The most bullish analysts were modelling revenue of about A$1.5b and earnings of A$120.1m by 2029, versus A$40.1m today. That is a huge jump. These forecasts pre date the LyLo Bangkok news, so views may shift as fresh information lands.
Explore another EVT fair value estimate, including one that suggests it could be worth as much as A$9.82!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your EVT research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for EVT. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate EVT's overall financial health at a glance.
Looking For More EVT Style Investment Ideas?
If EVT's asset light push has you thinking about where else this kind of story might be taking shape, it makes sense to widen the lens and look across the market using the Simply Wall St Screener before making any portfolio moves.
- For investors who care most about valuation support and resilient fundamentals, start by scanning a 6 high quality undervalued stocks that already combine quality metrics with attractive pricing.
- If portfolio resilience and steadier risk scores matter more than headline excitement, narrow your search to a 7 resilient stocks with low risk scores that may better fit a capital preservation mindset.
- When you want to back stronger balance sheets without spending hours on footnotes, focus your research on a list of solid balance sheet and fundamentals (12 results) that already screen for financial strength and cleaner fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com