
Is New Qatar Service Center Altering The Investment Case For Emerson Electric (EMR)?
- Emerson Electric announced plans in 2026 to build a 3,500-square-meter Middle East & Africa Service Center in Qatar's Umm Alhoul Free Zone, adding the region's first certified in-country flow calibration lab and broad automation support for customers across Qatar, Saudi Arabia, the UAE and wider Africa.
- The new site concentrates advanced flow calibration, control system staging, training facilities and spare parts distribution in one hub. This could reshape Emerson Electric's cost profile and execution speed on complex projects for energy and industrial clients across the region.
- We will now examine how Emerson Electric's investment narrative could be influenced by the new Qatar automation service and calibration hub.
Emerson Electric Investment Narrative Recap
To own Emerson Electric, you need to believe the automation and industrial software story keeps pulling more work into its ecosystem, even if some end markets stay patchy. The Qatar service hub points in that direction. It tightens Emerson Electric's grip on high value service, software deployment and lifecycle work in a region that is investing heavily in energy and infrastructure.
The key near term swing factor remains execution on software, AI products and complex project delivery, while managing tariffs, FX and lumpy capital spending. The new center does not change those risks. It mainly reinforces the operational plumbing that could support order momentum if customers keep committing to large projects.
The Qatar Middle East & Africa Service Center announcement matters most because it lines up directly with Emerson Electric's automation and software catalyst. It clusters control systems staging, instrumentation, training and a flow calibration lab inside a single regional node. That structure can support more reliable deployments and potentially tighter project timelines when big power, LNG or chemicals projects move forward.
It also touches on several known pressure points in a practical way. Local calibration and spares can soften FX and tariff exposure on some hardware flows. A regional training and integration base can help with software adoption and reduce the risk of delays on complex control systems. Execution quality around this rollout will provide insight into how Emerson Electric handles its broader pure play automation ambitions.
Emerson Electric's current earnings sit at US$2.6b, with analysts expecting consensus earnings of US$3.8b by 2029. This implies an earnings increase of about US$1.2b and a projected revenue growth rate of 5.9% per year, tied to forecast revenue of US$22.1b and forecast earnings of US$3.8b in that same 2029 estimate year.
Discover why Emerson Electric's fair value indicates an 11% potential upside to its current price that could close sooner than you expect.
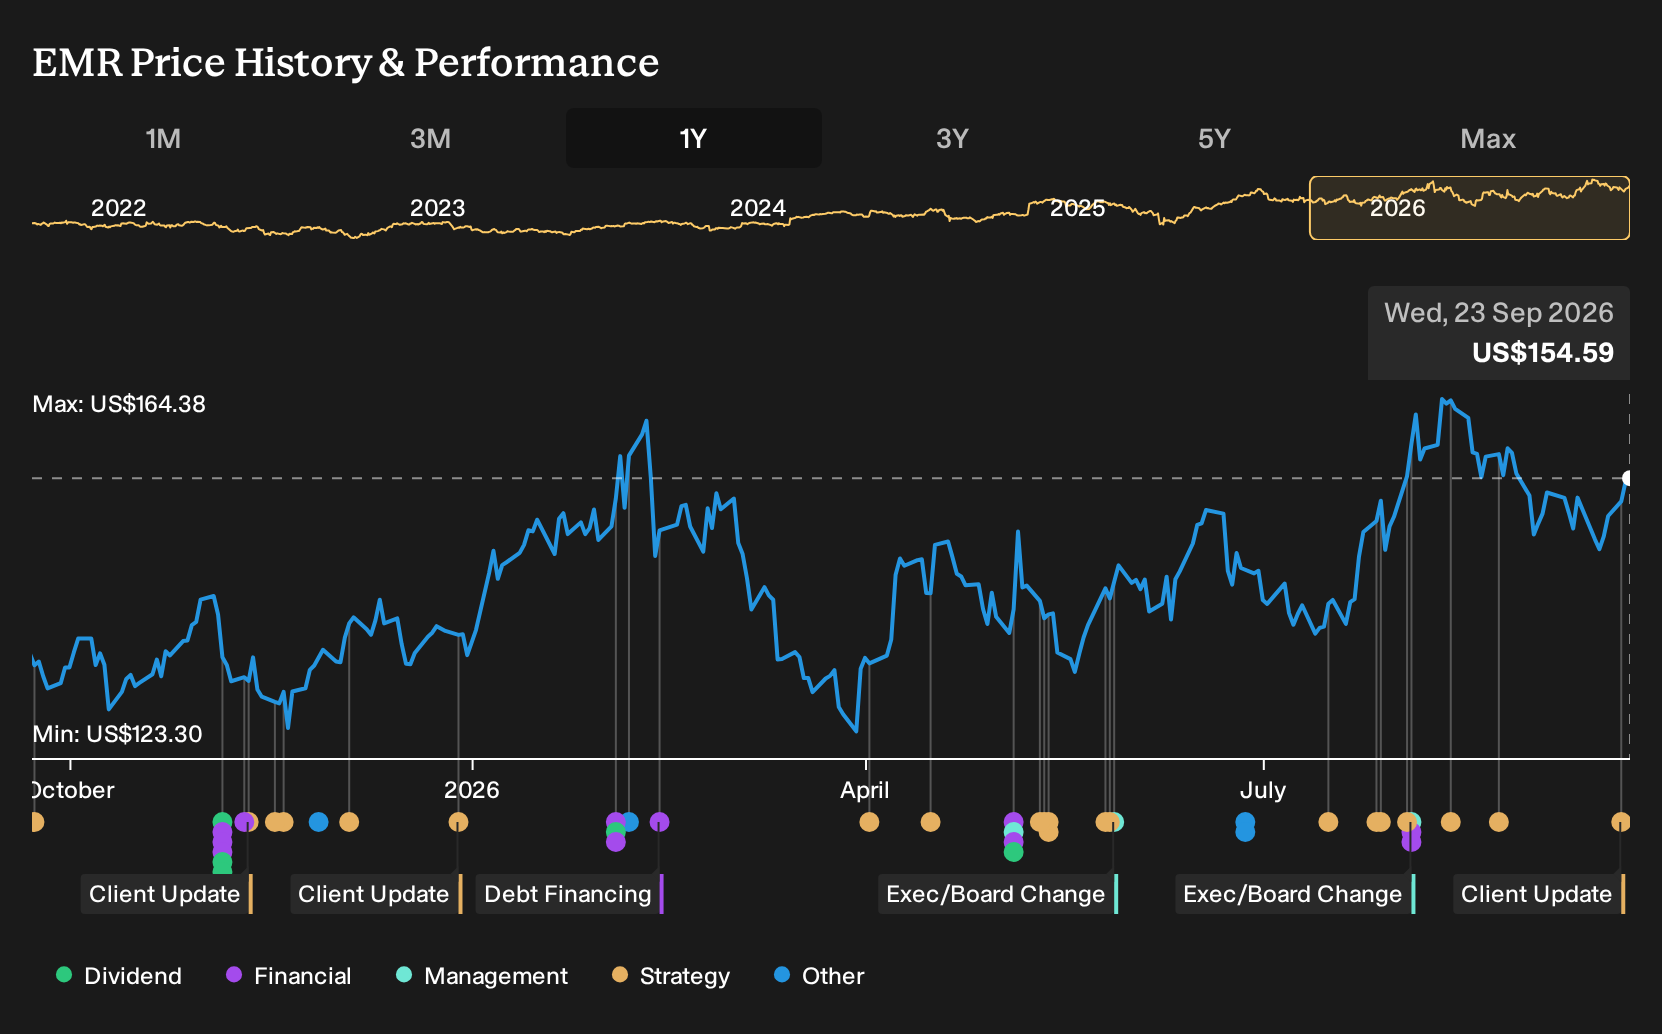
Exploring Other Perspectives
One optimistic twist on Emerson Electric focuses on faster AspenTech and AI traction. The most bullish analysts were already sketching out revenue of about US$22.4b and earnings near US$4.2b by 2029, well above the US$22.1b and US$3.8b consensus. This Qatar hub could nudge those narratives, in either direction, once forecasts refresh.
Explore 3 other Emerson Electric fair value estimates, including one that indicates there could be as much as 12% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Emerson Electric research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Emerson Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Emerson Electric's overall financial health at a glance.
Looking for more Emerson Electric style ideas?
If Emerson Electric's Qatar expansion has sharpened your interest in automation and industrial stories, it can help to widen the lens and scan other listed businesses with different strengths and risk profiles.
- For income focused investors who want yield with sturdier fundamentals, review companies in the 7 dividend fortresses that might complement a position in an industrial like Emerson Electric.
- If capital preservation and steadier balance sheets matter more to you than headline growth, filter opportunities through the 31 resilient stocks with low risk scores to see which businesses meet your risk tolerance.
- For investors hunting for underappreciated quality outside the usual crowd, scan the 16 high quality undiscovered gems and compare how those prospects stack up against Emerson Electric on fundamentals and valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com