
Backlog Decline Could Be A Key Test For Meritage Homes Stock (MTH)
- Recent analysis of Meritage Homes highlights pressure on core business fundamentals, with a 27.6% average backlog contraction over two years and earnings per share declining 7.7% annually across five years.
- The erosion in returns on capital suggests Meritage Homes may be relying on aging profit centers, which could push management to reconsider its product mix and go to market approach in order to sustain profitability.
- We will examine how Meritage Homes' investment narrative is challenged by shrinking backlog and earnings pressure, and what that means now.
See how Meritage Homes compares with other builders facing similar backlog and earnings pressure by reviewing the hand picked list of solid balance sheet and fundamentals (23 results).
Meritage Homes Investment Narrative Recap
For you to own Meritage Homes, you need to believe the current backlog contraction and earnings pressure are workable problems, not permanent damage. The short term swing factor is how effectively the builder converts its expanded community count and entry level focus into steady orders without leaning too hard on incentives that hurt margins. The biggest risk right now is simple. Affordability sensitive buyers may hesitate just as Meritage enters quarters with limited visibility from a thinner backlog.
Pressure on returns on capital, softer net margins at 6.1% compared with 10.3% a year ago, and a 7.7% annual EPS contraction over five years all point to aging profit pools. That puts execution in the spotlight. The story improves if Meritage Homes can reset its product mix, tighten build cycles near the approximately 110 day level mentioned by analysts, and grow volume through its larger community base while holding the line on incentives. It worsens if higher land costs, more resale competition, and ongoing discounting combine to keep margins compressed for longer.
Recent commentary around Meritage Homes has focused on the same operational issues that now show up in the shrinking backlog and weaker EPS trend. Analysts had already flagged affordability driven demand risk in the entry level and first move up segments, along with thinner visibility because the builder converts backlog quickly and starts many homes without long lead presales. The new data on a 27.6% average backlog contraction over two years simply sharpens that concern and brings timing risk on near term revenue into clearer view.
The most interesting thread in earlier expectations was the plan for double digit community count expansion through 2025 and 2026, paired with faster construction and a focus on move in ready homes. That expansion can still act as a catalyst, because a larger footprint in Sun Belt markets gives Meritage more shots on goal if demand holds up. It also raises the execution bar. With margins already under strain and returns on equity described as low at 6.5%, any stumble on pricing discipline, land spend, or build efficiency could offset the benefits of that broader platform.
Meritage Homes' narrative projects US$6.4b revenue and US$453.0m earnings by 2029. This assumes 4.3% yearly revenue growth and an earnings increase of about US$67.5m from current earnings of US$385.5m.
Uncover why Meritage Homes' fair value indicates a 26% potential upside to its current price that may not last much longer.
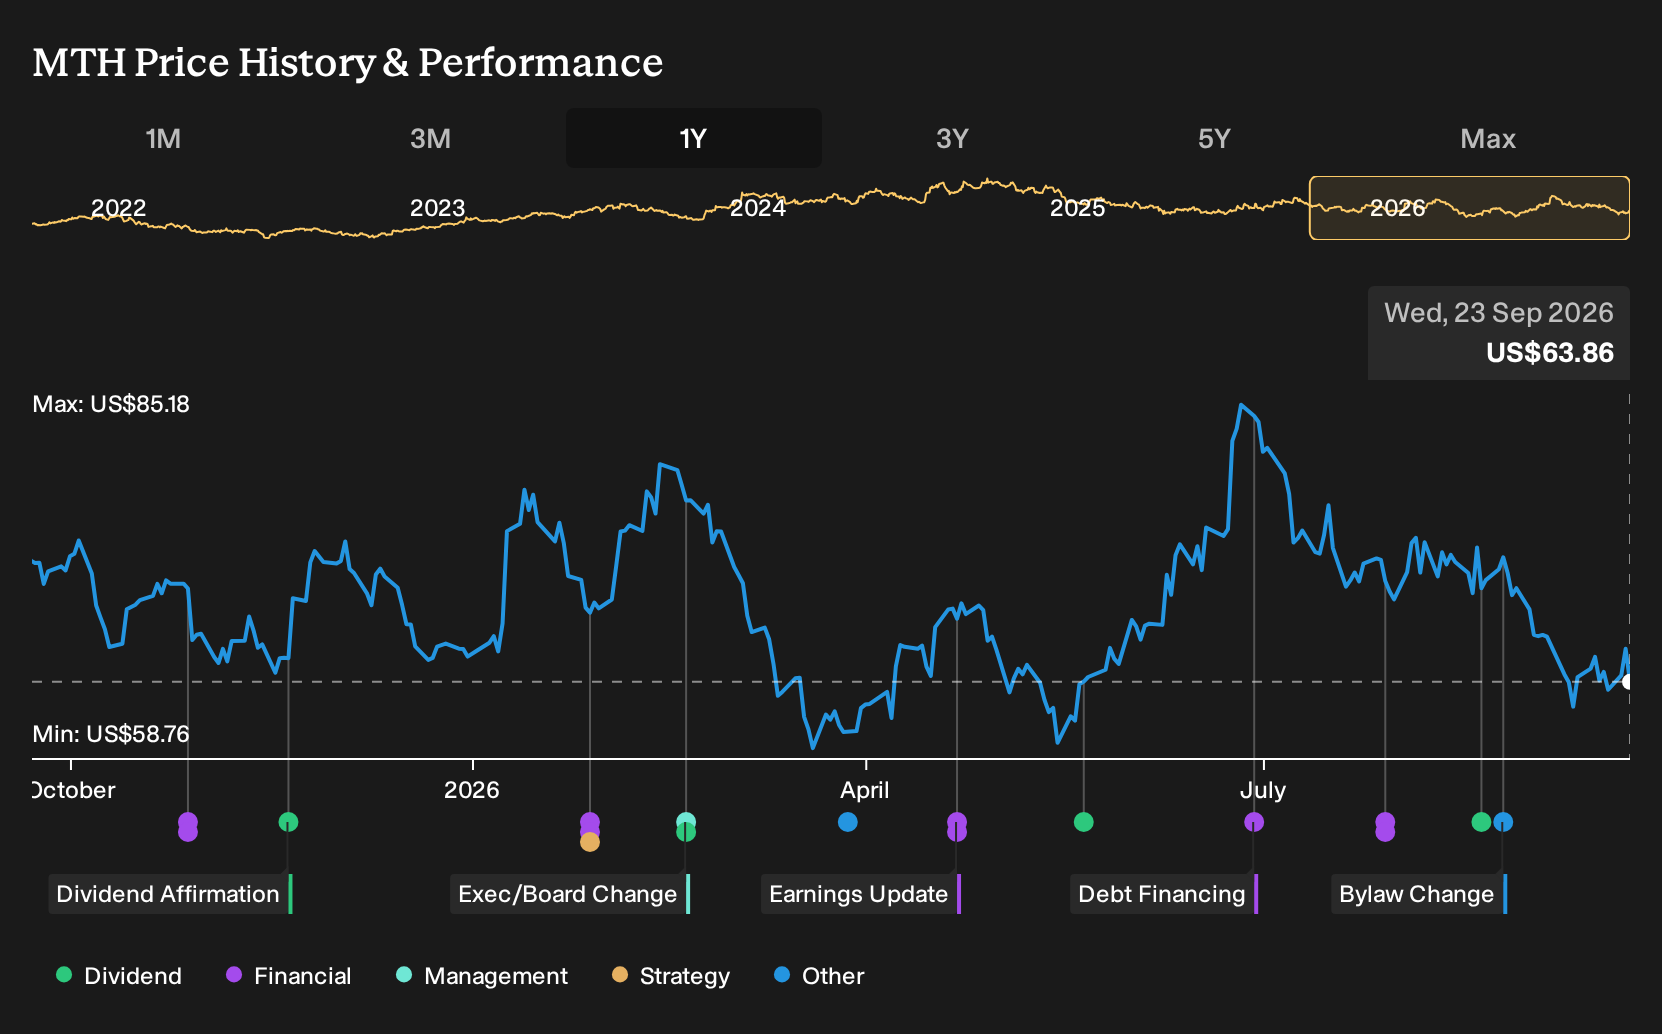
Exploring Other Perspectives
For Meritage Homes, the stark contrast comes from how bearish analysts view long term demand risk. The lowest cohort leaned into affordability and demographic headwinds and still modeled revenue of about US$6.2b and earnings near US$471.5m by 2029. That more cautious story may shift after this news, so compare both narratives yourself.
Explore 3 other Meritage Homes fair value estimates, including one that suggests it could be worth just $72.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Meritage Homes research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Meritage Homes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Meritage Homes' overall financial health at a glance.
Looking for more Meritage Homes style investment ideas?
If the Meritage Homes story has sharpened your thinking about backlog risk, balance sheets, and long term earnings power, it can help to widen the lens and compare it with other opportunities using the Simply Wall St Screener.
- For investors who want potential mispricings backed by solid fundamentals, start with a curated set of 30 high quality undervalued stocks and see which ones deserve a closer look.
- If downside protection matters most to you, filter for businesses that score well on stability and resilience by focusing on a 31 resilient stocks with low risk scores.
- When you prefer strong finances over headline stories, scan the list of solid balance sheet and fundamentals (23 results) to find companies that pair cleaner balance sheets with robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com