
Does Expanded HIV Prevention Access Change The Bull Case For Gilead Stock (GILD)?
- Gilead Sciences expanded its royalty-free voluntary licensing agreements for lenacapavir to cover once-yearly HIV prevention in 120 mainly low and lower middle income countries, and signed a separate accord with the Pan American Health Organization to support twice-yearly PrEP access across Latin America and the Caribbean.
- These moves deepen Gilead Sciences' role in long acting HIV prevention, while committing the business to complex technology transfer, manufacturing scale up and no profit supply models that can reshape its long term product mix and cost structure.
- We will now look at how Gilead Sciences' expanded lenacapavir access commitments might influence the broader investment narrative around HIV prevention.
Gilead Sciences Investment Narrative Recap
Owning Gilead Sciences means believing its HIV and oncology franchises can offset patent cliffs, pricing pressure and the firm’s current unprofitable position. The key near term swing factor is whether newer launches like lenacapavir and Trodelvy can rebalance the portfolio away from aging HIV regimens. The lenacapavir access deals are operationally intensive, but do not yet change that core question.
The biggest risk right now is execution. HIV still carries heavy earnings weight, margins have been under strain and the dividend is not well covered by earnings. Expanded no profit and low margin access for lenacapavir could add cost and complexity before any offset from a richer product mix comes through.
The fresh agreement with the Pan American Health Organization looks most relevant. It creates a regional channel for twice yearly lenacapavir PrEP across Latin America and the Caribbean, including 14 markets outside existing licenses. That pushes Gilead Sciences deeper into large scale prevention programs that depend on reliable supply, country readiness and payer mechanics.
For you as an investor, this PAHO deal ties directly into the main catalyst and the main risk. Successful rollout would support the case that lenacapavir can anchor a broader HIV prevention franchise. Any delay, logistical issue or pricing pushback would reinforce concerns about Gilead Sciences’ dependence on HIV, policy headwinds and the profitability of its access strategy.
Gilead Sciences' current analyst narrative points to US$34.5b in revenue and US$10.8b in earnings by 2029. This profile is built on 5.1% yearly revenue growth and an earnings increase of about US$1.6b from US$9.2b today.
Uncover why Gilead Sciences' fair value indicates a 4% potential upside to its current price that could narrow quickly.
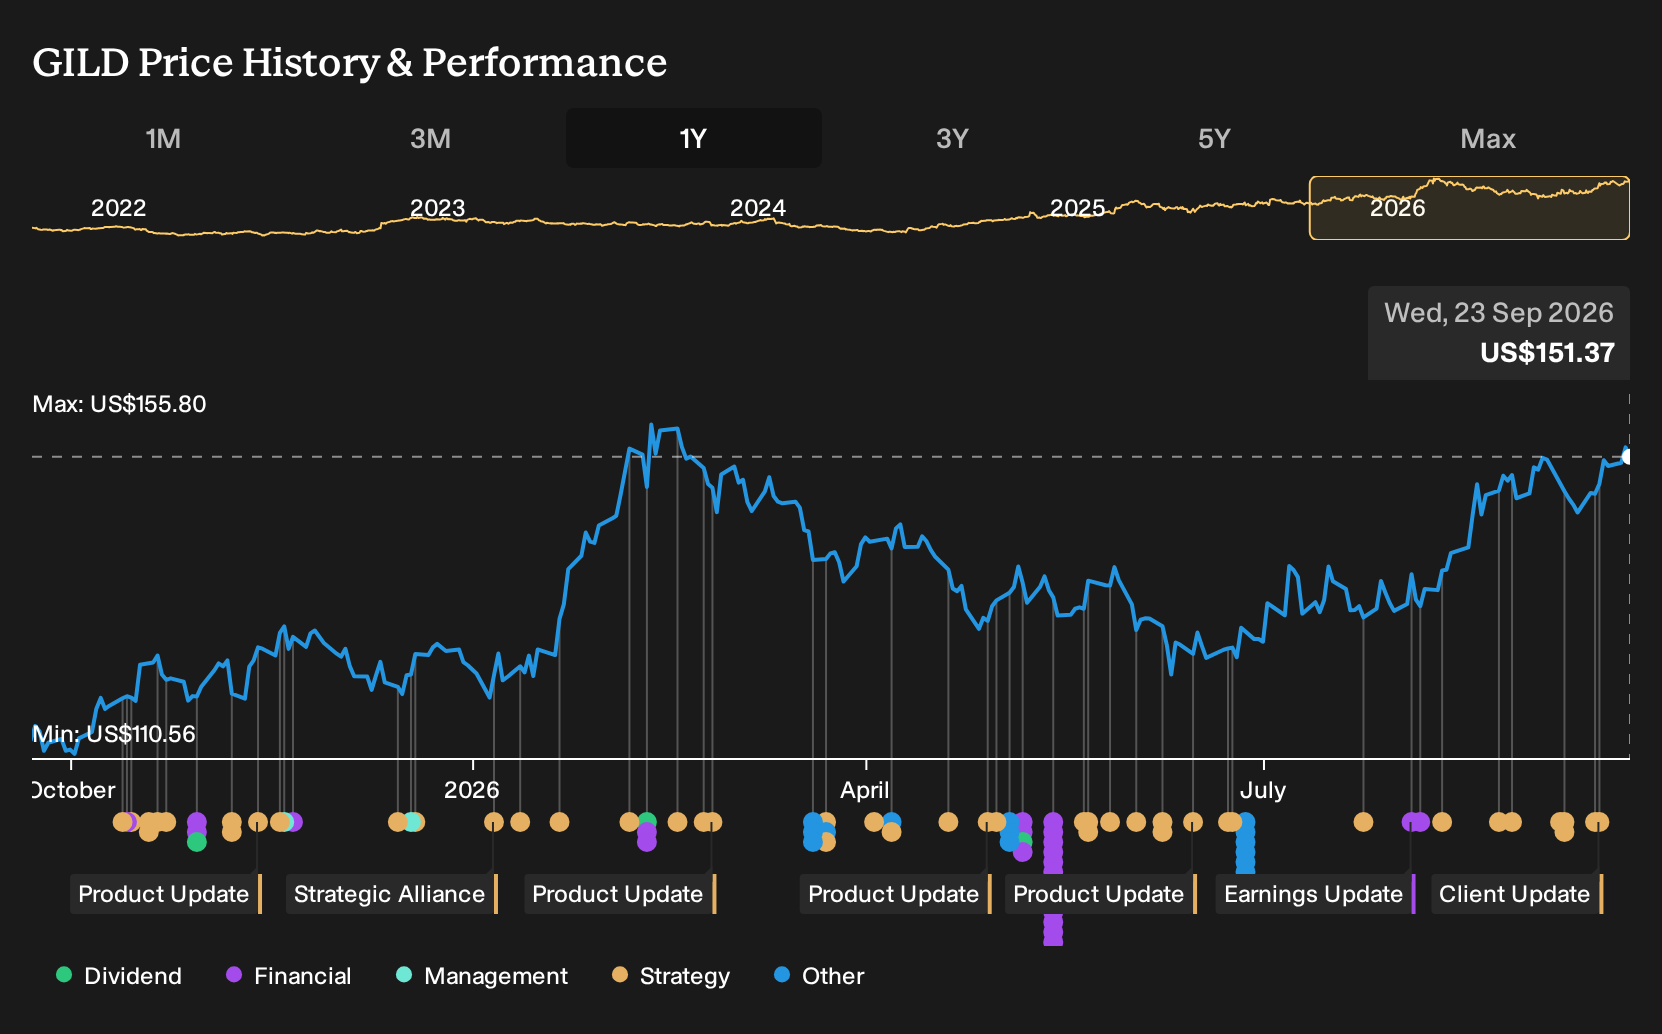
Exploring Other Perspectives
One alternate view on Gilead Sciences focuses on policy risk. The most pessimistic analysts were only assuming about 3.2% annual revenue growth to roughly US$33.5b and US$12.1b in earnings by 2029. That is a harsher story than consensus and could shift again once these new lenacapavir access deals are fully assessed.
Explore 4 other Gilead Sciences fair value estimates, including one that suggests as much as 15% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A starting point for your Gilead Sciences research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Gilead Sciences. The report includes a fundamental analysis summarized in a single visual, the Snowflake, which is designed to help investors quickly review Gilead Sciences' overall financial profile.
Looking For More Ideas Beyond Gilead Sciences?
If Gilead Sciences has sharpened your interest in healthcare and long term themes, it can be useful to line it up against other stocks with clear fundamental profiles. The Simply Wall St Screener lets you filter by balance sheet strength, dividend profile or valuation so you can build a watchlist that fits how you like to invest.
- If capital protection comes first for you, consider reviewing 31 resilient stocks with low risk scores that combine resilience scores with tighter risk profiles.
- For investors focused on quality at a reasonable price, scan through 30 high quality undervalued stocks that pair solid fundamentals with lower implied valuations.
- If you prefer early stage potential with room to grow, you can assess 9 elite penny stocks with strong financials that already show stronger financial traits than most peers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com