
Lucid (LCID) Stock May Trade Above Fair Value Despite Autonomous Fleet News
Lucid Group has seen its share price slide to US$4.16 despite fresh headlines about autonomous driving partnerships, which puts the focus squarely on what investors are paying for its current sales base. With the stock under pressure over several time frames, the question now is how much of the business story is already embedded in that revenue multiple.
- Over the past 5 years, Lucid Group has delivered a share price loss of 98.4%, which raises sharp questions about how the market currently values each dollar of its sales.
- The recently announced partnership with Bolt to deploy up to 25,000 autonomous vehicles across Europe can shape expectations for Lucid's future revenue mix and the timing of any shift toward more recurring fleet income.
- Your read on Lucid Group is one view; the desks covering it have another. See what analysts think Lucid Group's shares could be worth.
For investors, the debate is whether Lucid Group's current share price is justified by its sales given this mix of long term share price declines and new autonomous fleet ambitions.
If you want a wider set of ideas on companies tied to autonomous and AI themes rather than focusing only on Lucid Group, a targeted screen of 36 AI small caps is a useful next step.
Has Lucid Group Run Too Far on Sales?
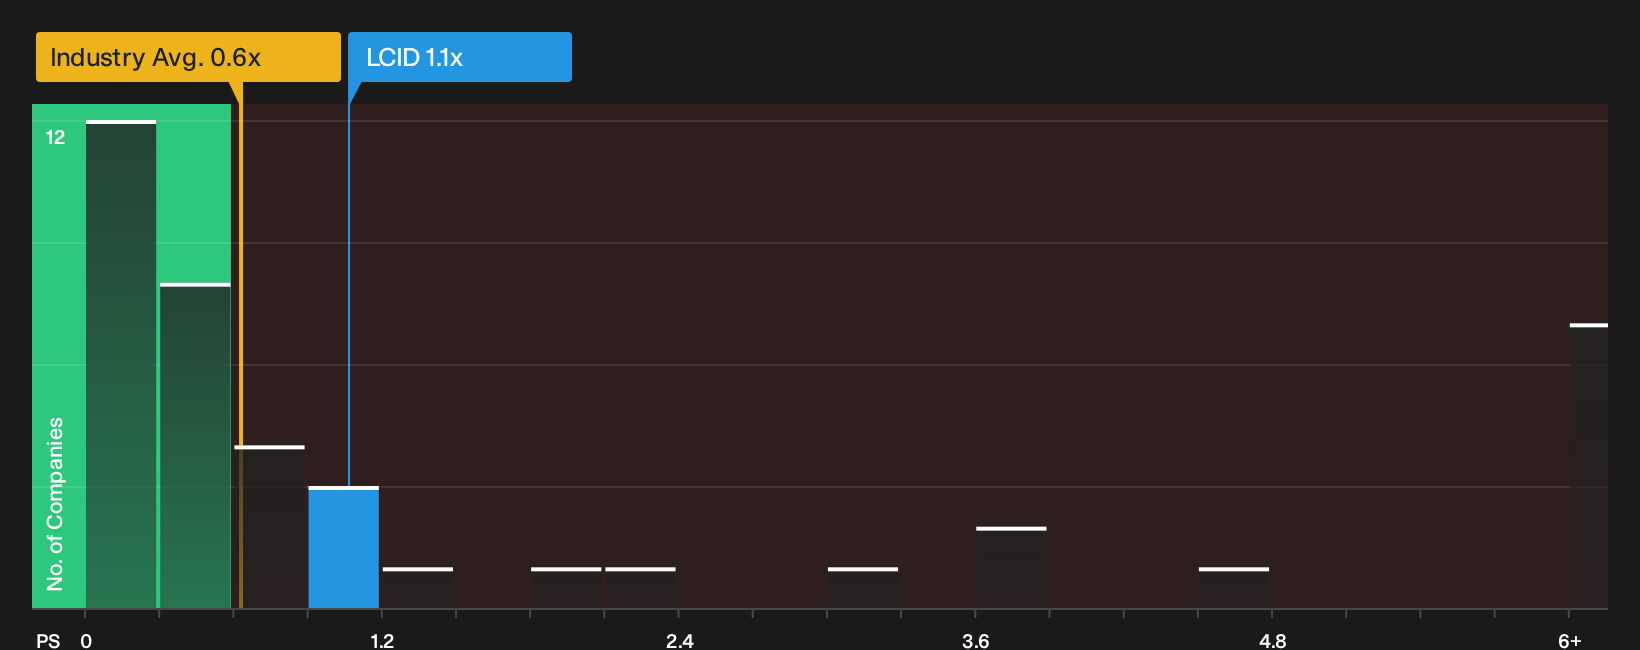
The P/S ratio is a straightforward way to compare Lucid Group while it is still loss making on earnings and free cash flow. Lucid trades on a P/S of about 1.1x, which is above both the wider auto industry average of roughly 0.6x and a peer group closer to 0.5x. That means investors are currently paying more for each dollar of Lucid's revenue than for many established vehicle manufacturers and closer peers.
Because the fair multiple that adjusts for Lucid's growth profile, margins, size and risk points to a much lower P/S than the current 1.1x, the stock screens as overvalued on this framework. The model is heavily penalising the business for ongoing losses and the quality of its revenue, so the implied fair ratio looks more like a warning flag about how expensive the shares screen on sales than a precise target. Despite the Bolt autonomous fleet deal indicating a different mix of future revenue, the current P/S still asks investors to pay a premium to sector and peer levels for Lucid's existing top line. Explore the numbers behind Lucid Group's P/S valuation.
The Lucid Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Lucid Group pick up where that P/S puzzle leaves off and set out the specific growth, margin and earnings paths that would need to play out for the stock to be worth materially more or less than today’s price. Rather than providing one static output from a single ratio or model, these scenarios map out the future that number relies on, so you can follow Lucid Group's actual progress against it on the Community page.
Bulls in the Lucid Group community lean hard into the autonomous and Saudi-scale buildout story, while bears focus on funding strain and execution risk.
Bull case: 50% undervalued
"The newly announced Uber and Nuro partnership, including a planned $300 million Uber investment and a commitment to deploy at least 20,000 Lucid Gravity vehicles as robotaxis over six years, is expected to open a large and fast-growing autonomous fleet market to Lucid, driving significant revenue expansion and potential margin improvement via technology licensing and high-volume fleet sales…"
Discover why this Narrative puts Lucid Group at 50% undervalued.
Bear case: 19% overvalued
"Ongoing negative free cash flow and the need for repeated capital raises, as indicated by the upcoming 2026 convertible maturity and the recent reverse stock split, are likely to cause further shareholder dilution and continue to suppress earnings per share for the foreseeable future…"
Explore why this Narrative puts Lucid Group at 19% overvalued.
One last Lucid Group check that sits beyond today's price tag
All the ratio work still leaves one big question hanging over Lucid Group, which is how professional analysts presently map its revenue and earnings story a few years down the road. Explore where analysts expect Lucid Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com