
Is Idorsia (SWX:IDIA) Undervalued As Its Share Price Slide Tests The Bull Case?
Idorsia (SWX:IDIA) has drawn fresh attention after a sharp pullback, with the share price down about 22% over the past month and roughly 36% in the past 3 months.
That recent slide comes after a much stronger stretch for Idorsia, with a year to date share price return of 7.44% and a 1 year total shareholder return of 17.42%. However, the long run picture remains mixed, with a 5 year total return down 80.68% and a 3 year total shareholder return of 69.60% that hints at how quickly sentiment around the stock can swing as investors reassess both its growth potential and risk profile.
Look past Idorsia's sharp swings and use the 619 high quality undiscovered gems to identify other potential rebound candidates that are still flying under most investors' radar.
Bulls see Idorsia as a beaten down pipeline story, while bears point to ongoing losses and past drawdowns. Which side does the current valuation actually support as the stock resets after this latest slide?
Most Popular Narrative: 13% Undervalued
On the most followed valuation narrative, Idorsia screens as undervalued, with a fair value of CHF5.00 against the last close at CHF4.36. This puts the current price at a discount while still anchoring expectations to specific revenue and earnings assumptions.
Analysts are assuming Idorsia's revenue will grow by 24.8% annually over the next 3 years. Analysts assume that profit margins will increase from 158.3% loss today to 13.3% positive margin in 3 years time.
See why 8 investors see Idorsia as 13% undervalued.
Result: Fair Value of CHF5.00 (UNDERVALUED)
Still, if QUVIVIQ continues to gain reimbursement and TRYVIO progresses smoothly after recent regulatory and clinical updates, Idorsia's current discount could narrow faster than many expect.
Find out about the key risks to this Idorsia narrative.
Another View: Idorsia Through A Sales Multiple Lens
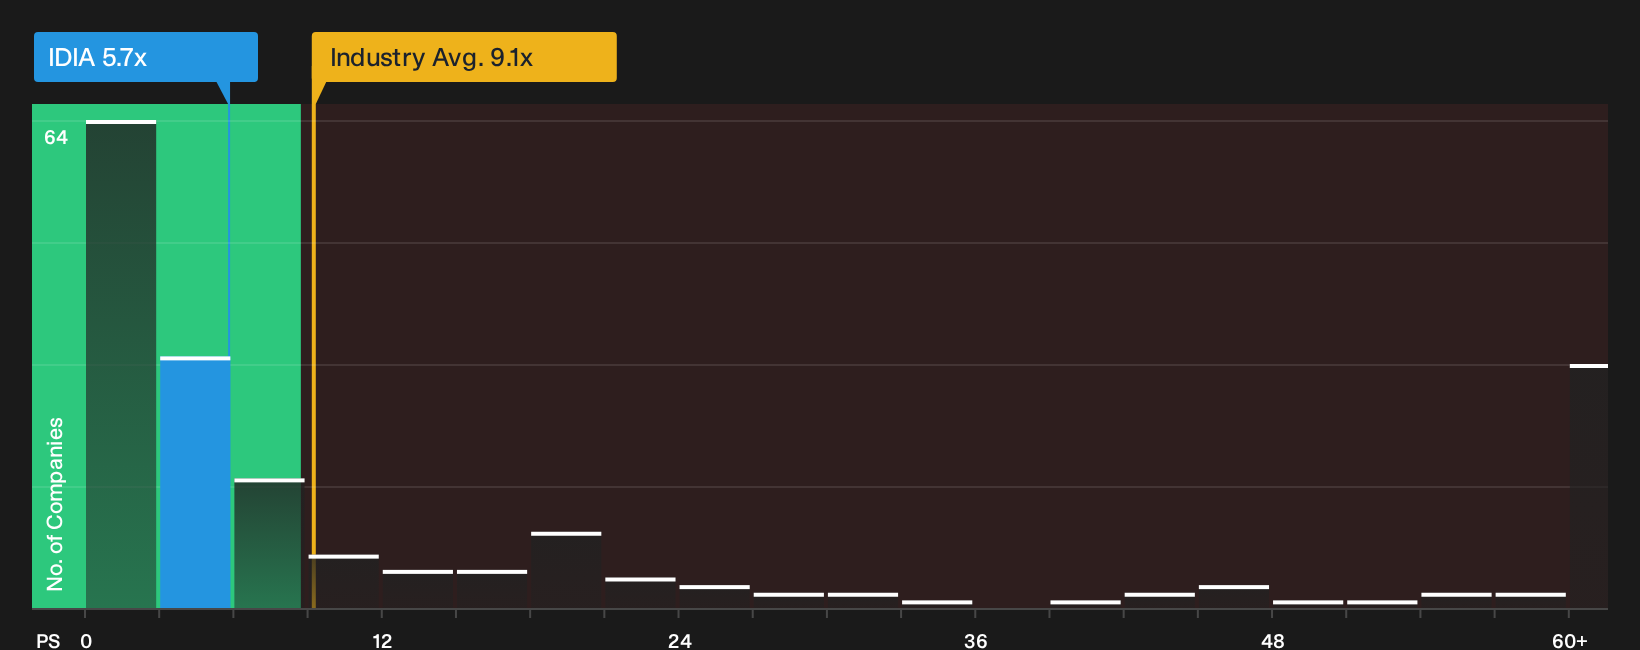
Idorsia may look cheap on one metric and stretched on another. On P/S of 5.7x, the stock trades below both the European biotech average of 9.1x and a peer average of 8x, yet it sits above an estimated fair ratio of 4.7x that the market could eventually gravitate toward. Is that gap a cushion or a warning sign for you as an investor?
To stress test this second lens and see how the current P/S gap might matter for upside or downside risk, take a closer look at the valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Idorsia is split, with some investors focused on setbacks and others on potential upside. Consider reviewing the data yourself promptly, before opinions harden. To see both sides of that debate clearly, weigh the 3 key rewards and 4 important warning signs.
Looking for more Idorsia-like investment ideas?
If Idorsia has your attention, do not stop here. You could miss out on other stocks that fit your style and risk comfort.
- Target fresh rebound potential by scanning a curated pool of quality mispriced opportunities through the 177 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by focusing on companies screened for stronger financial footing using the list of solid balance sheet and fundamentals (200 results).
- Lean into consistency and capital protection by concentrating on sturdier performers filtered through the 230 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com