
Digital Turbine Stock After CBO Resignation Has The Bull Case Changed?
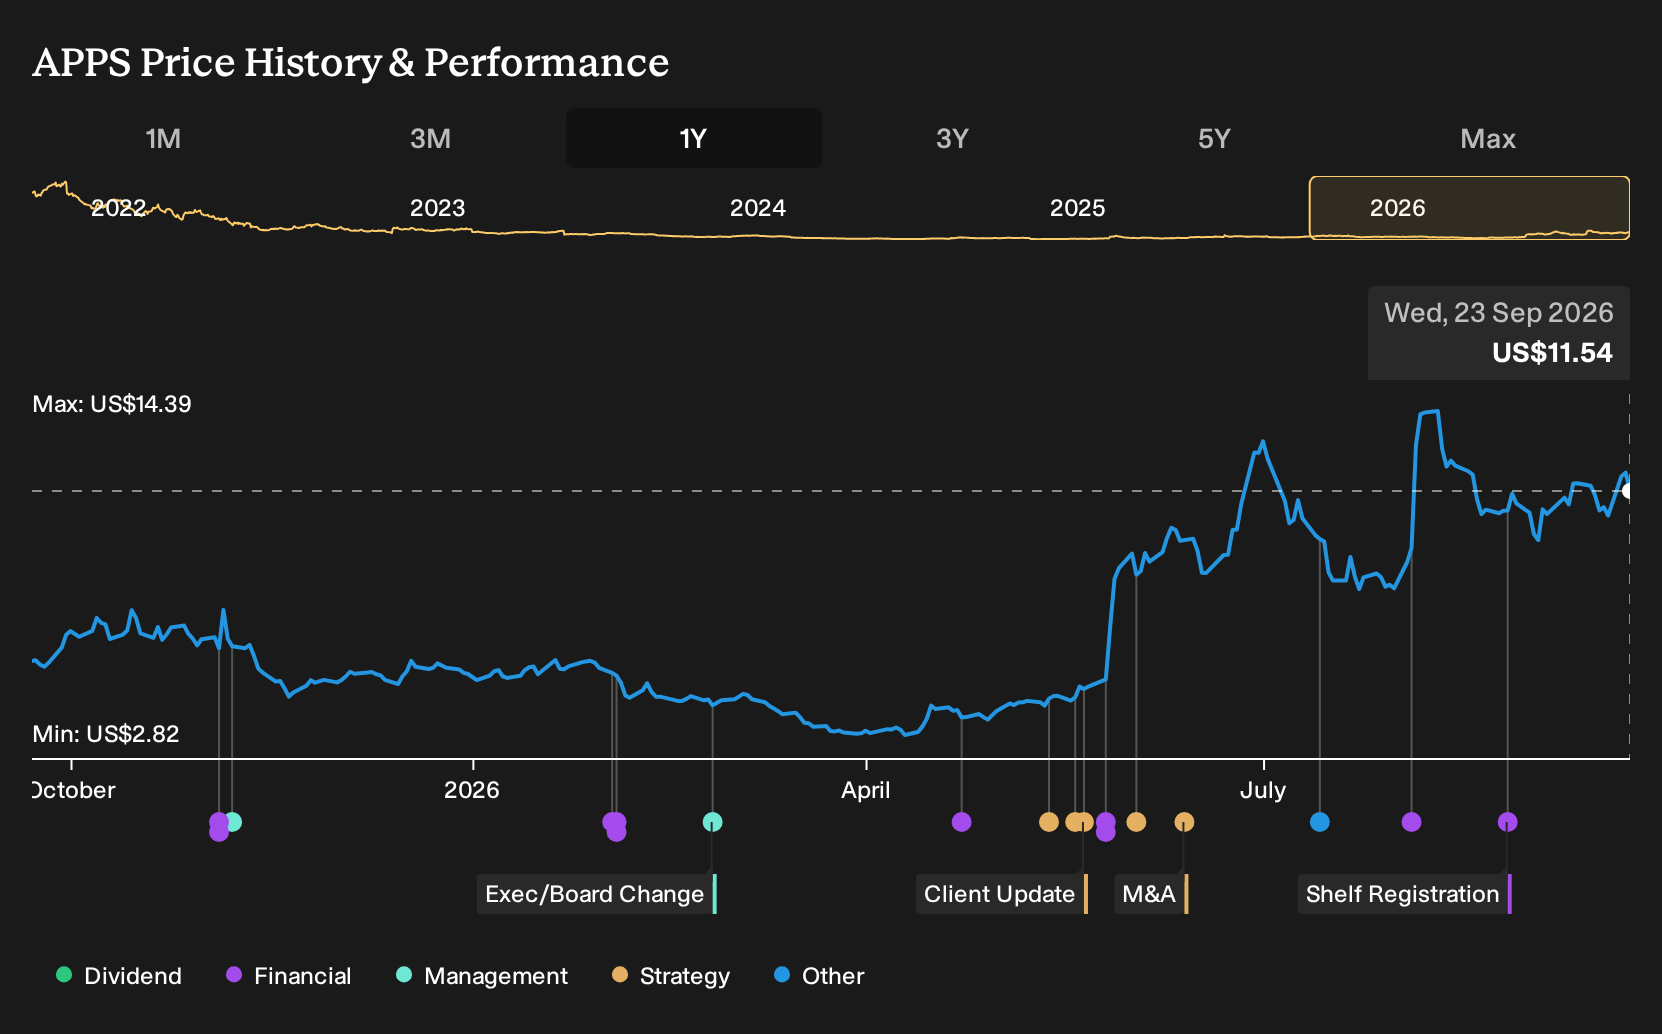
- Digital Turbine reported that Chief Business Officer Michael Akkerman resigned on September 23, 2026, with his departure effective October 30, 2026, to take a Chief Executive Officer role at another company.
- The exit of the executive responsible for major commercial relationships and growth initiatives raises practical questions about Digital Turbine's business pipeline, client momentum, and execution priorities.
- We will now assess how Digital Turbine's investment narrative could be affected by the Chief Business Officer's decision to depart for a CEO role.
Balance potential disruption at Digital Turbine by scanning a curated group of resilient businesses in our 31 resilient stocks with low risk scores, which features steadier leadership profiles and lower risk scores.
Digital Turbine Investment Narrative Recap
To be comfortable owning Digital Turbine, you need to believe the mobile growth platform can keep widening its reach with carriers, OEMs, advertisers, and publishers while lifting profitability from today’s loss making base. The big near term swing factor is execution around On Device Solutions and the App Growth Platform, where consistency in partner activity and campaign volume really matters.
Michael Akkerman’s exit touches those commercial relationships directly, so it introduces some operational noise. If succession is handled cleanly and deal flow remains intact, the main risk still looks broader. Reliance on partners, exposure to “walled gardens”, and ongoing investment in first party data and AI remain the bigger operational pressure points.
There are no other fresh announcements tied to this resignation, so context comes from the existing profile. Digital Turbine is unprofitable today, forecast to remain loss making over the next three years, and has a history of increasing losses over the past five years. That makes commercial leadership stability especially important while the business leans on cost control and mix improvements.
Analysts see revenue growth that is slower than both the US market and the wider Software sector, while also expecting share count to keep rising. Against that backdrop, the combination of a volatile share price, heavy dependence on partners, and leadership turnover in a growth facing role keeps execution risk front and center for any near term catalyst you care about.
Digital Turbine's current profile assumes revenue will grow at 12.0% a year, lifting revenues to $842.3 million and earnings to $14.9 million by 2029 from an earnings loss of $35.0 million today. This implies a $49.9 million earnings swing to reach the consensus profit target.
Uncover why Digital Turbine's fair value indicates a 49% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You might see Digital Turbine very differently if you lean into the most optimistic angle. The bullish analysts were penciling in revenue of about $861.3 million and earnings of $125.5 million by 2029, far above the consensus $842.3 million and $14.9 million. With a key commercial leader exiting now, those upbeat forecasts may get revisited. Consider both possibilities before deciding how this fits your portfolio.
Explore 4 other Digital Turbine fair value estimates, including one that suggests as much as 99% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Digital Turbine research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Digital Turbine. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Digital Turbine's overall financial health at a glance.
Looking For More Ideas Beyond Digital Turbine?
If this Digital Turbine update has sharpened your thinking, it can help to widen the lens and compare it with other companies that fit very different profiles. Use the Simply Wall St Screener to line up alternatives side by side so you can judge risk, income potential, and quality on your own terms.
- If resilience and balance sheet strength are high on your checklist, start with a list of solid balance sheet and fundamentals (23 results) that can act as potential anchors in a portfolio.
- If you are hunting for compelling valuations backed by fundamentals, scan a 30 high quality undervalued stocks that might align better with your preferred risk and return trade off.
- If income is your focus, review a 7 dividend fortresses that aim to pair higher yields with more established payout records.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com