
How 1.1 Million Square Feet Of Leases At Highwoods Properties (HIW) Has Changed Its Investment Story
- Highwoods Properties, Inc. reported that since July 1, 2026 it has signed 1,100,000 square feet of second generation leases, including over 200,000 square feet of new commitments and several long term renewals across multiple markets.
- This leasing volume gives investors a fresh data point on how Highwoods Properties is filling existing space, managing rollover risk, and keeping office occupancy aligned with real tenant demand rather than headlines about remote work.
- We will now look at how Highwoods Properties' investment narrative could be influenced by this large block of recently signed leases.
Highwoods Properties Investment Narrative Recap
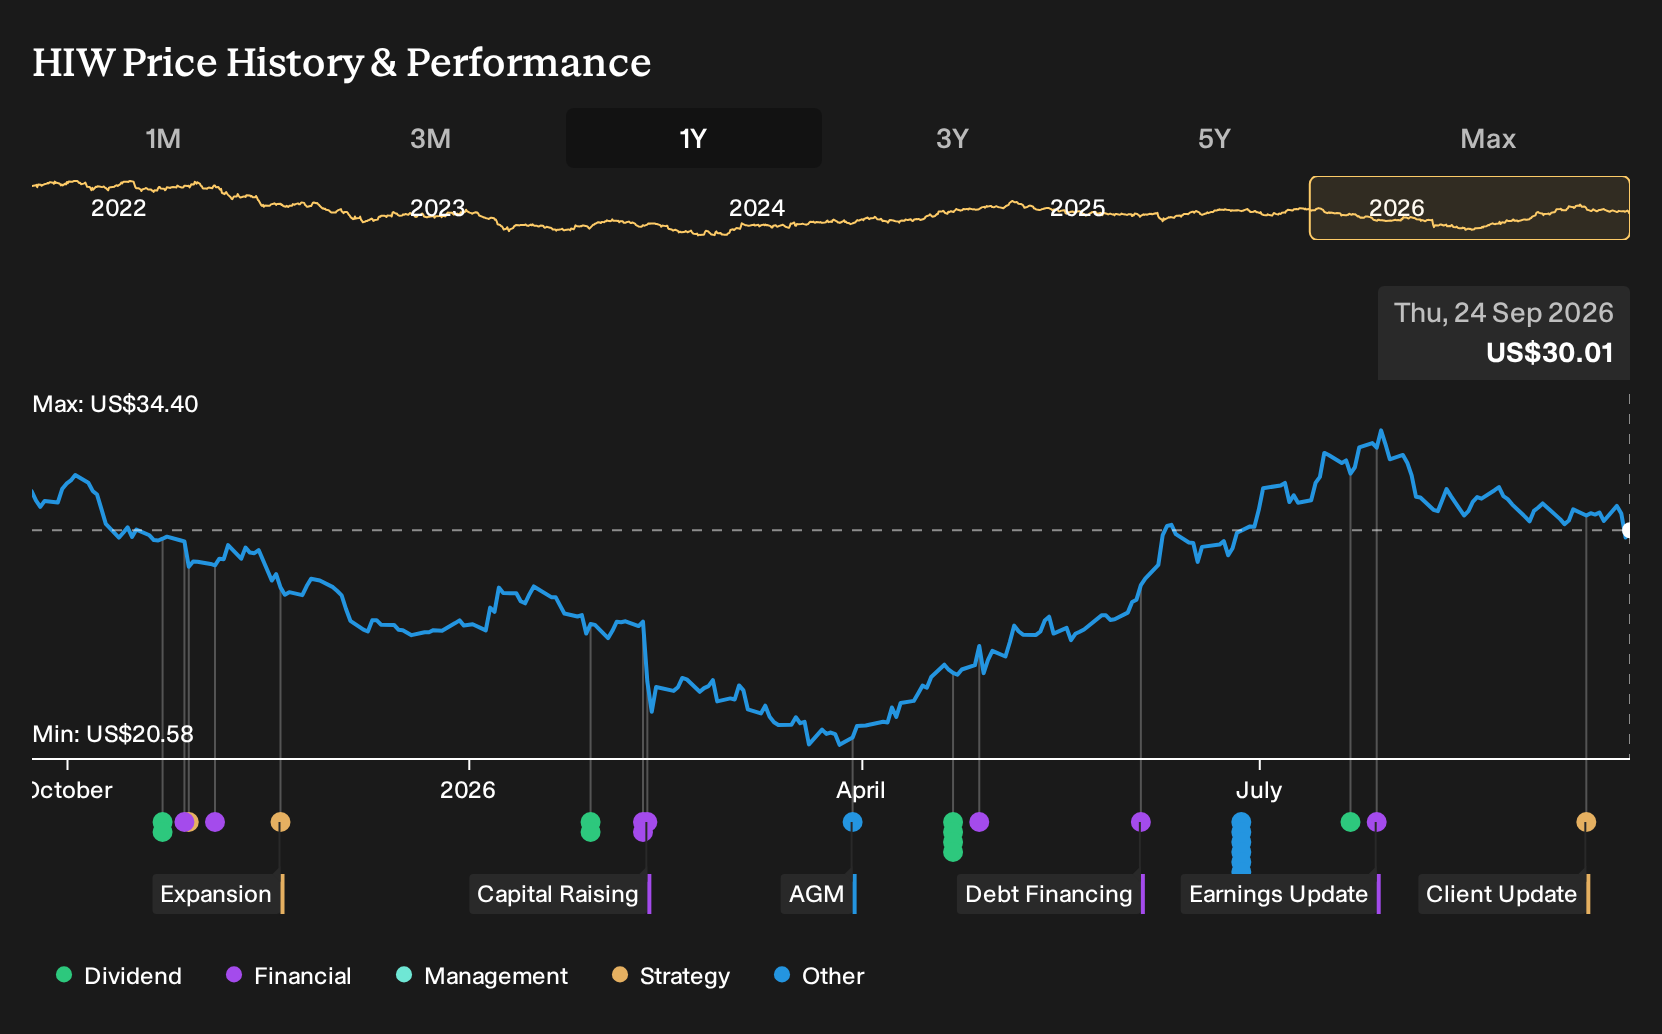
For Highwoods Properties, investors need to decide whether high quality Sunbelt business districts can continue to attract tenants even as remote and hybrid work affects traditional office demand. The 1,100,000 square feet of second generation leasing since July 1, 2026, including over 200,000 square feet of new leases, directly addresses near term occupancy and rollover concerns.
The key short term catalyst is how quickly that signed space turns into rent and stabilizes cash flow, particularly with interest costs already a concern and earnings forecasts pointing lower. The biggest risk is that physical office usage stalls again, which could leave Highwoods Properties with higher vacancy and capital spending without matching revenue.
The leasing announcement sits alongside an earnings story that is already mixed. Highwoods Properties recently reported earnings growth of 31.5% over the past year and net margins of 19.8%, supported by a large one off gain of US$107.4m within the 12 months to 30 June 2026. That non recurring item means many investors focus more on recurring rent and occupancy trends.
Analysts currently expect earnings to decline on average by 22% per year over the next three years, while revenue is forecast to grow 2.9% annually. This new block of second generation leases provides a concrete data point to test those expectations, including assessments of interest coverage, dividend support at a 6.74% yield, and the timing of any future occupancy related improvement.
What The New Leases Mean For Highwoods Properties' Forecasts
Highwoods Properties is being modelled on some fairly specific assumptions. Analysts are working off revenue growth of 3.1% per year and current earnings of US$166.4 million, with consensus estimates pointing to US$91.6 million of profit by 2029. That implies an earnings decline of about US$74.8 million relative to earnings today, even as forecasters project revenues of US$919.4 million in the same 2029 timeframe.
Uncover why Highwoods Properties' fair value indicates an 8% potential upside to its current price before the gap closes.
Exploring Other Perspectives
Some of the most optimistic analysts looked past near term office worries and focused on Highwoods Properties' potential rent reset. They were penciling in revenue of about US$958.8 million and earnings of US$89.4 million by 2029, with a higher P/E assumption. Those views were set before this leasing news, so you can expect opinions to evolve.
Explore 2 other Highwoods Properties fair value estimates, including one that indicates up to 17% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Highwoods Properties research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Highwoods Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Highwoods Properties' overall financial health at a glance.
Looking For More Ideas Beyond Highwoods Properties?
Once you have a view on Highwoods Properties, it can help to widen the lens and see how other businesses stack up on income, value, and balance sheet strength using the Simply Wall St Screener.
- For investors who want potential income resilience on top of capital appreciation, scan a curated set of income-focused opportunities through 7 dividend fortresses.
- If your priority is paying less for quality than you think it is worth, run your filters over a targeted pool of value candidates using 29 high quality undervalued stocks.
- When capital preservation matters just as much as upside, compare Highwoods Properties with a carefully filtered 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com