
RealReal (REAL) Opens New Stores, Is The Stock Still Cheap?
RealReal (REAL) is back in the spotlight after opening new brick and mortar locations in Glendale, California, and Chestnut Hill, Massachusetts, tying physical consignment hubs directly into its online luxury resale platform.
Recent share price action has been far less upbeat than RealReal’s store roll out, with the stock down 20.05% on a 30 day share price return and 43.73% on a year to date share price return, even as the 3 year total shareholder return is very large and points to earlier enthusiasm that now appears to be fading.
Capitalize on RealReal’s brick and mortar push by scanning a curated 16 high quality undiscovered gems that pair strong fundamentals with business models investors may not be fully pricing in yet.RealReal now combines fresh store openings, record GMV of US$617 million and a share price that has slid hard this year. Is most of the rerating already in the rear-view mirror, or is the market still underappreciating the upside?
Most Popular Narrative: 48% Undervalued
RealReal last closed at $8.89 while the most followed valuation narrative pegs fair value at $17.25. That gap sets a high bar for what needs to go right in the business for this thesis to hold.
Accelerating consumer demand for authenticated, sustainable luxury goods among Millennials and Gen Z, as evidenced by record growth in new consignors and a growing active buyer base, is expanding RealReal's addressable market and fueling higher transaction volumes, directly supporting future revenue growth.
Ongoing reinvestment in marketing, referral programs, and omni-channel experiences, such as pop-up events and new store openings, is successfully acquiring and re-engaging high-quality consignors, creating a flywheel effect that supports recurring supply, high customer retention, and long-term revenue expansion.
See why 7 investors see RealReal as 48% undervalued.
Result: Fair Value of $17.25 (UNDERVALUED)
Still, the RealReal story can change quickly if supply growth slows or commission rates compress further, since both would directly pressure margins and earnings expectations.
Find out about the key risks to this RealReal narrative.
Another View on RealReal’s Valuation
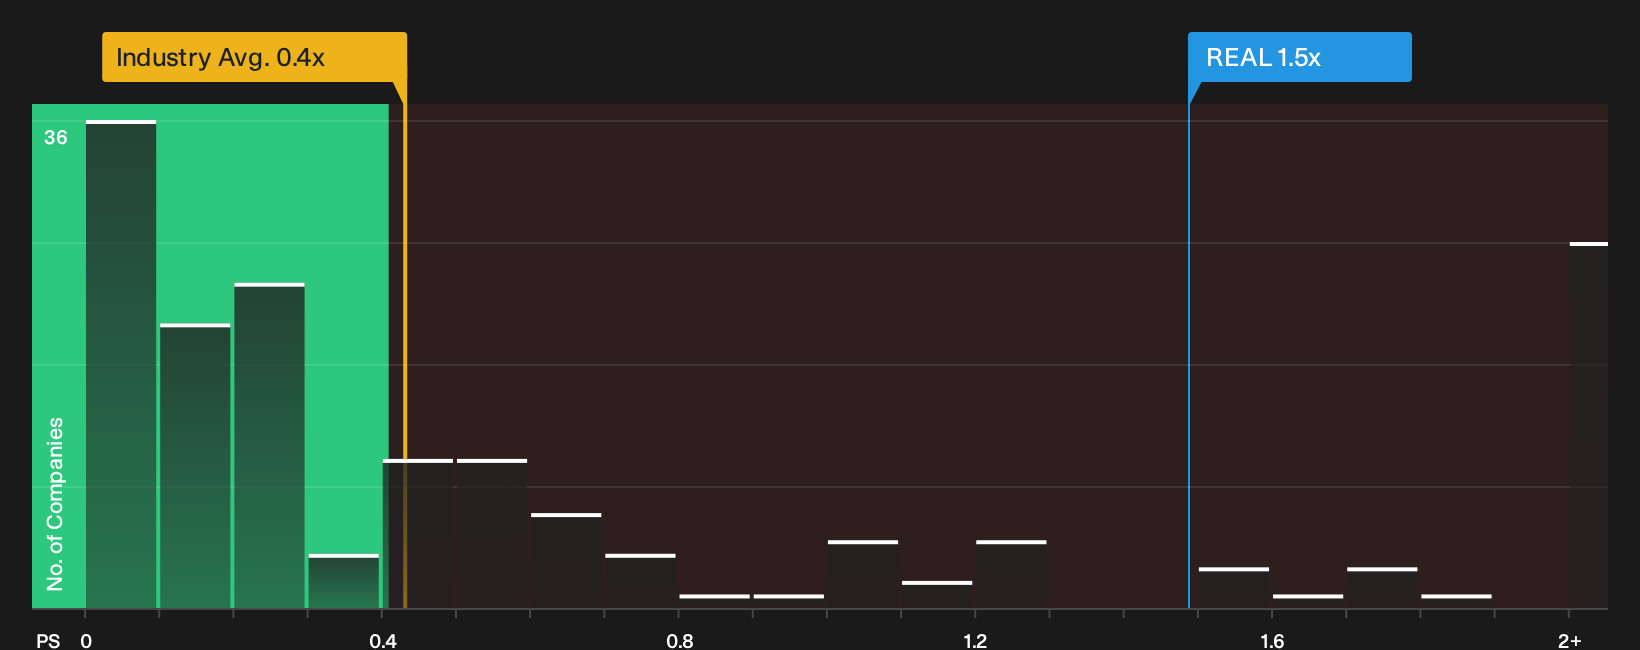
While the fair value narrative points to RealReal trading below intrinsic worth, the simple P/S picture is tougher. The stock changes hands at about 1.5x sales, compared with a 1.1x peer average and 0.4x for the wider US Specialty Retail group. The fair ratio sits at 1.3x, so investors are paying a premium today. Is that extra pricing power a margin of safety or a margin of error?
To pressure test that premium against hard numbers, review the full valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around RealReal can feel messy, so consider acting promptly, review both the concerns and the upside, and ground your stance in the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond RealReal?
RealReal is only one way to play this theme. Diversify your watchlist now so you are not chasing the crowd after the next move.
- Target resilient cash generators by scanning a curated 7 dividend fortresses that focuses on higher yields with balance sheets built to handle tougher conditions.
- Hunt for potential mispricings through a focused 29 high quality undervalued stocks designed to surface stronger fundamentals at prices the market may be overlooking.
- Prioritize capital preservation by using a carefully filtered 30 resilient stocks with low risk scores that highlights businesses with sturdier financial profiles and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com