
Dividend Raise Might Change The Case For Investing In BancFirst (BANF)
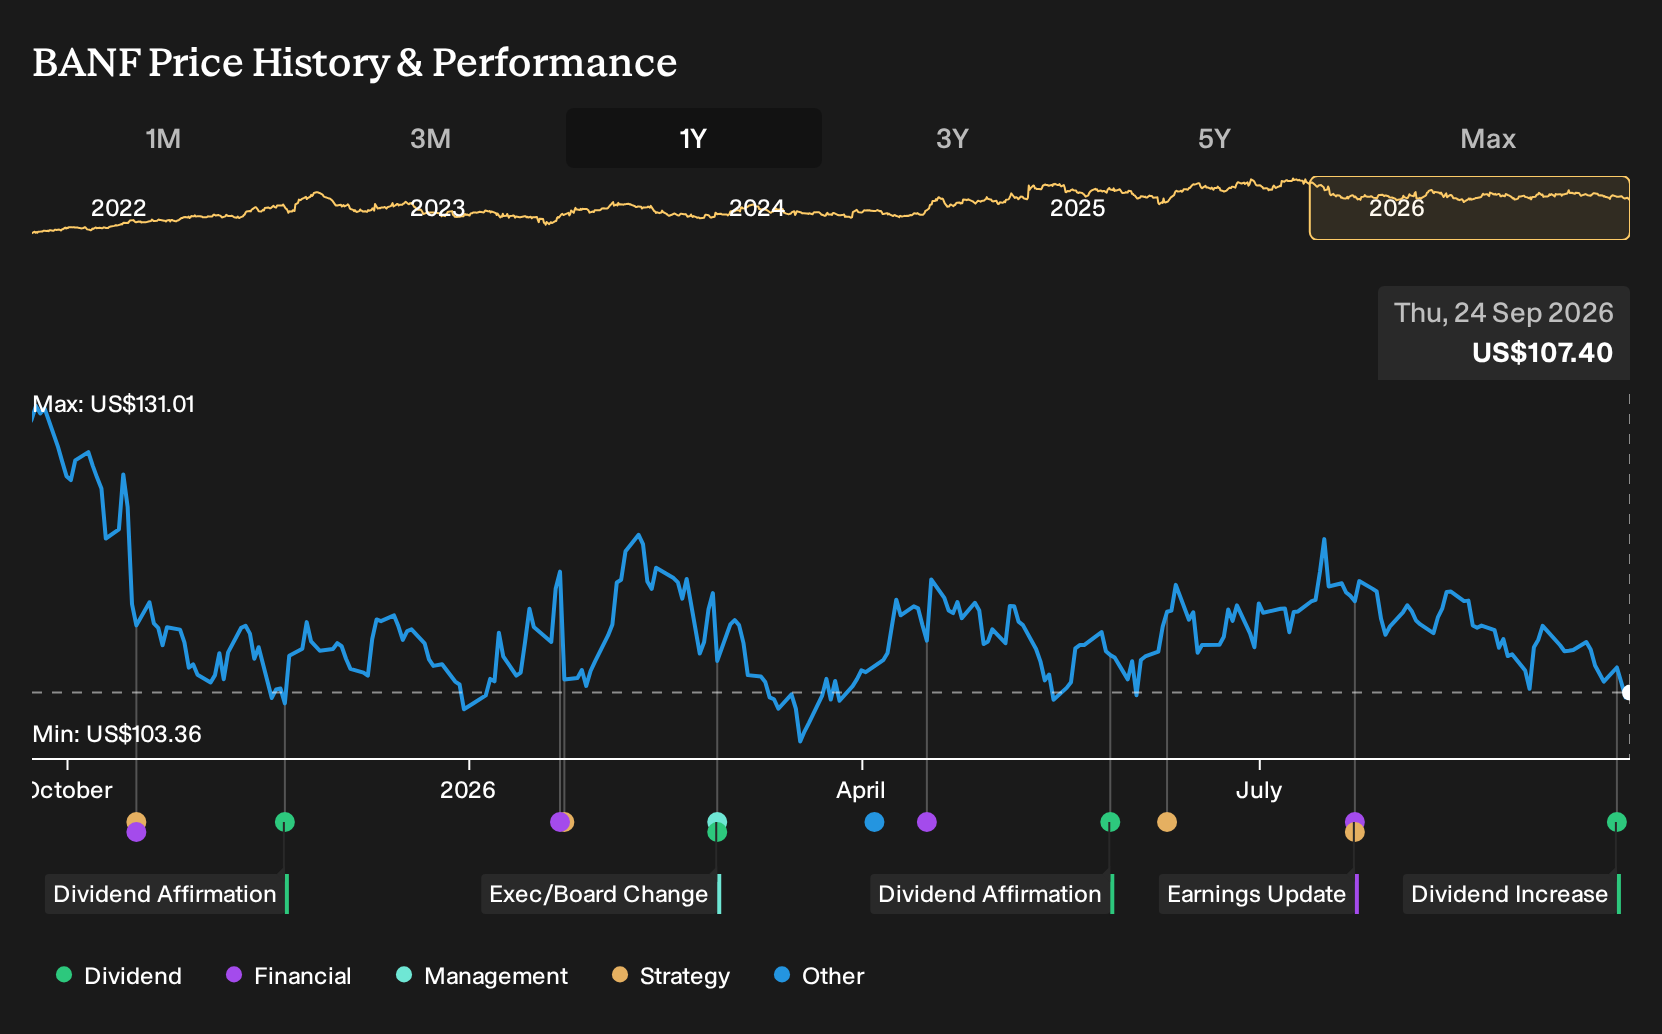
- BancFirst Corporation raised its regular payout, declaring a quarterly dividend of US$0.52 per share that was paid on October 15, 2026 to holders of record on September 30, 2026.
- This richer cash return matters for income focused holders because it relates to BancFirst’s capital strength and its mix of interest and fee based revenue.
- We will now explore how BancFirst’s higher quarterly dividend could influence the broader investment narrative that investors use to judge the bank.
Scan beyond BancFirst and see how this dividend story compares with other income focused opportunities on our curated list of 7 dividend fortresses
BancFirst Investment Narrative Recap
To own BancFirst, you need to be comfortable with a regional bank that leans on steady earnings rather than rapid expansion. The key near term swing factor is how efficiently it runs a growing branch network while revenue growth is described as only mediocre and its efficiency ratio is expected to worsen. The higher quarterly dividend by itself does not materially change that operating picture.
The biggest current risk is that slower top line progress and higher costs could squeeze the 35.3% net margin, especially if net interest income growth continues to soften. That would make it harder to justify BancFirst’s premium P/E against banks whose revenue is growing faster.
The fresh US$0.52 quarterly dividend sits alongside a history of reliable payouts, including the current 1.83% yield, and very strong capital levels with a total capital ratio above 20%. For income focused holders, that capital strength matters because it underpins both the cash distribution and the capacity to fund acquisitions such as American Bank of Oklahoma and the planned Spirit BankCorp deal.
Those Tulsa focused transactions remain the most relevant backdrop for this dividend move because they drive the main catalyst. Management is trying to turn a larger footprint, plus roughly 30% non interest income from treasury, trust, insurance and mortgage services, into durable earnings while keeping returns on equity in the top tier. Any stumble on integration, cost discipline or revenue mix could weigh more heavily on the story than the dividend increase itself.
What The Dividend Signals About BancFirst’s Forecasts
BancFirst's narrative projects US$874.9 million in revenue and US$286.7 million in earnings by 2029, based on analyst models that assume 7.0% yearly revenue growth and an earnings increase of about US$34.9 million from current earnings of US$251.8 million.
Uncover why BancFirst's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster tightly at about US$124.33 per share. That kind of agreement shows some retail analysts currently see BancFirst as fairly clearly priced. You still need to weigh that against risks around efficiency, revenue mix and the impact of Tulsa focused acquisitions on future performance.
Explore another BancFirst fair value estimate, including one that suggests it could be worth just $124.33.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BancFirst research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BancFirst. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BancFirst's overall financial health at a glance.
Looking For More BancFirst Investment Ideas?
If the BancFirst story has sharpened your thinking about yield, value and risk, it can be useful to test that same framework across a wider set of opportunities using the Simply Wall St Screener.
- For investors who want income with some resilience, scan a curated 7 dividend fortresses that combine higher yields with sturdier fundamentals.
- If capital preservation ranks higher on your checklist, filter for 30 resilient stocks with low risk scores that score well on financial strength and earnings stability.
- When you are hunting for potential bargain opportunities, cast a wider net across 29 high quality undervalued stocks that pair stronger balance sheets with attractive pricing signals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com