
Weatherford International (WFRD) Stock Still Looks Undervalued Despite Its 341% Run
Weatherford International has delivered a very strong 5 year run, which naturally raises a question for anyone looking at the stock today. With the shares now around US$84, the key issue is whether that price still lines up with what the business is earning.
- A roughly 341.1% return over 5 years puts a lot of weight on the idea that Weatherford International's earnings power can support a much higher valuation than in the past.
- The business model is heavily tied to oilfield services and related equipment, so expectations for future contract quality and margins can have a direct impact on how much investors are willing to pay for each dollar of earnings.
- The analysts covering Weatherford International have run their own numbers. See what analysts think Weatherford International's shares could be worth.
The issue now is whether Weatherford International's current share price is justified by its earnings when stacked up against the Fair Ratio benchmark.
If you want to test whether Weatherford International's valuation still feels reasonable in context, compare it with other 30 high quality undervalued stocks.
Does Weatherford International Look Undervalued on Earnings?
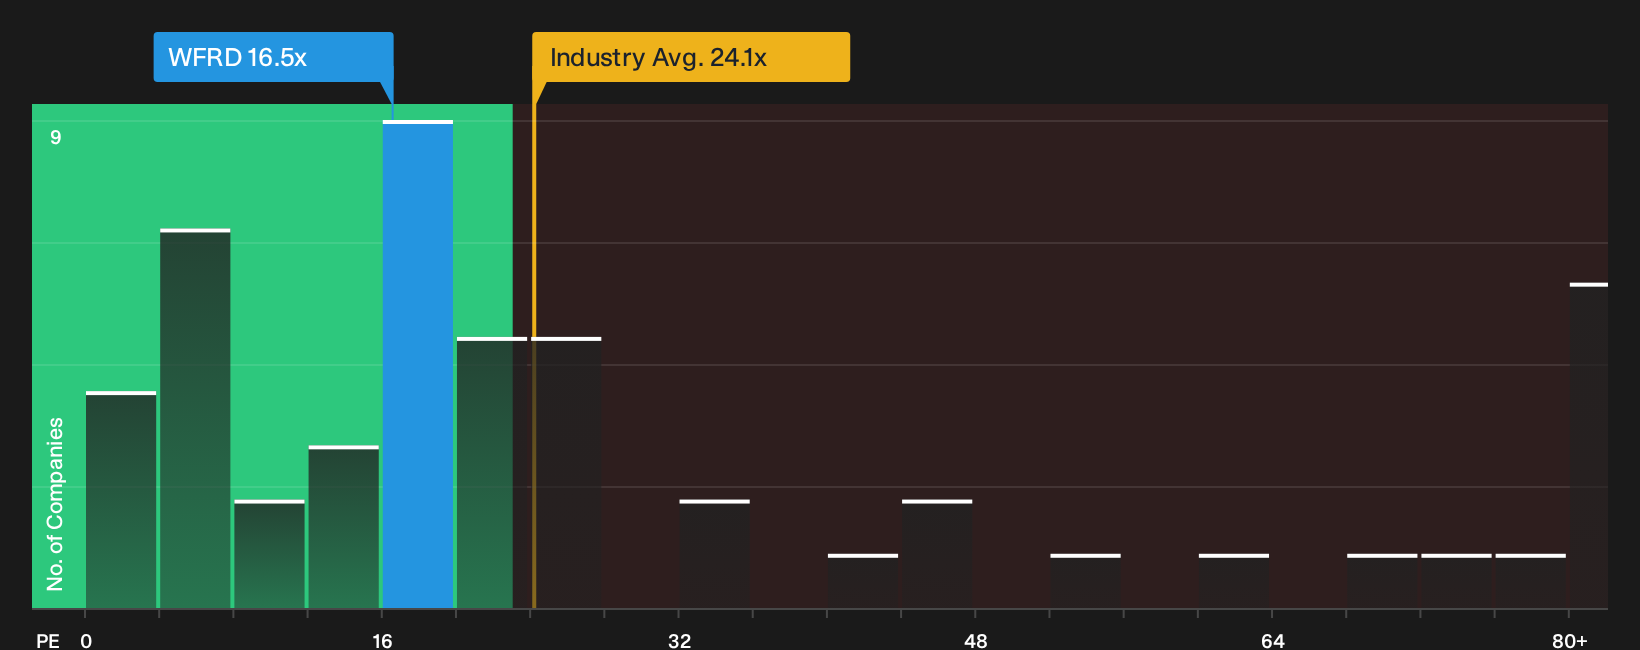
The P/E ratio suits Weatherford International because earnings are a key reference point for investors in service heavy energy businesses. On this measure the stock trades on about 16.5x earnings, which sits below the Energy Services industry average of roughly 24.1x and far under the peer group closer to 75.2x.
Against the tailored Fair Ratio benchmark, which reflects Weatherford International's own mix of growth prospects, profitability profile, size and risk, the current P/E comes in below what that model would typically flag for this type of business. For anyone assessing the shares today, the gap between the present 16.5x and that implied level is an important signal that the market is pricing the company's earnings on the lower side compared with both its industry and the more customised yardstick. Explore the numbers behind Weatherford International's P/E valuation.
The Weatherford International Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Weatherford International valuation puzzle leaves off by spelling out which combinations of growth, margin profile and earnings power would need to hold for the stock to be worth meaningfully more or less than today’s market price on the Community page. Rather than focusing on a single model output, each narrative lays out the assumptions behind its view of fair value so you can compare those inputs with future results as they arrive.
One of the top community narratives on Weatherford International: 29% undervalued
"Weatherford's expanding portfolio of advanced technologies is positioning the company to benefit as oilfield operations become more complex and customers seek solutions…"
Discover why this Narrative puts Weatherford International at 29% undervalued.
Before you act on Weatherford International’s valuation, there is one more factor to weigh
Price multiples only tell part of the story for Weatherford International, because the checks behind the scenes have raised specific concerns that some investors may want to examine closely before making a move. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com