
LXP Industrial Trust (LXP) Looks Fairly Valued, Is There More Upside To Come?
LXP Industrial Trust stock moves
LXP Industrial Trust (LXP) has drawn fresh attention after a period of steady trading, with the REIT showing a 22.89% year-to-date return and a 41.15% total return over the past year.
LXP Industrial Trust’s share price has climbed 9.59% over the past 90 days to US$60.93, while a 41.15% 1-year total shareholder return and 59.52% 3-year total shareholder return point to momentum that investors are still testing against the trust’s fundamentals.
Scan how LXP Industrial Trust’s momentum compares with other real estate plays by reviewing a curated set of 31 resilient stocks with low risk scores in similar income-focused sectors.
LXP Industrial Trust now carries a strong run of shareholder returns and a focused warehouse portfolio, yet those gains only help if the current US$60.93 price still leaves room for value.
Most Popular Narrative: 1% Overvalued
LXP Industrial Trust is trading at $60.93 against a widely followed fair value narrative of about $60.20. The market price currently sits just above that framework while investors weigh the impact of the take private proposal and future leasing results.
The analysts have a consensus price target of $60.2 for LXP Industrial Trust based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $401.3 million, earnings will come to $14.0 million, and it would be trading on a PE ratio of 326.0x, assuming you use a discount rate of 9.0%.
See why 2 investors see LXP Industrial Trust as 1% overvalued.
Result: Fair Value of $60.20 (OVERVALUED)
Still, LXP Industrial Trust’s reliance on large single tenant assets, along with its concentrated Sunbelt and Midwest exposure, could magnify any vacancy spikes or local market softness.
Find out about the key risks to this LXP Industrial Trust narrative.
Another View on LXP Industrial Trust’s Value
The first narrative frames LXP Industrial Trust as about 1% overvalued at $60.93 versus a $60.20 fair value built from earnings forecasts and a high implied P/E. A different lens tells a very different story.
Simply Wall St’s DCF model estimates LXP at $80.93 per share, which puts the current $60.93 quote about 24.7% below that cash flow based value and labels the stock as undervalued. The question for investors is which set of assumptions appears more realistic for a long term owner.
Look into how the SWS DCF model arrives at its fair value.
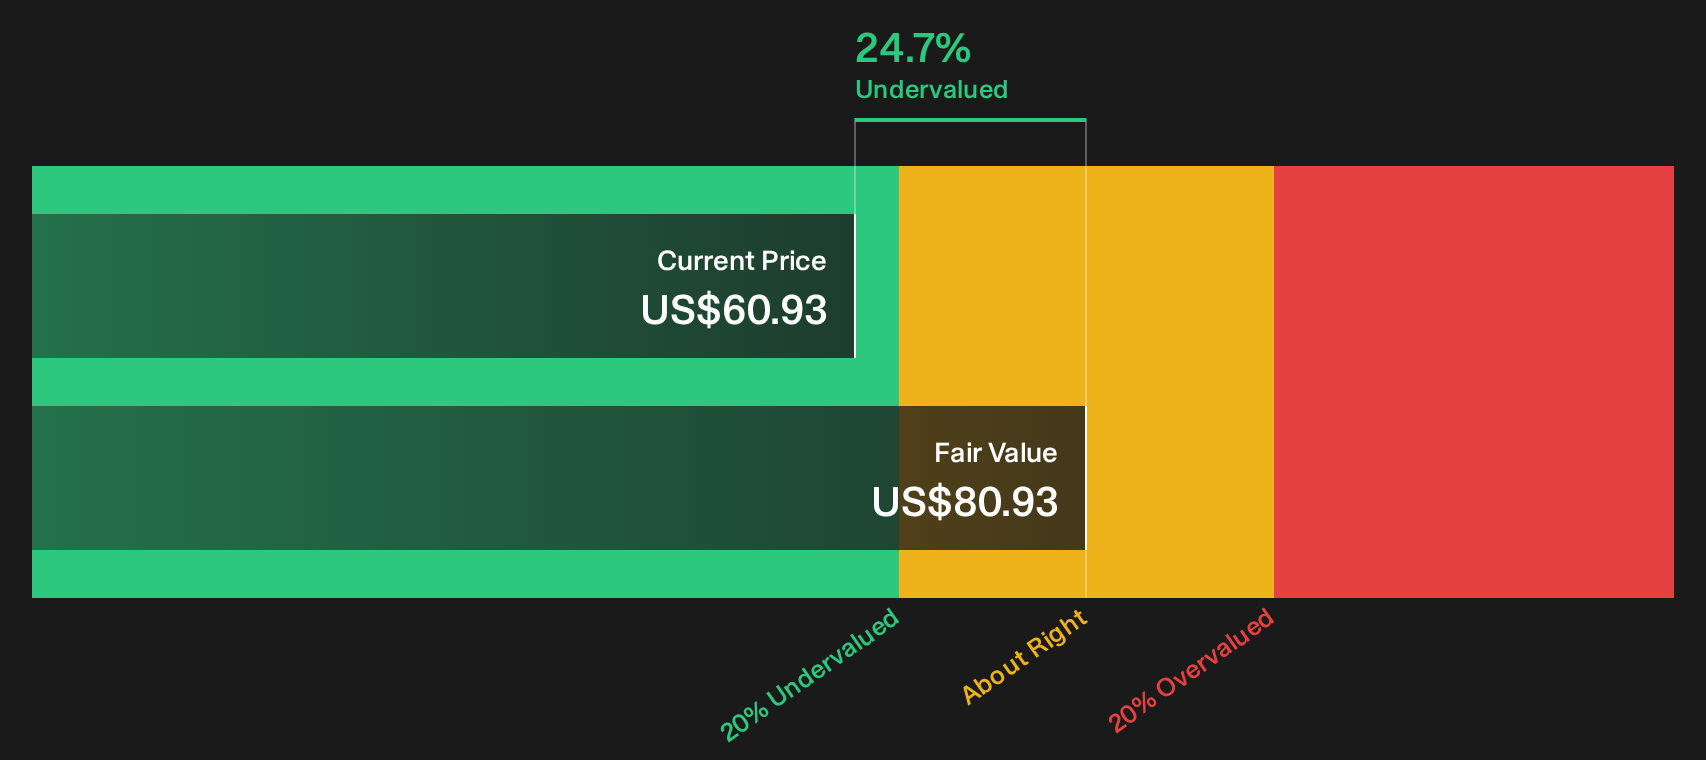
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out LXP Industrial Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on LXP Industrial Trust’s value and risk profile make this a judgment call. Move quickly, review the data, and weigh both sides with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond LXP Industrial Trust?
If LXP Industrial Trust has sharpened your interest, broaden your watchlist and pressure test your thesis by lining it up against other targeted opportunities using the Simply Wall St screener.
- Target long term compounding potential by scanning a curated pool of 30 high quality undervalued stocks that combine quality fundamentals with prices that sit below intrinsic estimates.
- Strengthen your income stream by reviewing 7 dividend fortresses built around higher yields and businesses that aim to keep payouts supported by underlying cash generation.
- Limit unpleasant surprises by filtering for list of solid balance sheet and fundamentals (23 results) so you focus on companies with sturdier financial footing when markets turn rough.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com