
Is Earnings Beat Altering The Investment Case For HEICO Stock (HEI)?
- HEICO reported Q2 and Q3 2026 results with higher year on year sales and earnings, supported by strong aftermarket demand and healthy free cash flow.
- The combination of expanding market share and raised analyst earnings estimates highlights how recent execution is contributing to a more optimistic view of HEICO's long term business model.
- We will now look at how HEICO's quarterly revenue and earnings performance could reshape the broader investment narrative around the company.
Compare HEICO's momentum with a curated list of peers by scanning the list of solid balance sheet and fundamentals (23 results).
HEICO Investment Narrative Recap
To own HEICO, you need to be comfortable with a business built around aftermarket aircraft parts, repair services, and specialty electronics that depend on steady air travel and defense demand. The recent Q2 and Q3 2026 updates, with higher year on year sales and earnings and healthy free cash flow, support that core thesis.
The key short term catalyst is continued aftermarket strength and execution on orders as airlines and defense customers keep fleets in service. The biggest risk is pressure from OEM competition and any slowdown in orders that could expose HEICO's higher debt and test how durable current margins really are.
The Q3 2026 earnings release is the clearest operational marker in this story. HEICO reported higher sales and earnings year on year, alongside strong free cash flow, which reinforces the idea that its broad catalog of PMA parts, repair capabilities, and electronics is still finding willing buyers across commercial and defense customers.
For shareholders, that update matters because it speaks directly to execution on the core catalysts. Solid Q3 numbers help support ongoing investment in acquisitions and product development while servicing debt. At the same time, any future cooling in aftermarket demand or tighter OEM control over parts approvals would remain the main operational watchpoints.
What HEICO's Forecasts Say About Expectations
Analysts are effectively asking you to judge whether HEICO can grow into a much larger and more profitable enterprise over the next few years. Their models build around double digit top line expansion, higher margins, and a richer valuation multiple than the broader US Aerospace & Defense peer group.
Consensus forecasts assume revenue increases of 11.3% per year over the next three years. Those projections sit alongside a margin lift from 16.4% today to 18.1% over the same horizon, which would support higher earnings on every dollar of sales if achieved.
On the earnings line, analysts expect profit to rise from US$847.7 million today to US$1.3b by about 2029. That implies an earnings step up of roughly US$452 million, which is a meaningful jump in absolute dollar terms and would need support from both volume and pricing, as well as cost discipline.
Valuation assumptions sit at the center of the story. To line up with the consensus price target, HEICO would need to trade at a P/E of 54.3x those 2029 earnings, compared with 49.4x today and 34.3x for the wider US Aerospace & Defense industry. That gap means you would be paying a premium for the company, backed by the view that its growth profile and business mix justify a higher multiple than peers.
HEICO's narrative projects US$7.1b revenue and US$1.3b earnings by 2029. This assumes 11.3% yearly revenue growth and an earnings increase of roughly US$452 million from current earnings of US$847.7 million.
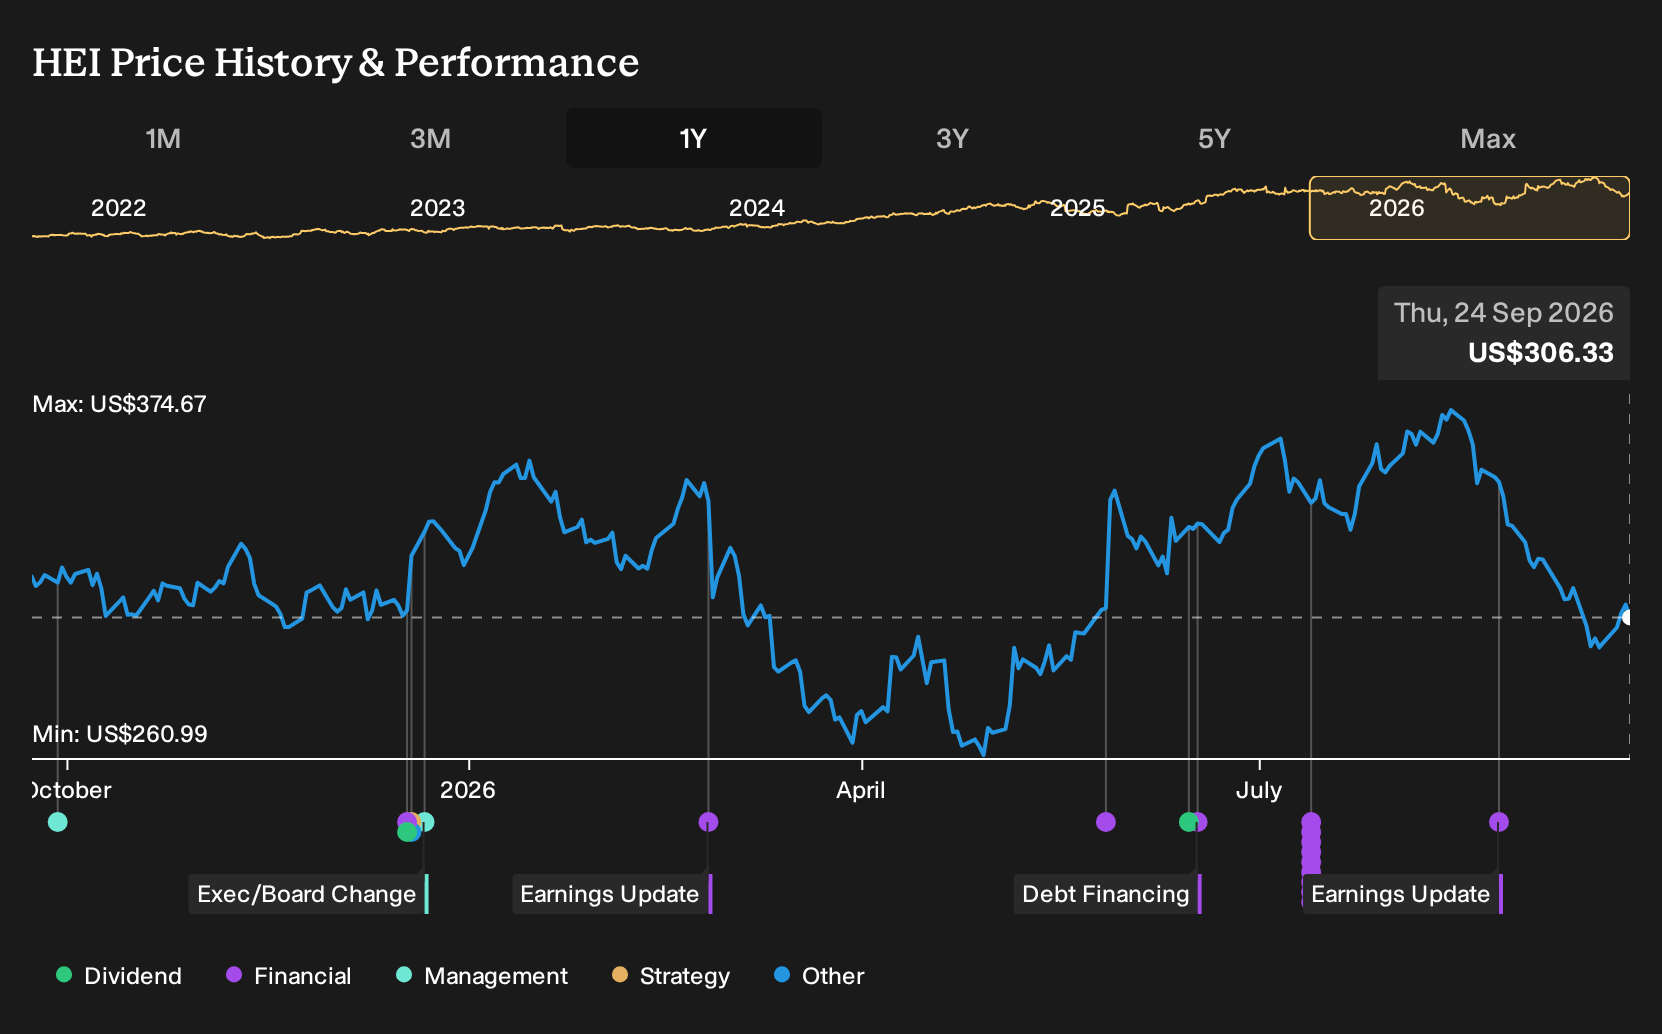
Sell side targets pull these ingredients together into a wide range of potential outcomes. The consensus price target sits at US$393.95 per share, with the most optimistic analyst at US$491.00 and the most cautious at US$294.00. With the stock at US$299.43 on 23 September 2026, that central target is 24.0% above the current price. This spells out how much improvement in scale, profitability, and valuation multiple those forecasts are asking you to underwrite.
Softer details around capital structure also matter. Analysts expect the share count to grow by 0.29% annually for the next three years, which would slightly dilute existing holders and means future per share metrics need to clear that extra hurdle to meet the consensus numbers.
Uncover why HEICO's fair value indicates a 29% potential upside to its current price, a discount that could close more quickly than expected.
Exploring Other Perspectives
One alternate angle on HEICO focuses on the acquisition engine as a potential upside surprise. The most optimistic analysts were modeling revenue to reach about US$7.7b and earnings around US$1.4b by 2029, well above the baseline. Those projections came before the Q2 and Q3 news, so you should expect views to shift and explore how your own expectations compare.
Explore 3 other HEICO fair value estimates, including one that suggests as much as 29% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your HEICO research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for HEICO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HEICO's overall financial health at a glance.
Looking for more HEICO style investment ideas?
If the HEICO story has sharpened your thinking about quality, price, and risk, it can help to line it up against other opportunities that share similar traits or offer a very different profile. The Simply Wall St Screener lets you cast a wider net without losing that focus on fundamentals.
- For investors hunting for mispriced quality, a good next step is to review a curated set of companies that combine strong fundamentals with attractive valuations by scanning 30 high quality undervalued stocks.
- If resilience matters most to you, consider broadening your watchlist to businesses that pair solid financial footing with lower risk profiles through the 31 resilient stocks with low risk scores.
- Income focused readers who want yield backed by robust cash flows can round out their research by checking companies featured in the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com