
Is Cal-Maine Foods (CALM) Undervalued As Its Shares Slide And P/E Sends Mixed Signals?
Cal-Maine Foods (CALM) drew attention on 23 September 2026 after its share price slipped 1.91%, prompting investors to reassess the egg producer’s recent returns and current valuation profile.
That single-session drop sits on top of a wider pullback, with Cal-Maine Foods showing a 30-day share price return down 18.61% and a year-to-date share price return down 12.73%, while the 1-year total shareholder return has fallen 27.68%, despite multi-year gains remaining positive.
Scan how Cal-Maine Foods compares with other producers under pressure by reviewing a curated group of list of solid balance sheet and fundamentals (23 results)
After a slide like this, some investors lean into Cal-Maine Foods on weakness, while others sit on their hands and wait. Which camp does the current valuation really favor?
Most Popular Narrative: 15.5% Undervalued
On the most followed narrative, Cal-Maine Foods screens as undervalued, with an $81 fair value estimate sitting above the latest $68.48 close. This puts more weight on future cash generation than on the recent share price slide.
Expanding specialty egg and prepared foods offerings, including high growth cage free, pasture raised and ready to eat formats, is expected to lift average selling prices and shift the mix toward higher margin revenue streams. This is expected to support net margin expansion and earnings growth.
See why 18 investors see Cal-Maine Foods as 15% undervalued.
Result: Fair Value of $81 (UNDERVALUED)
Still, the Cal-Maine Foods narrative leans on fragile assumptions. A prolonged egg oversupply or another severe avian influenza flare up could quickly erode that perceived undervaluation.
Find out about the key risks to this Cal-Maine Foods narrative.
Another View: What Cal-Maine Foods’ P/E Is Really Saying
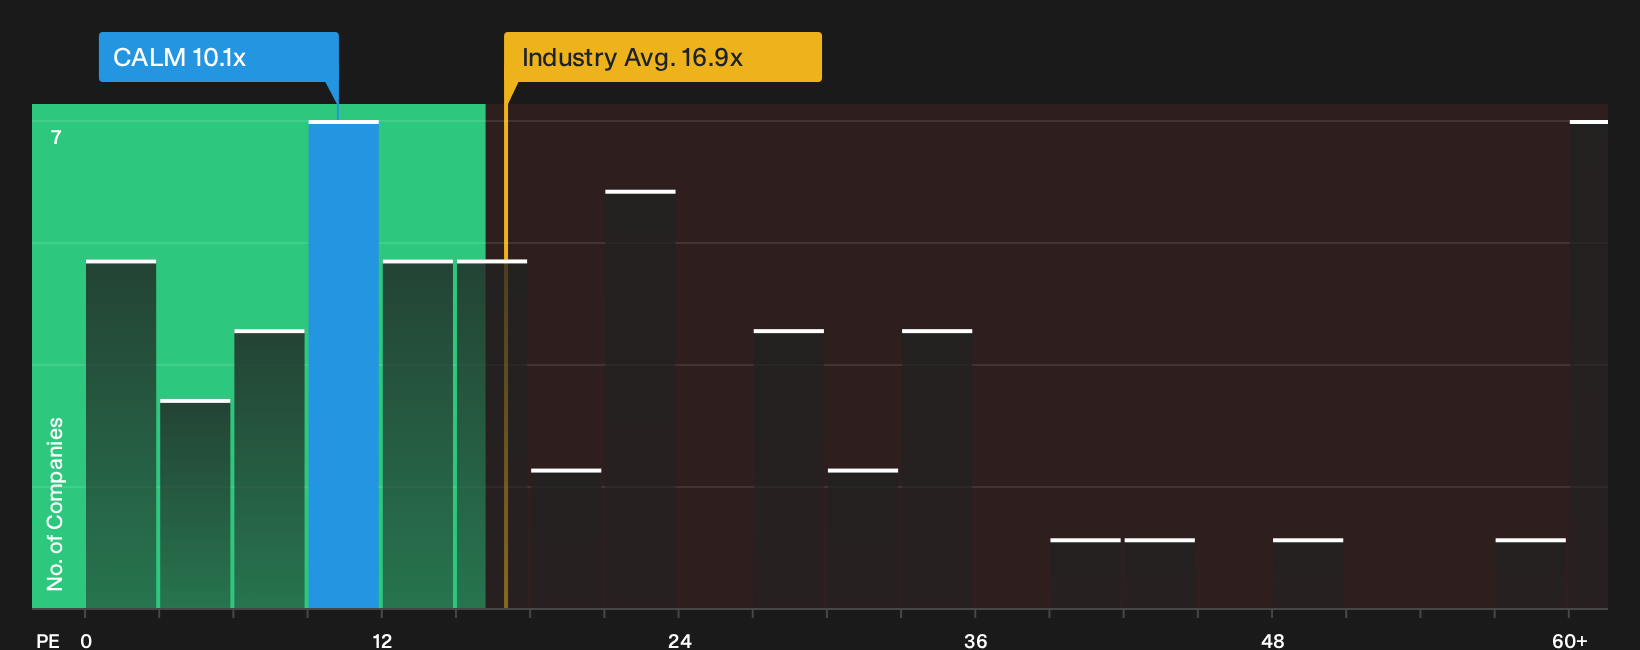
There is a twist once you move from that $81 fair value estimate to simple earnings multiples. Cal-Maine Foods trades on a 10.1x P/E, below the US Food industry at 16.9x and under the wider US market at 18x, yet above its own fair ratio of 5.5x.
This mix creates a split picture for investors. Compared with peers, the stock looks cheaper. Against the fair ratio that our model suggests the market could move toward over time, the P/E implies valuation risk if earnings disappoint or sentiment cools again.
For anyone weighing these conflicting signals, the key question is whether the discount to the sector matters more than the gap to that lower fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Cal-Maine Foods looks split, with investors weighing both pressure points and bright spots. Act while the data is fresh and check the balance of risks and potential upsides for yourself by reviewing the 1 key reward and 2 important warning signs
Looking for more Cal-Maine Foods investment ideas?
If Cal-Maine Foods has you rethinking your next move, do not stop here. Broaden your watchlist now or risk missing more suitable opportunities nearby.
- Target stronger balance sheets by reviewing companies filtered through the list of solid balance sheet and fundamentals (23 results), which pair financial resilience with cleaner fundamentals.
- Zero in on value opportunities by scanning the 30 high quality undervalued stocks, which highlights businesses trading below their assessed worth.
- Strengthen your income focus by checking the 7 dividend fortresses, which surfaces higher yielding payouts with supporting metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com