
What Cardinal Health Stock's Specialty Push Means For Shareholders
- Recent commentary highlights Cardinal Health's push toward a more diversified, specialty-led model across Pharmaceutical and Specialty Solutions and other higher value healthcare services, supported by its established role in drug and medical product distribution.
- Cardinal Health is also featured as a key participant in the fast expanding medical textile sector, which points to additional product and service avenues alongside ongoing share repurchases that concentrate earnings across a smaller equity base.
- We will now look at how Cardinal Health's specialty led push in pharmaceuticals and services could influence the existing investment narrative.
Cardinal Health Investment Narrative Recap
To own Cardinal Health, you need to be comfortable with a large scale distributor that is steadily tilting toward specialty pharma, Biopharma Solutions and higher margin service lines. The key short term swing factor is whether that specialty led mix can keep lifting earnings on a relatively thin 0.7% net margin while funding debt and investment needs.
The biggest operational watchpoint is still execution risk around quality control and the repaired Global Medical Products and Distribution segment. Recent commentary on specialty momentum does not materially change that. It simply raises the bar on Cardinal Health to grow higher value services without letting recalls, inflation exposed input costs or insider selling headlines distract from delivery.
The most relevant recent theme is the emphasis on Cardinal Health as a core player in the rapidly expanding medical textile market. That fits directly with the GMPD turnaround story, since this unit manufactures gowns, drapes and other single use apparel that tie into broader medical textile demand across hospitals and outpatient centers.
For catalysts, investors can link medical textiles to volume growth and better product mix in Cardinal Health branded items. The operational upside sits in higher utilization of existing production and distribution assets, while the risk side sits in quality oversight, commodity linked input costs and the need to prevent any repeat of subpotent product issues that could blunt customer confidence.
Cardinal Health Forecasts and What They Assume
Cardinal Health's current story hinges on analysts expecting revenue to rise by 5.4% each year and earnings to move from US$1.7b today to a consensus of US$3.0b by 2029, which is an increase of about US$1.3b in absolute profit. That profile rests on a margin shift from 0.7% to 1.0% and a share count that analysts see shrinking by about 2.11% a year, so per share earnings rise faster than total profit even before any change in what investors are willing to pay on a P/E basis.
Cardinal Health's narrative projects US$297.6b revenue and US$3.0b earnings by 2029. This requires 5.4% yearly revenue growth and about US$1.3b earnings increase from US$1.7b today.
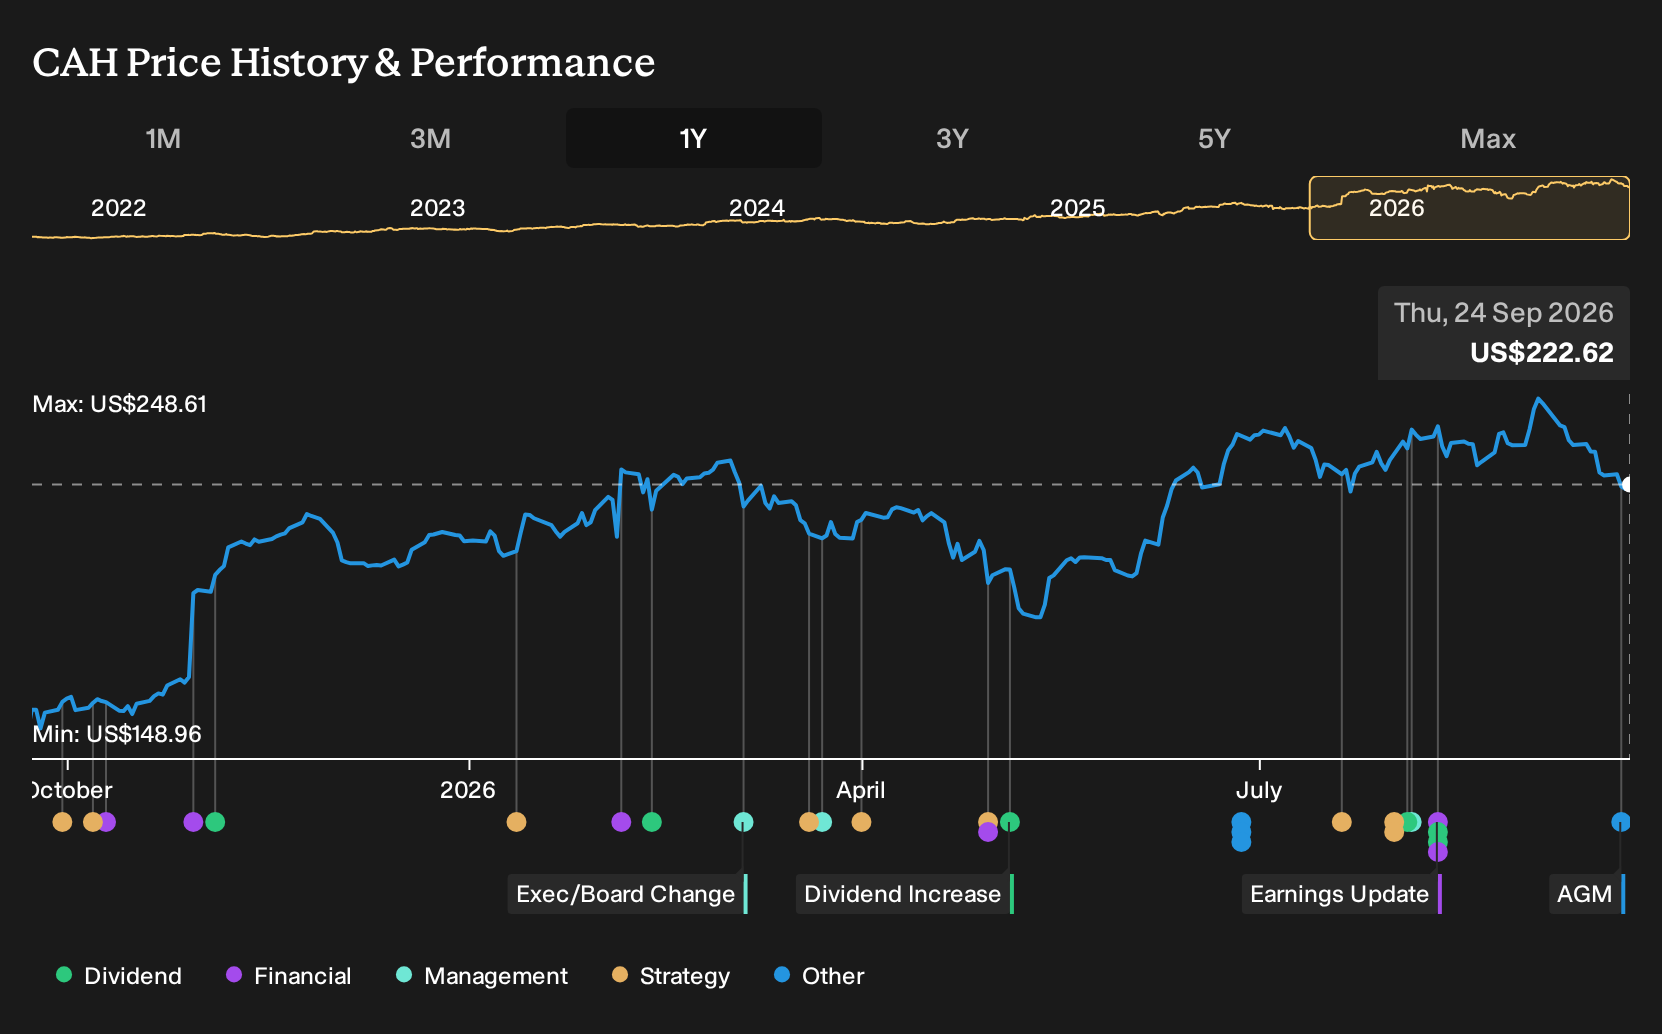
Discover why Cardinal Health's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value views on Cardinal Health inside the Simply Wall St Community stretch from about US$271 to roughly US$742 across 3 separate retail investor models, so you are looking at very different scripts for the same stock. When you consider that alongside product quality recall risk and the medical textile growth angle, you can see why opinions diverge so widely. Explore those contrasting viewpoints before deciding how Cardinal Health fits into your own thesis.
Explore 2 other Cardinal Health fair value estimates, including one that suggests there could be up to 233% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Cardinal Health research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cardinal Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Cardinal Health's overall financial health at a glance.
Looking for more Cardinal Health style investment ideas?
If the Cardinal Health story has sharpened your thinking about balance sheets, cash flows and risk, use that same lens to hunt for other companies that fit your preferences. The Simply Wall St Screener can help you quickly filter the market down to a manageable shortlist that matches the quality, income or downside profile you care about most.
- If capital preservation is a priority and you want businesses that aim to limit downside, start with our focus on resilience through the 31 resilient stocks with low risk scores.
- For investors who care about income and want to see which companies combine higher yields with fundamental support, take a look at the 7 dividend fortresses.
- If you are searching for quality operators that may not yet be widely followed but still have solid financial underpinnings, broaden your watchlist with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com