
Does India Can Plant Groundbreaking Change The Bull Case For Crown Holdings (CCK)?
- Crown Holdings held a groundbreaking ceremony in September 2026 for its first beverage can plant in Unnao, Uttar Pradesh. The facility is designed with two production lines and capacity of about 2,200 million aluminum cans per year, with operations planned to start in the second half of 2027.
- The India facility is intended to support both alcoholic and non alcoholic beverage demand using advanced manufacturing and sustainability standards. The company maintains guidance for about US$550 million of 2026 capital expenditures across its global capacity projects.
- We will look at how Crown Holdings' broader investment narrative is shaped by the India plant's large scale beverage can capacity build.
Compare Crown Holdings' India build out with other packaging players that are being priced for a similar story by scanning our hand picked 30 high quality undervalued stocks that already combine scale projects with solid fundamentals.
Crown Holdings Investment Narrative Recap
To own Crown Holdings, you need to believe that global demand for recyclable metal packaging stays healthy enough for the business to keep its plants full while converting that volume into solid cash flow. The Unnao build out fits that view but does not change the near term picture. That picture still hinges on executing current projects and keeping utilization high in North America and Europe.
The biggest short term risk remains cost pressure from freight, energy and industrial gases, especially where contracts lag input spikes. Flat to slightly softer 2026 Americas Beverage income versus 2025, along with Brazil softness and Crown Holdings' relatively high debt load, could limit how much earnings progress these capacity additions translate into over the next few years.
The India ground breaking is the clearest recent proof that Crown Holdings is leaning into long term beverage can demand using sizable, committed capacity. Management expects about US$550 million of 2026 capex across Brazil, Greece, Spain and India. Timely ramp up and cost control on this program are central to the equity story and to sustaining free cash flow.
There is an operational trade off for investors to weigh. The India facility, where roughly 70% of volume is under long term commitments, can support visibility on volumes once online. However, it also concentrates execution risk if demand growth slows after temporary boosts such as the World Cup or if input costs stay elevated relative to contracted price recovery.
Crown Holdings' current analyst story points to revenues of US$14.4b and earnings of US$937.0m by 2029, based on an assumed 2.9% yearly revenue growth rate and an increase in earnings of about US$153.0m from US$784.0m today.
Uncover why Crown Holdings' fair value indicates a 29% potential upside to its current price before that valuation gap starts to close.
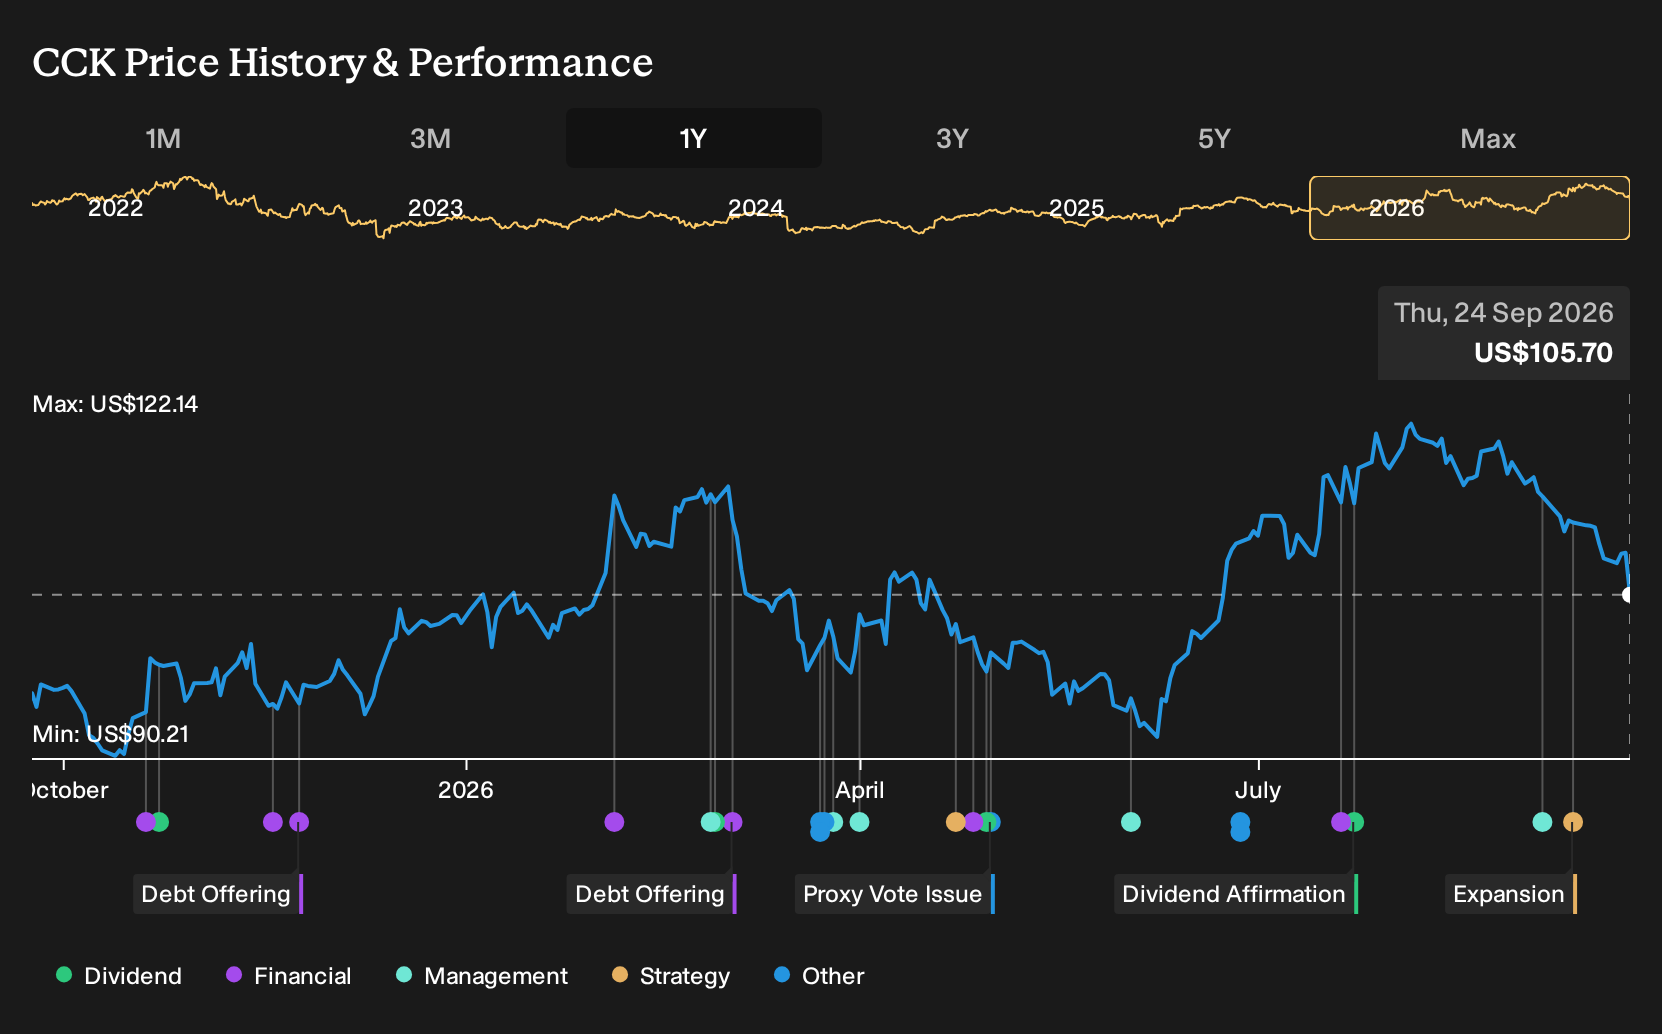
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community stretch from just US$76 to more than US$386.3b, which shows how far apart retail views on Crown Holdings can be. You see a P/E near 15x and recent volume catalysts like the World Cup. You also see cost inflation risks that could blunt the benefit of new India capacity. That mix of optimism and caution is exactly why it is useful to explore multiple community viewpoints before forming your own stance.
Explore 3 other Crown Holdings fair value estimates, including one that suggests as much as 365476292072% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Crown Holdings research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Crown Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crown Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Crown Holdings?
If the Crown Holdings story has you thinking about capacity, balance sheets and pricing power, it can help to line it up against other businesses with different risk and income profiles. The Simply Wall St Screener lets you quickly scan groups of companies that match the type of opportunity you are hunting for, rather than scrolling through tickers one by one.
- For investors willing to accept higher volatility in return for potentially outsized moves, scan through 8 elite penny stocks with strong financials that already clear basic quality and financial filters.
- If you want to anchor your research around valuation and fundamentals, start with the 30 high quality undervalued stocks that blend stronger balance sheets with support from their cash flows.
- Readers who prefer defense over drama can focus on resilience by filtering for 31 resilient stocks with low risk scores that score well on financial strength and earnings stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com