
Sigma Lithium (SGML) Stock May Be Undervalued As Bullish New Coverage Starts
Sigma Lithium has seen its share price move around sharply in recent years, and that volatility raises a straightforward question for investors who care about numbers first. Is the current US$9.98 price tag adequately supported by the revenue that the business is generating today?
- Over the past 3 years the stock has fallen 68.9%, which puts a spotlight on whether the market is now asking too much or too little in terms of sales against price.
- Fresh coverage from JPMorgan that highlights Sigma Lithium as an "operational de-risking plus brownfield growth" story can feed expectations about future production volumes and, in turn, the level of sales that might eventually underpin the current valuation.
- There is a second opinion on Sigma Lithium worth weighing. See what analysts think Sigma Lithium's shares could be worth.
The issue now is whether Sigma Lithium's current market value is properly aligned with its sales when measured against the Fair Ratio benchmark.
If you are weighing Sigma Lithium in the context of high demand for critical minerals, it can help to compare it with other listed producers and projects via 36 best rare earth metal stocks.
Does Sigma Lithium Look Undervalued on Sales?
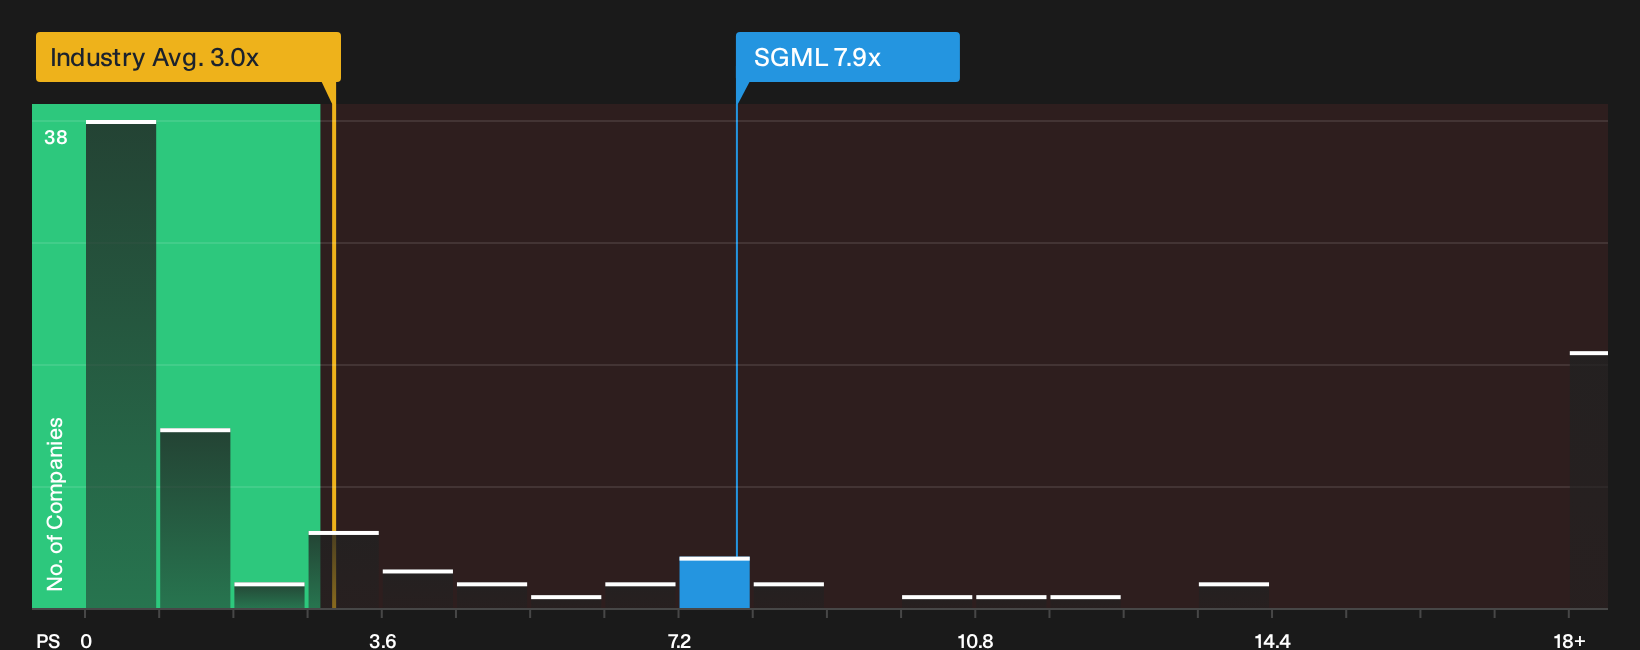
The P/S multiple suits Sigma Lithium because most of the focus is on revenue capacity and project build out rather than mature earnings. At a P/S of 7.9x, the stock trades well above the broader metals and mining sector, where the average is 3.0x, and it also sits far above the peer group average of about 1.1x. That gap tells you investors are already paying a premium for each dollar of current sales.
Freshly bullish coverage from JPMorgan, which frames Sigma Lithium as an operational de risking and brownfield expansion story, helps explain why the market is willing to assign this richer P/S tag. The Fair Ratio model, which blends the company’s growth profile, margins, size and risk, points to a higher multiple than where the shares trade today, so the current P/S screens as undervalued on that tailored benchmark even though it is elevated against sector and peer norms. This tension between a premium headline multiple and a discounted Fair Ratio signal is exactly what the detailed breakdown behind. Explore the numbers behind Sigma Lithium's P/S valuation.
The Sigma Lithium Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Sigma Lithium pick up where the valuation puzzle leaves off by spelling out what future path for growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. Instead of giving a single figure like a fair value number or ratio, they describe the underlying storyline that figure relies on so you can watch how closely reality tracks that script over time.
One of the top community narratives on Sigma Lithium: 42% undervalued
"Highly diversified and increasingly long-term offtake agreements, often with prepayment features, are stabilizing revenues and supporting working capital…"
Discover why this Narrative puts Sigma Lithium at 42% undervalued.
One more crucial piece for Sigma Lithium that the numbers alone cannot answer
Price, projects and ratios only go so far if you do not know who is steering Sigma Lithium and how their incentives line up with your interests. See who runs Sigma Lithium and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com