
H&M (OM:HM B) Margin Rebound Sharpens The Stock Debate
H & M Hennes & Mauritz came into this earnings print with the share price under pressure, down about 12% over the past month, which set the bar emotionally low for many holders. The headline is that profit quality, not sales fireworks, is doing the heavy lifting. Q3 operating margin landed at 10.6% and the trailing 12 month operating margin now sits at 9%, while net profit margin on that same trailing view is 6%. For a global fashion retailer long judged on squeezed margins, this report puts profitability back at the centre of the investment debate.
Love the margin progress at H & M Hennes & Mauritz, but want retailers with even stronger balance sheets backing it up? Compare this earnings story against our list of solid balance sheet and fundamentals stocks (200 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): SEK57,189m vs. SEK57,017m (stable, modest uplift year over year)
- Net Income (Q3 2026 vs Q3 2025): SEK4,123m vs. SEK3,229m (up about 27.7%)
- Basic EPS (Q3 2026 vs Q3 2025): SEK2.58 vs. SEK2.01 (up about 28.3%)
- Operating Margin (Q3 2026 vs prior 12 months): 10.6% for the quarter vs. 9% on a trailing 12 month basis (margin profile skewed toward a stronger Q3)
Prefer clean, visual charts to another wall of earnings commentary and spreadsheet rows? See H & M Hennes & Mauritz's full financial picture with a focus on its profitability and margin profile in the interactive company report for H & M Hennes & Mauritz.
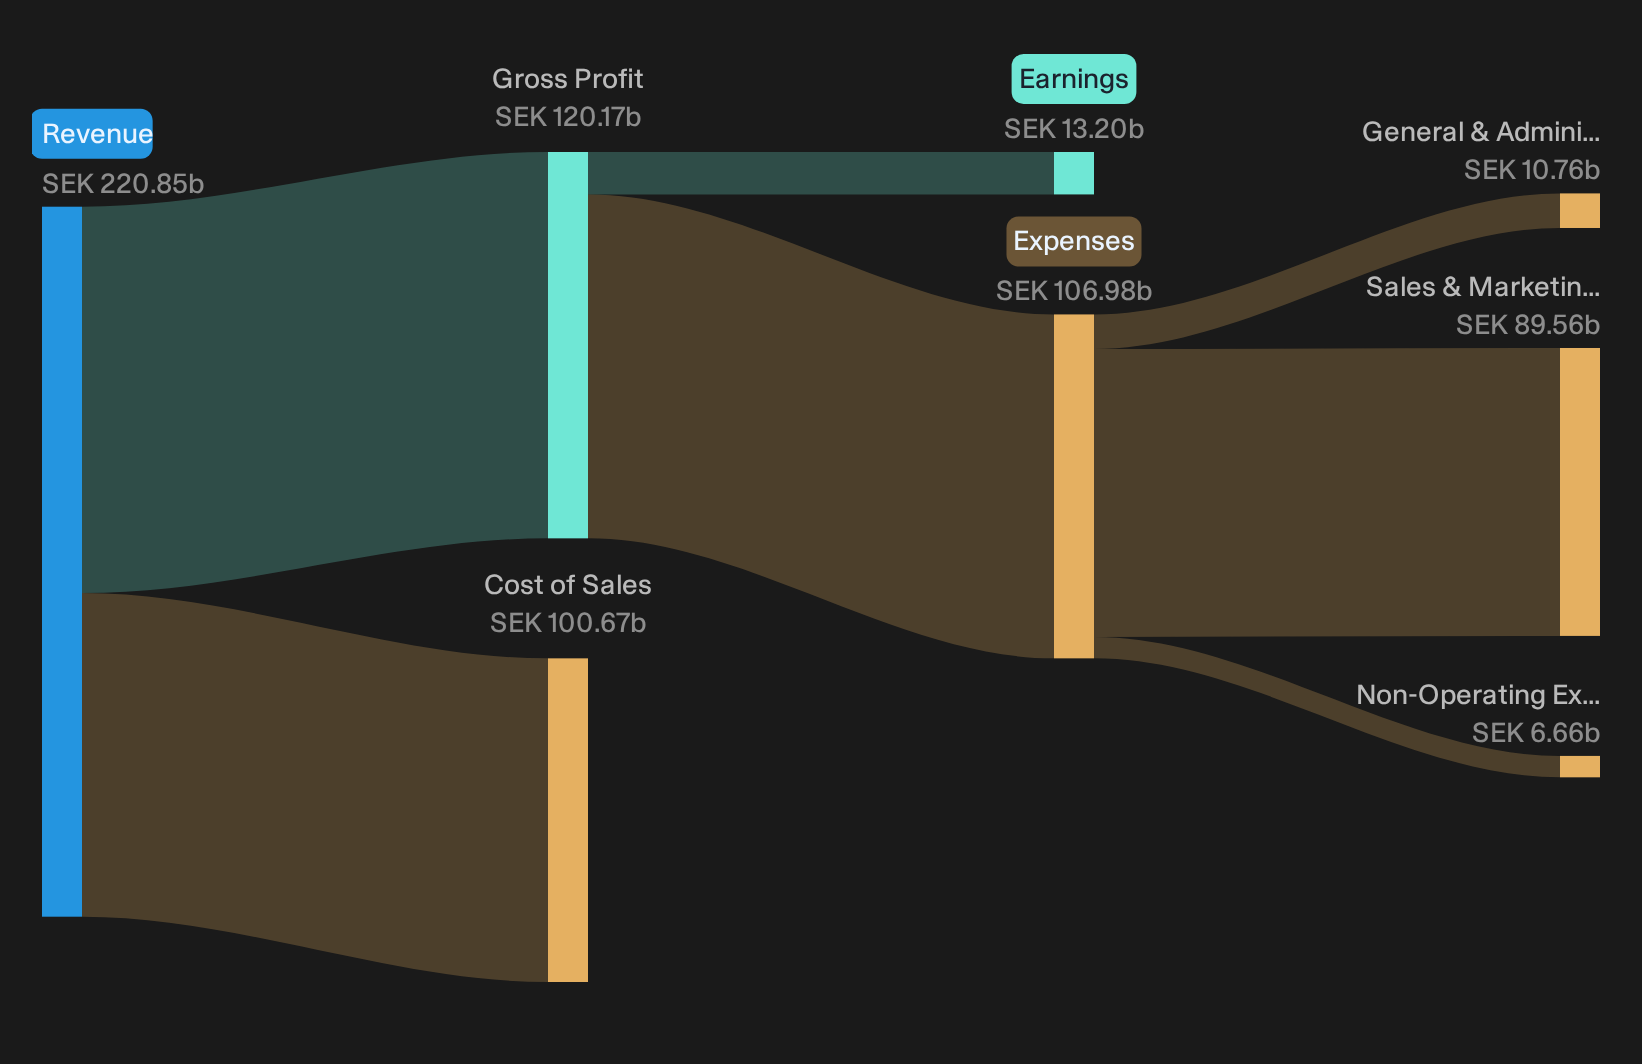
H&M margin thesis meets real-world checkpoints
Bulls argue H&M can turn sourcing tweaks, better product mix and tech investments into structurally higher profitability. This quarter moves that idea from slide deck to income statement. Operating margin of 10.6% and a trailing 9% compares with management explicitly talking about progress toward a roughly 10% long term target. That is a key milestone for any margin upgrade story.
Cost control, not flashy sales, is doing the work. Selling and admin expenses declined 1% even as RFID, self checkout and ERP spending continued. Gross margin of 54.0% did benefit from a one off tariff adjustment, yet management still points to underlying sourcing gains and shorter lead times as positive drivers.
Inventory is the main area where the bullish script is not fully proven yet. Stock levels increased, partly from goods in transit, so the promise of leaner working capital is still a work in progress.
Reveal where the surface looks calm but the models start to disagree on H & M Hennes & Mauritz's next few years, and see exactly where the consensus might quietly break on revenue, margins and EPS using the analyst estimates for H & M Hennes & Mauritz.Evaluating H&M Bear Fears On Margins And Execution
Bears argue H & M Hennes & Mauritz cannot protect profitability once labor, material and logistics costs bite and that footprint rationalization plus tech spend will drag on returns. This quarter cuts against parts of that story but leaves other worries intact. Gross margin at 54.0% looks healthy, yet roughly 1.6 percentage points came from a tariff one off, so underlying protection against rising input costs is less clear. Selling and admin expenses fell 1% even with ERP and digital investments, which challenges the view that structural cost inflation must overwhelm margin efforts.
Inventory rising by SEK1.4b and described as elevated into Q4 supports concern about supply chain volatility and markdown risk, especially with higher promotional activity and transport costs flagged. Store optimization touching about 20% of locations without large disclosed write downs is a partial miss for the most pessimistic closure thesis, but the execution risk from ERP and warehouse consolidation remains very real.
After ERP integration issues, rising inventory and ongoing warehouse consolidation, it is fair to ask whether these are isolated execution hiccups or early signs of deeper fragility. Review the structured risk scoring and hidden warning flags already mapped in the risk analysis for H & M Hennes & Mauritz which shows 1 important warning sign.Own Your Next Investing Move
If the margin story at H & M Hennes & Mauritz has your attention after this earnings print, register free with Simply Wall St and add it to your Watchlist to track price against fair value and watch how profitability trends evolve. When you decide to take a position, keep control of the bigger picture with the Portfolio Command Center that filters out noise and highlights only the key updates that matter for your holdings. For longer term thinking, compare your view with thousands of other investors inside the Community to see how sentiment and thesis work in real time. Spot potential catalysts and risks early so you can act with confidence before the wider market catches up.
Seeking Alternatives Beyond H&M?
Fresh ideas tend to move first, and late money chases. Spot potential breakout momentum while it still flies under the radar. Do not delay; consider acting early based on your own research and judgment.
- Track resilient performers that may hold up when others wobble by scanning the curated 230 resilient stocks with low risk scores before the crowd starts bidding them up.
- Consider structural spending shifts into key infrastructure by reviewing the hand picked 39 power grid technology and infrastructure stocks while sentiment is still catching up.
- Look at companies building the backbone of machine intelligence by scanning the focused 84 AI infrastructure stocks while valuations may still be adjusting.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com