
Evonik Industries (XTRA:EVK) Stock Looks Fully Priced After Its 36% Run
Evonik Industries has delivered a strong share price run so far this year, and that puts the focus squarely on whether the current valuation is adequately backed by its earnings. With the stock now well above where it started the year, investors are asking if the recent performance leaves enough support in the underlying profit story.
- The share price is up 35.8% year to date, which puts more weight on the question of how fully the market is already pricing in Evonik Industries' earnings power.
- The group relies heavily on its ability to turn specialty chemicals revenue into consistent profit margins, so any shift in pricing, input costs or product mix can materially influence how much earnings support the current share price really has.
- The analysts covering Evonik Industries have run their own numbers. See what analysts think Evonik Industries's shares could be worth.
The issue now is whether Evonik Industries' present share price is well supported by the earnings that investors can reasonably expect from the business.
If you are weighing whether Evonik Industries' 35.8% year to date run is justified by its earnings, it can help to compare it with a focused list of 179 high quality undervalued stocks.
Has Evonik Industries Run Too Far on Earnings?
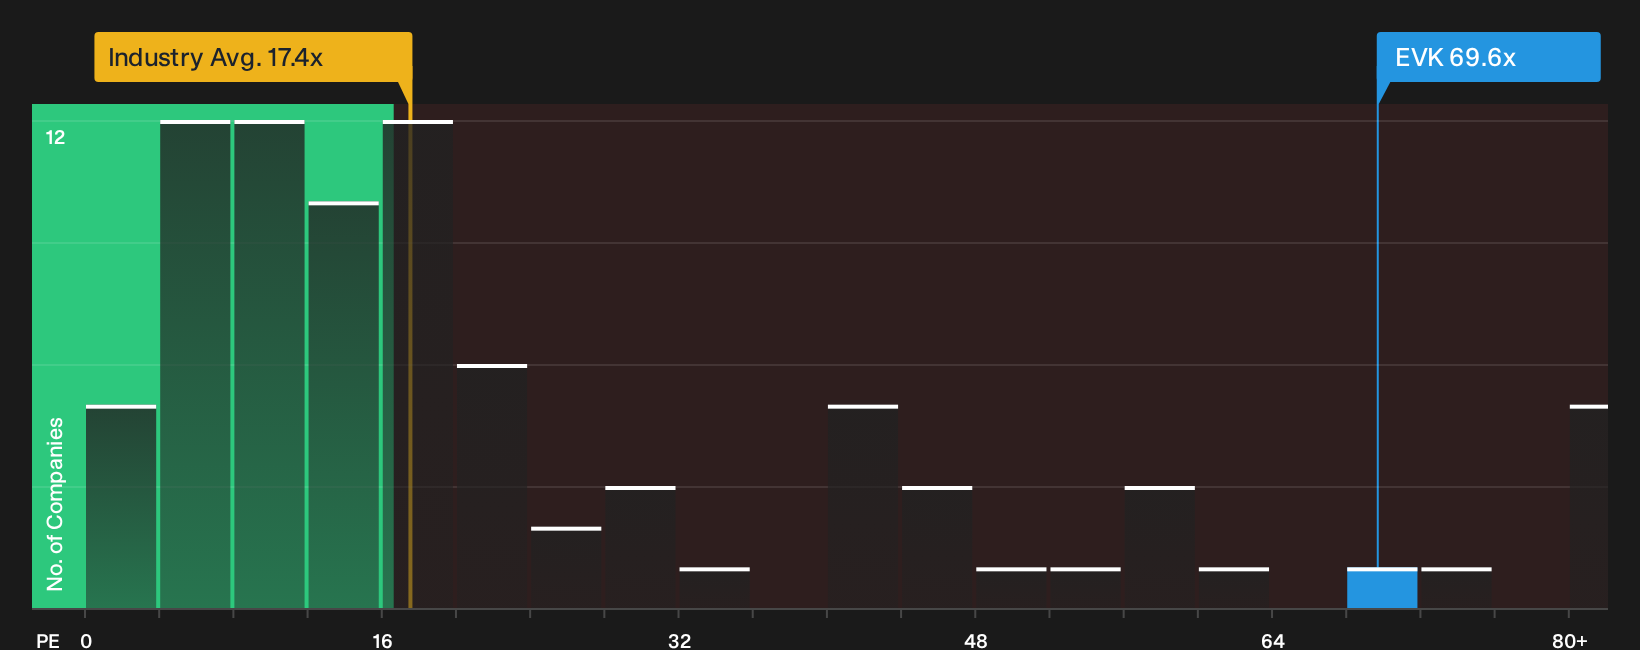
The P/E ratio is usually a straightforward way to see what investors are paying for each euro of Evonik Industries earnings. On that yardstick, the shares trade at about 69.6x, which is well above the Chemicals sector average of roughly 19.9x and also above the peer group level near 49.4x.
The tailored fair-value P/E suggested by the model, which blends Evonik Industries growth profile, profitability, size and risk characteristics, sits meaningfully lower than the current 69.6x. That gap indicates the stock appears overvalued on this earnings multiple, so anyone buying at today’s price is accepting a richer entry point than both industry norms and what the model implies for the business fundamentals. Explore the numbers behind Evonik Industries's P/E valuation.
The Evonik Industries Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Evonik Industries pick up where this valuation puzzle leaves off and spell out what kind of future growth, margin profile and earnings path would need to play out for the stock to be worth materially more or less than it is today on the market, all within the Community page. Rather than relying on a single multiple or model output, each narrative lays out the assumptions behind its view of fair value so you can later compare those expectations with the actual results that Evonik Industries reports.
Community views on Evonik Industries split between those who see decent support at current levels and those who think expectations run ahead of delivery.
Bull case: roughly fairly valued
"Ongoing portfolio shift towards high-margin specialty chemicals and away from commoditized businesses aligns with strict regulatory trends and customer demands for eco-friendly, high-value additives…"
Discover why this Narrative puts Evonik Industries at roughly fairly valued.
Bear case: 29% overvalued
"Intensifying regulatory pressure and the ongoing tightening of environmental standards in Europe and globally are set to force Evonik into higher compliance costs and potentially expensive upgrades…"
Explore why this Narrative puts Evonik Industries at 29% overvalued.
One more Evonik Industries check that sits alongside the share price
Before you stop at the P/E and growth stories, it is worth asking who is steering Evonik Industries and how their pay lines up with your interests as a shareholder. See who runs Evonik Industries and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com